Notice of Meeting:
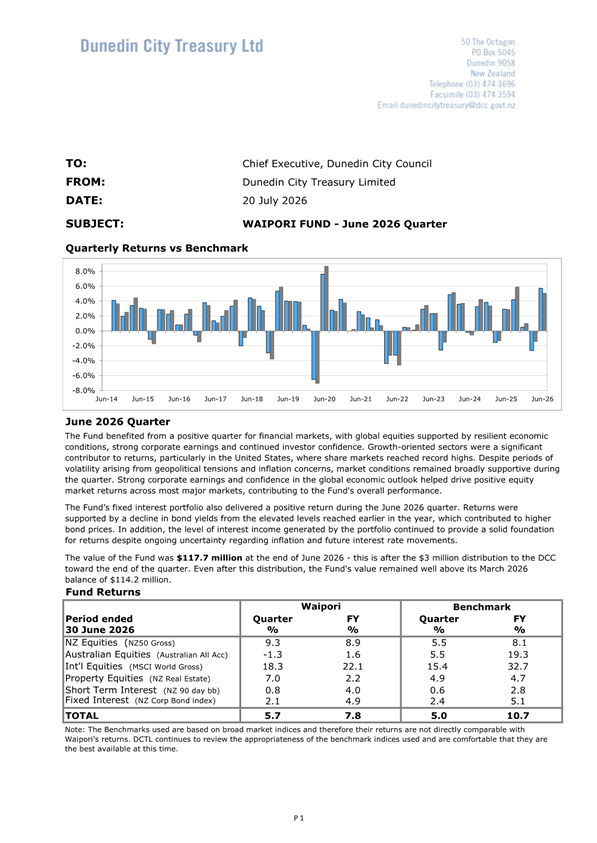
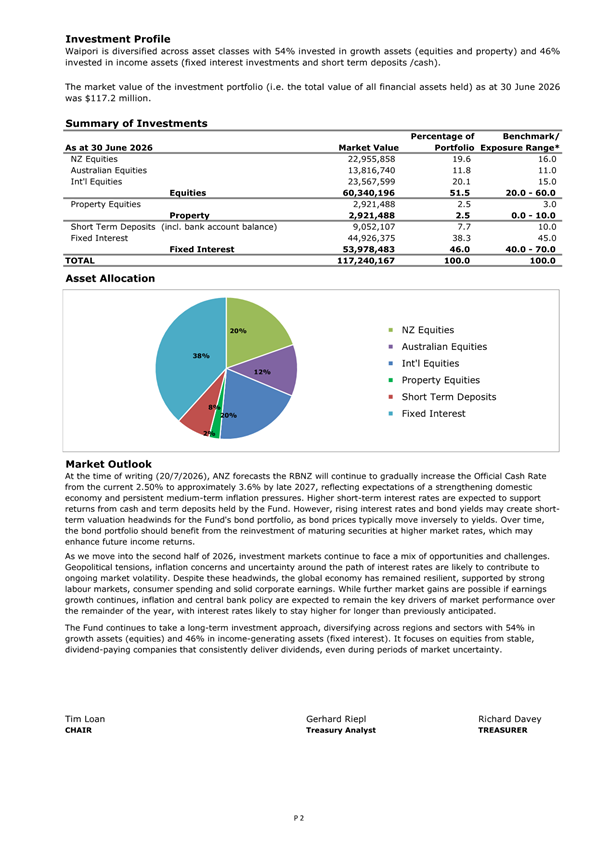
I hereby give notice that an ordinary meeting of the Finance
and Performance Committee will be held on:
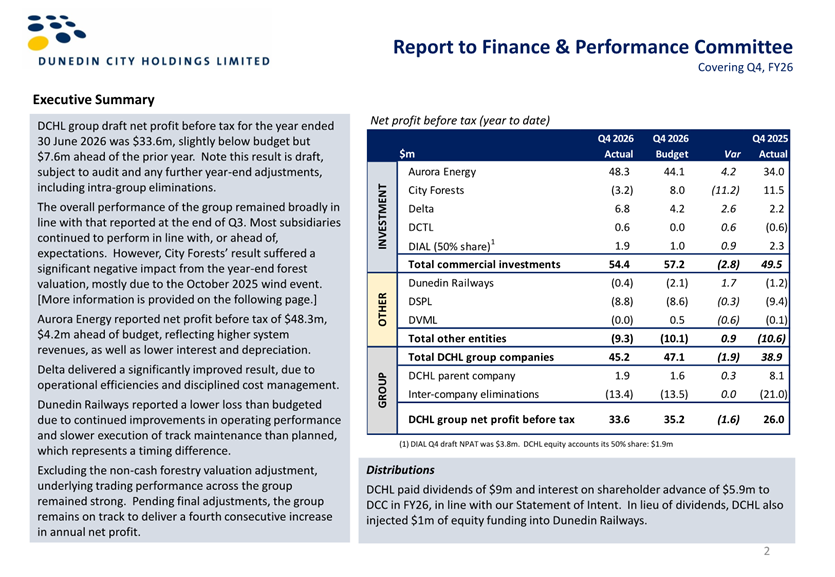
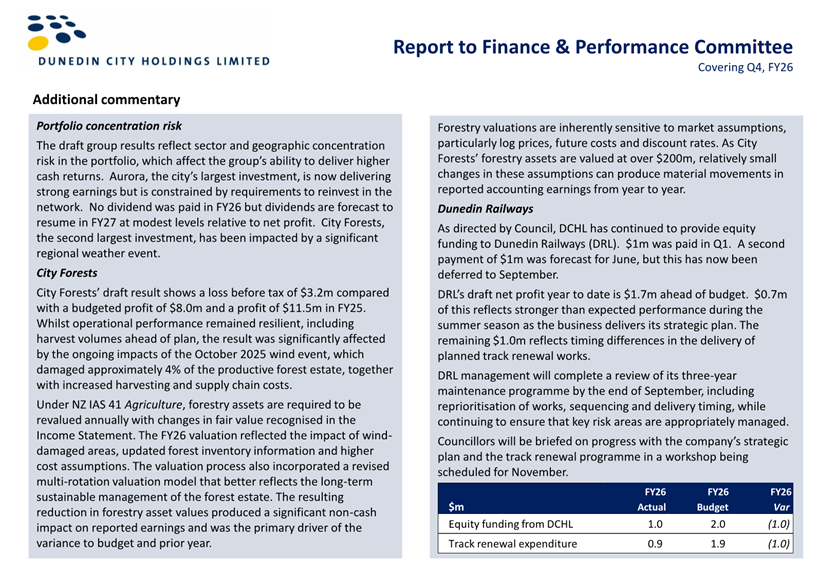
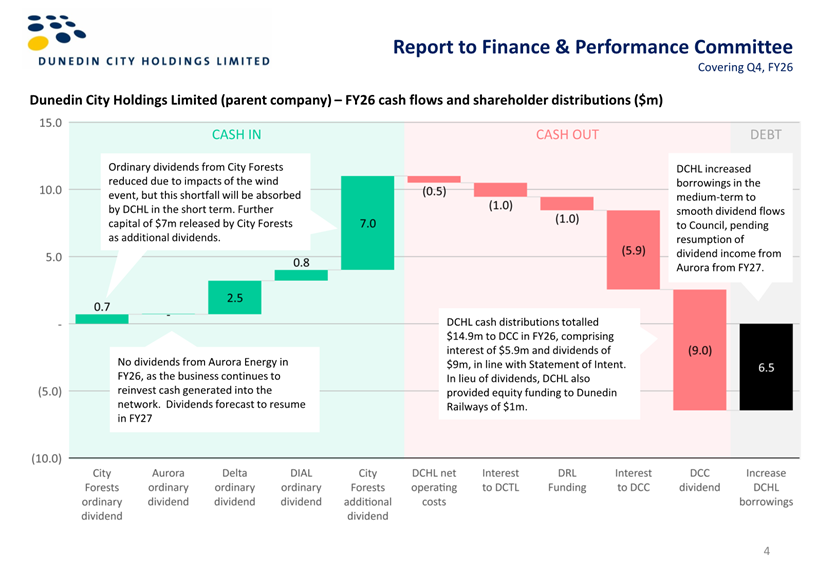
Date: Thursday
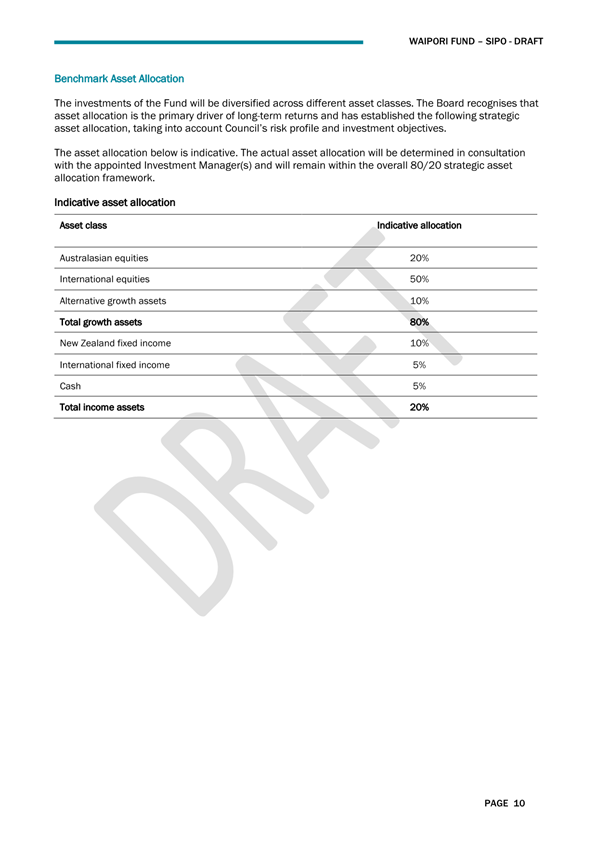
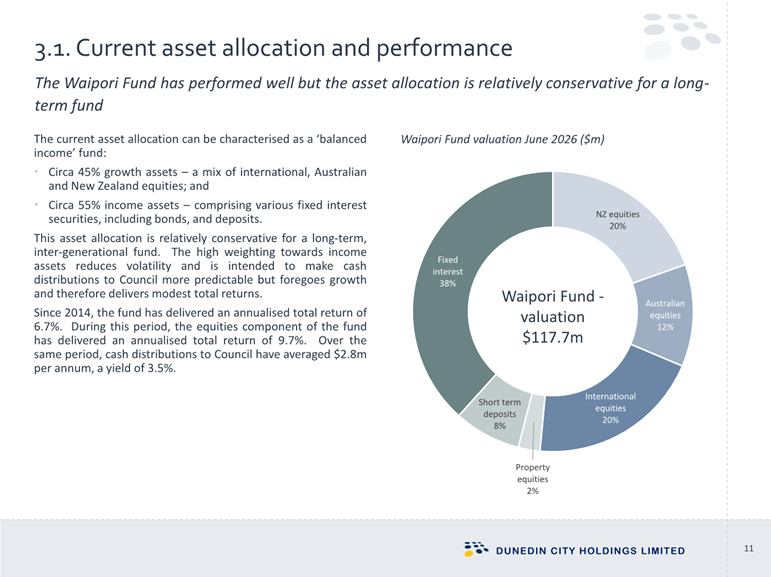
27 August 2026
Time: 9:00
a.m.
Venue: Council
Chamber, Level 2, Dunedin Public Art Gallery, The Octagon, Dunedin
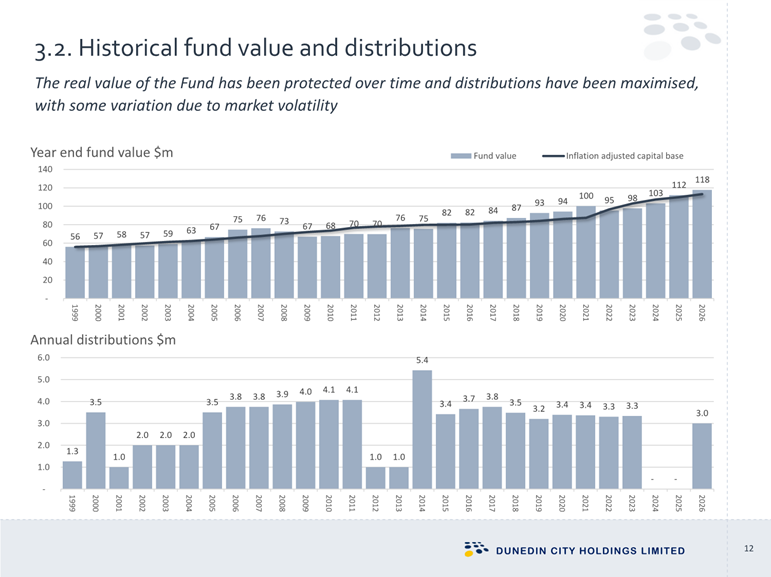
YouTube Link: https://youtube.com/live/-Gnd9wyHjus?feature=share
Sandy Graham
Finance and Performance Committee
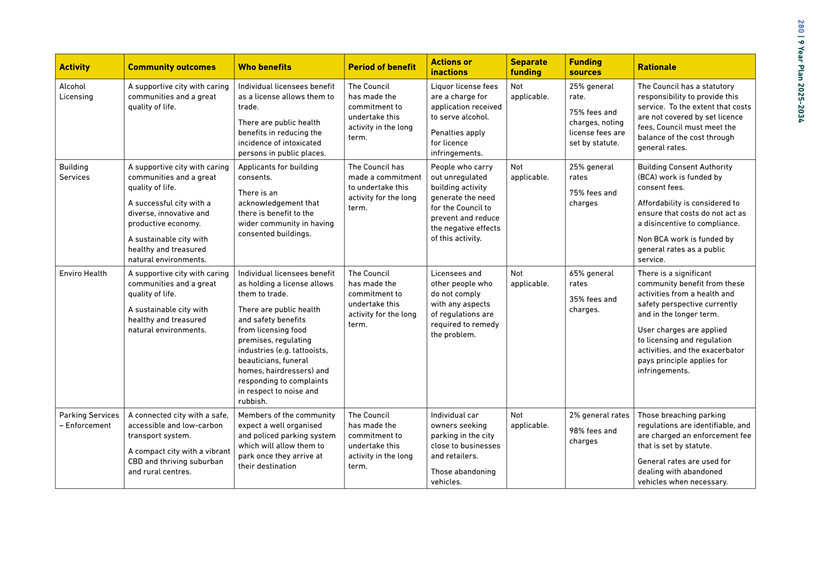
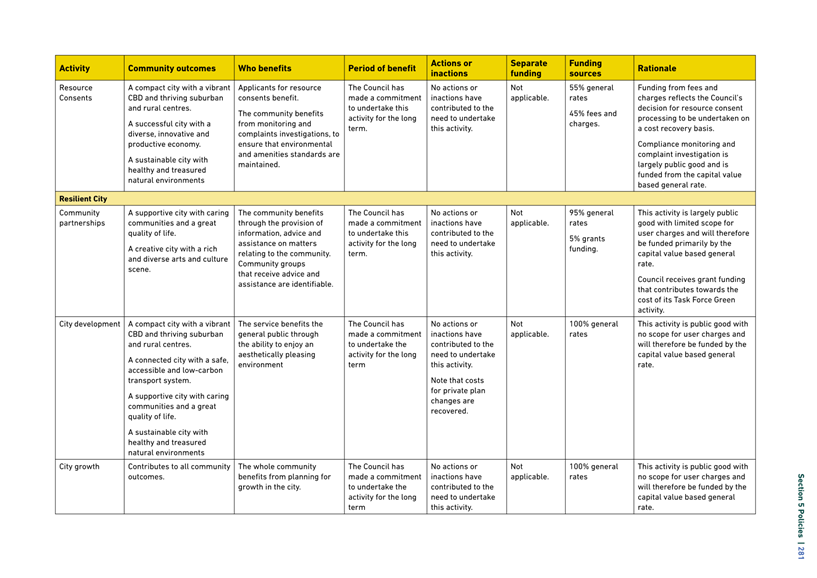
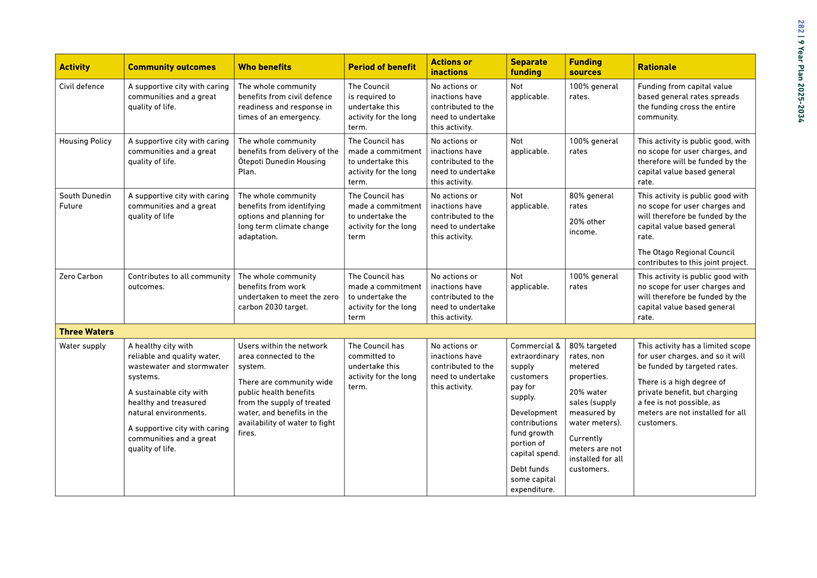
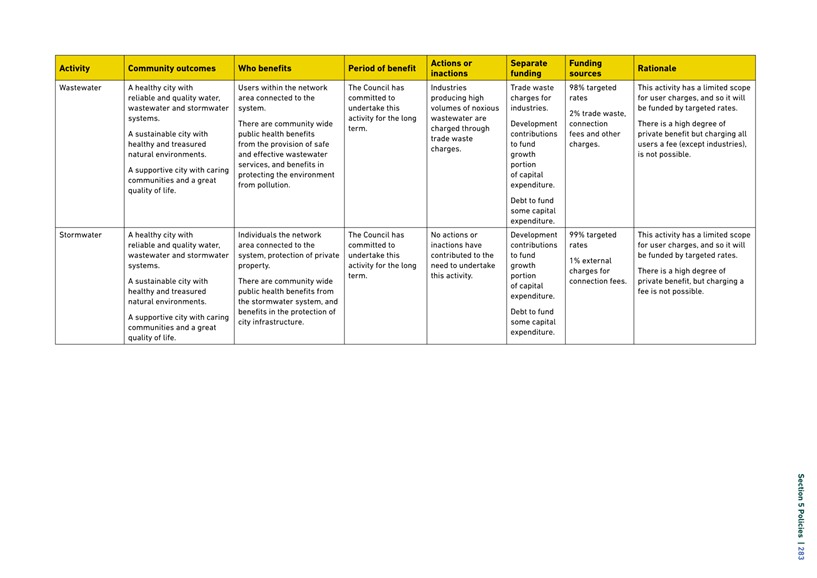
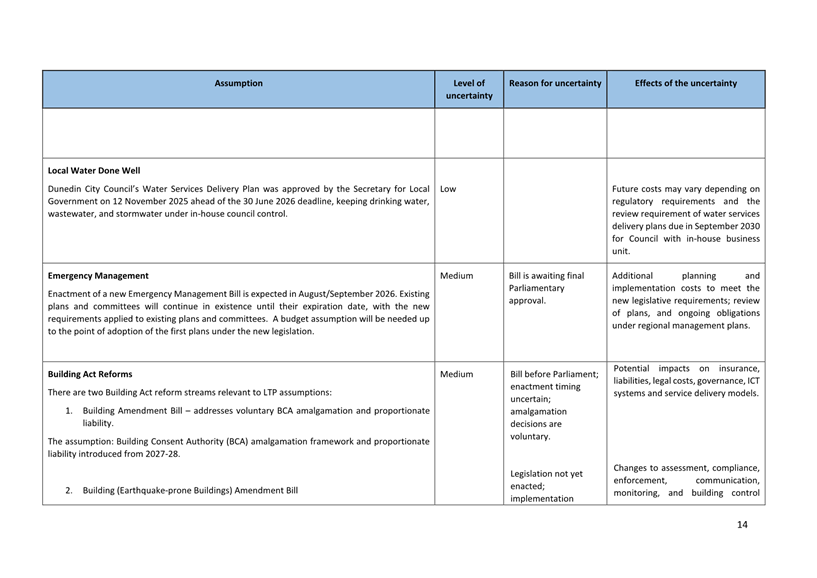
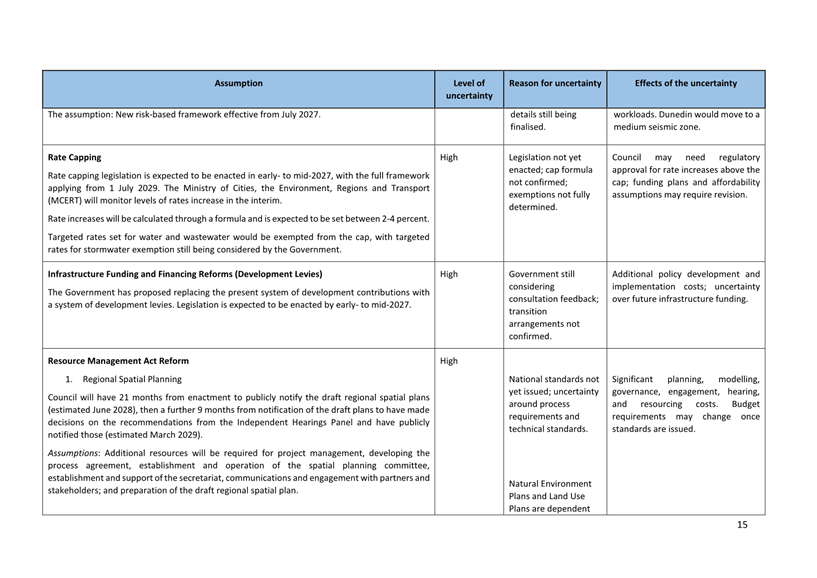
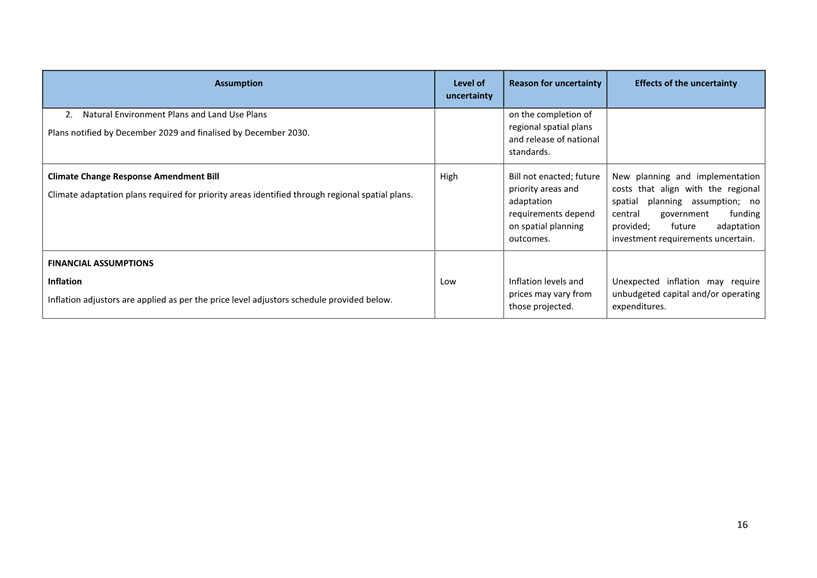
PUBLIC AGENDA
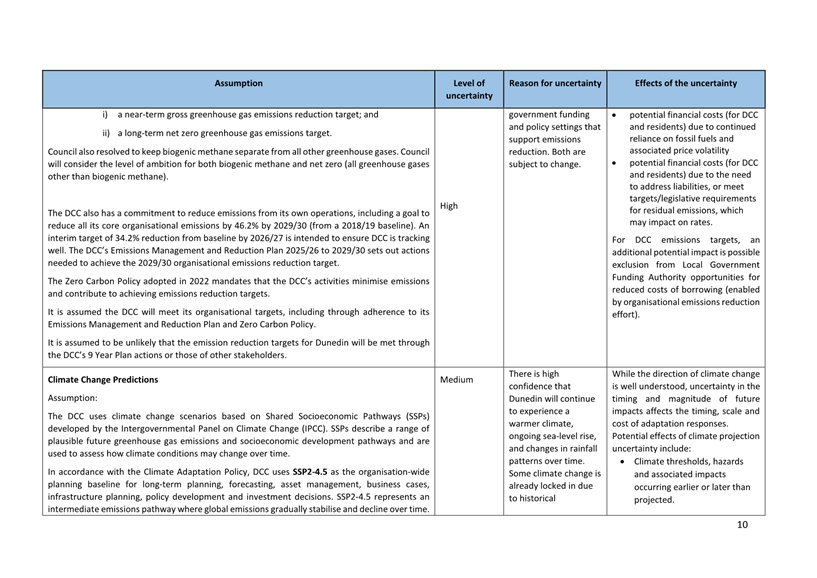
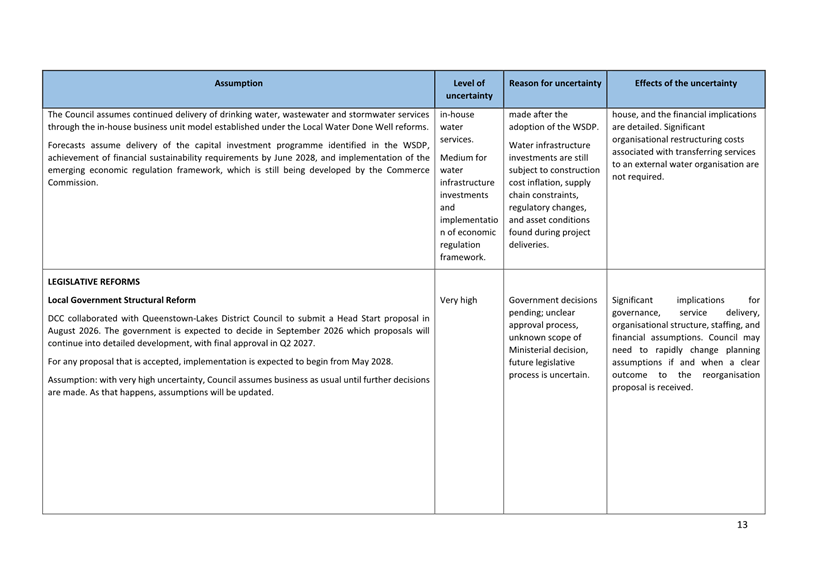
|
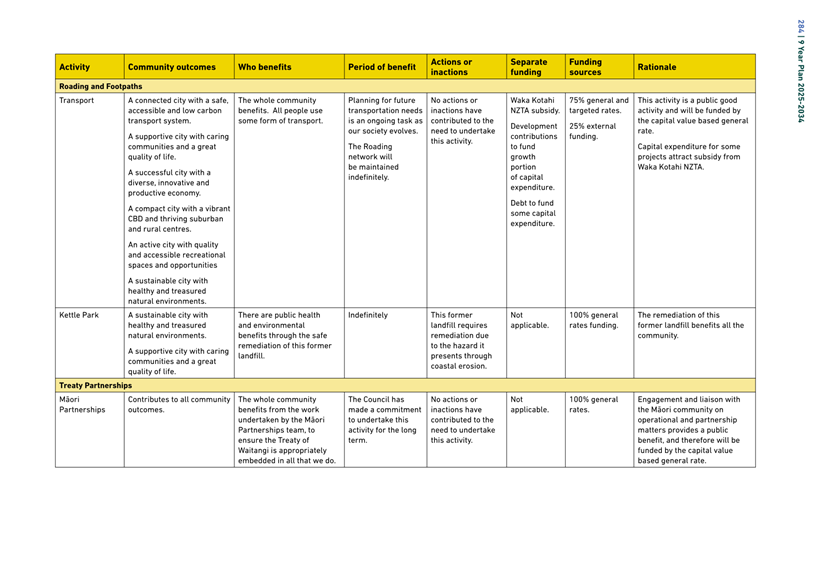
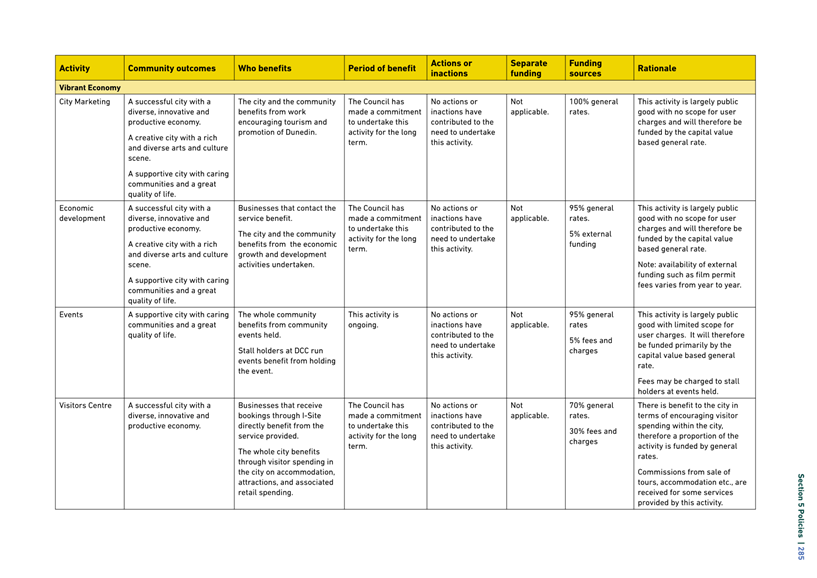
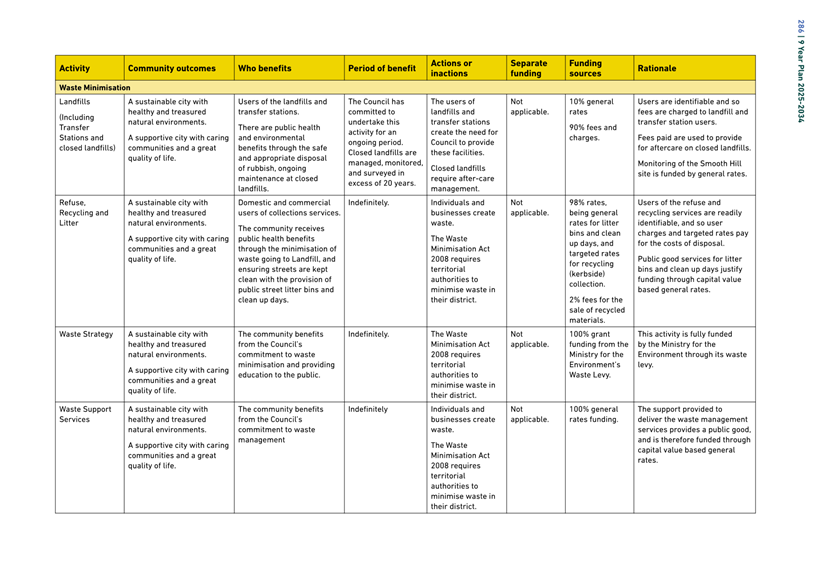
Co - Chairs
|
Cr Lee Vandervis
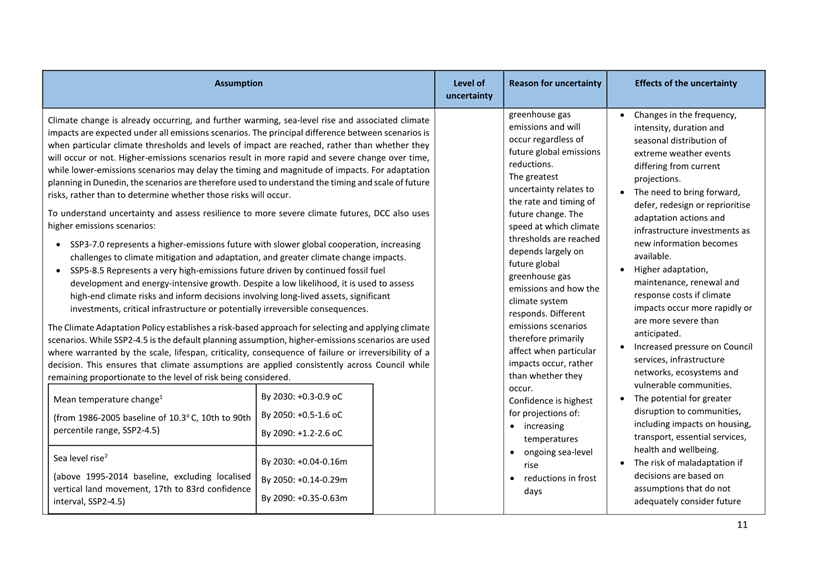
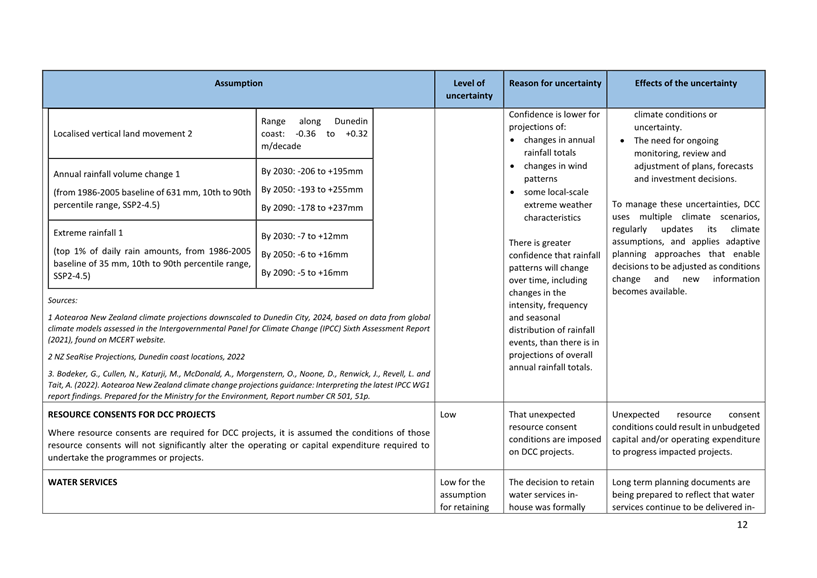
|
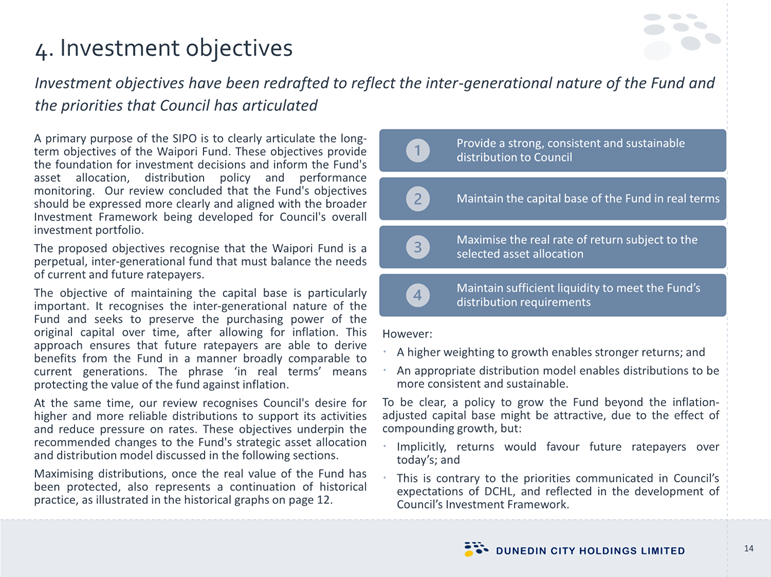
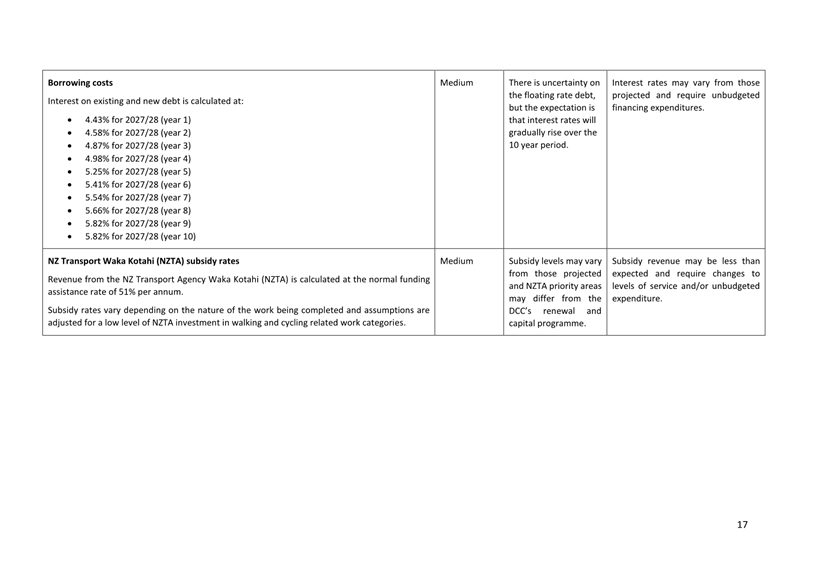
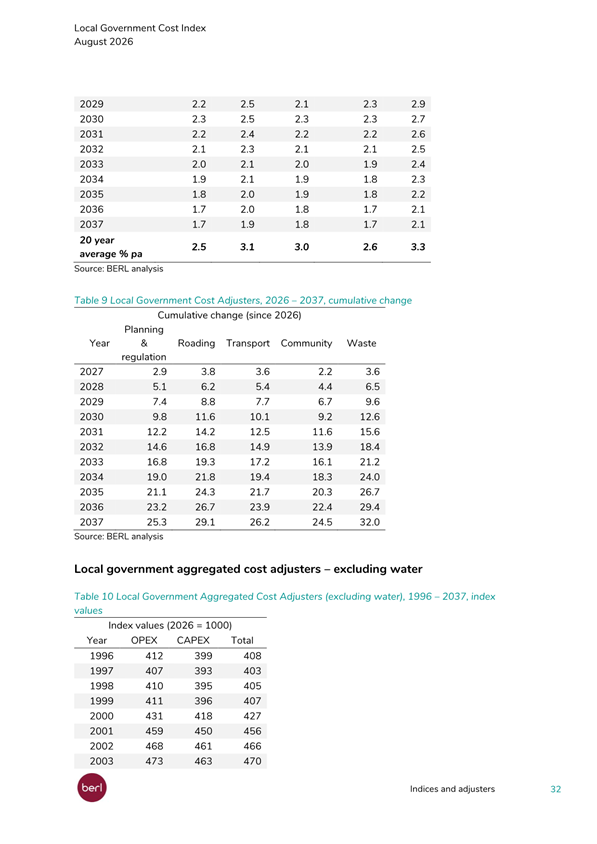
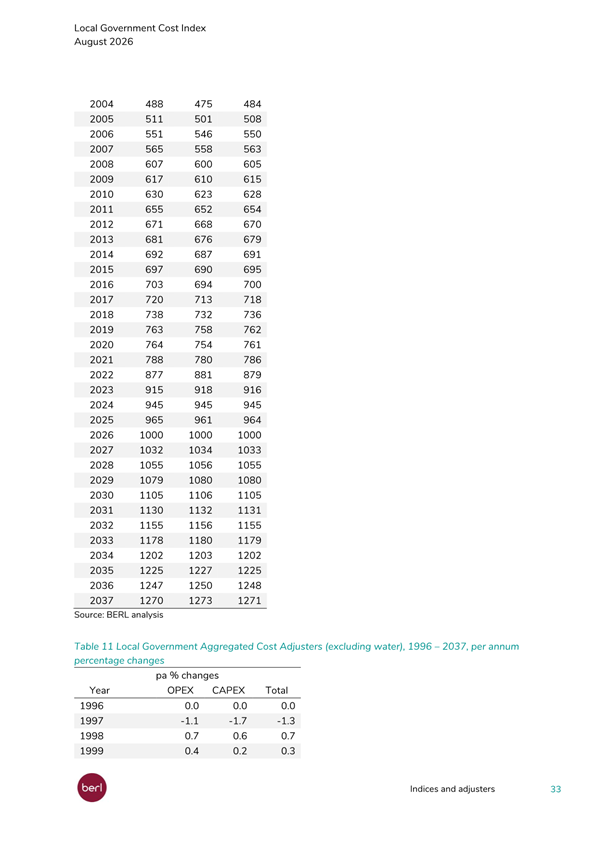
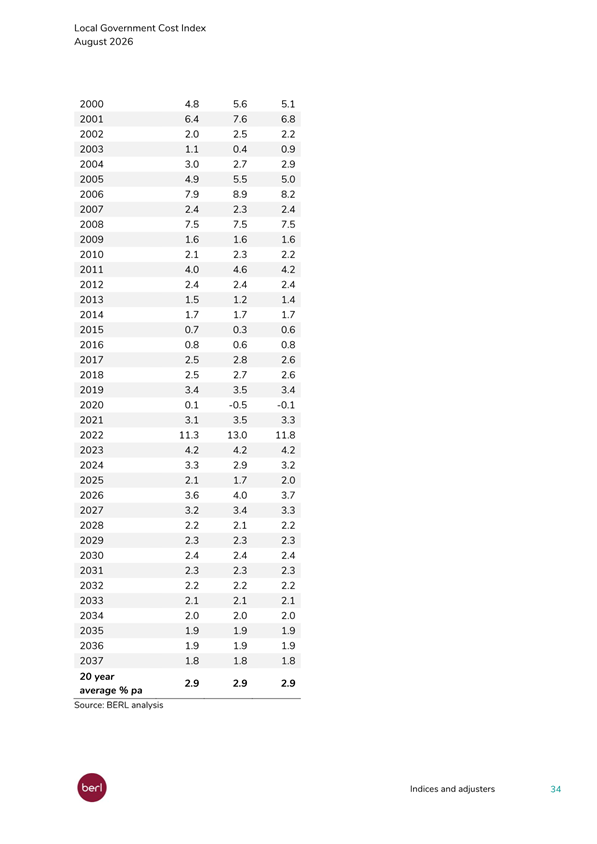
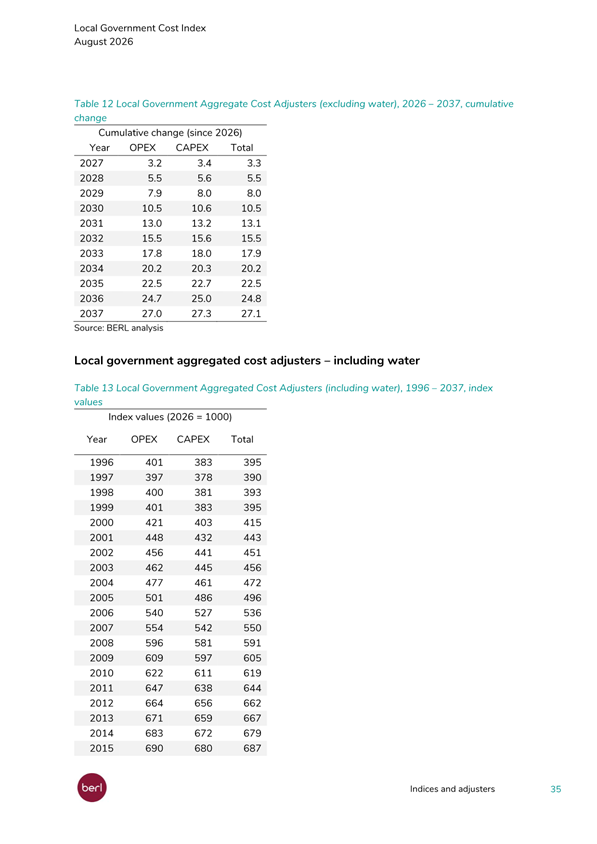
Cr Cherry Lucas
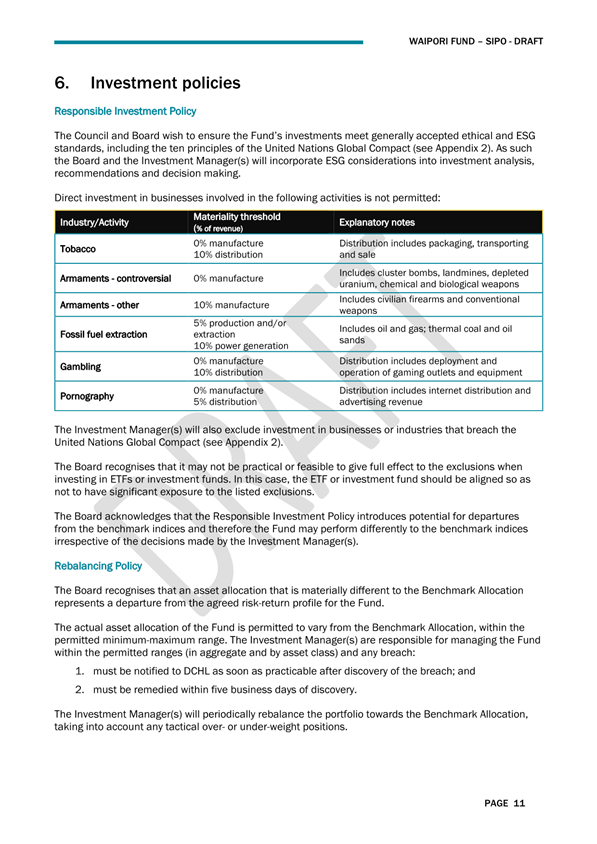
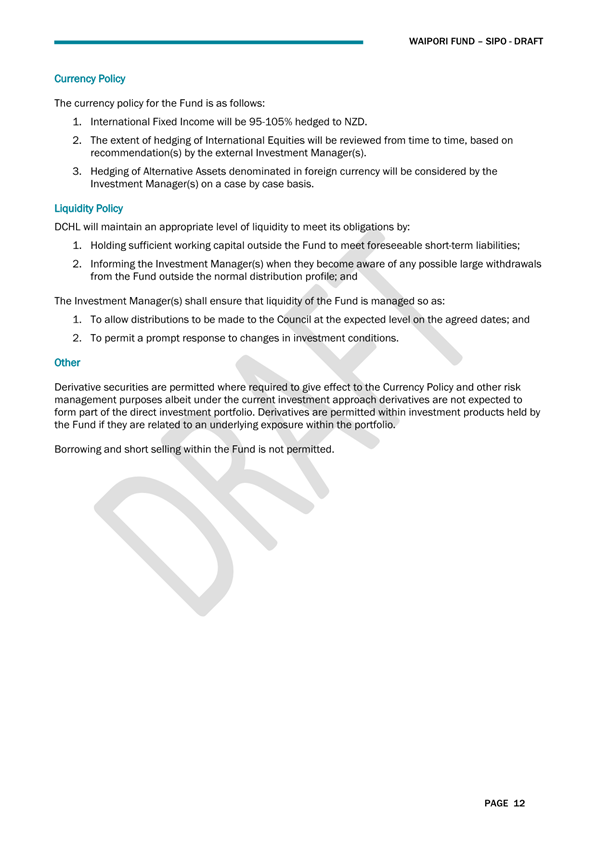
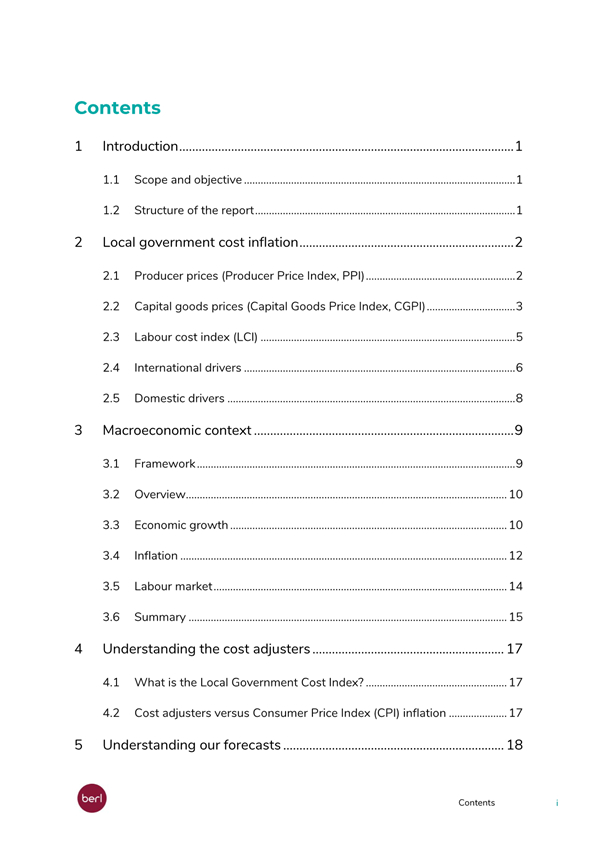
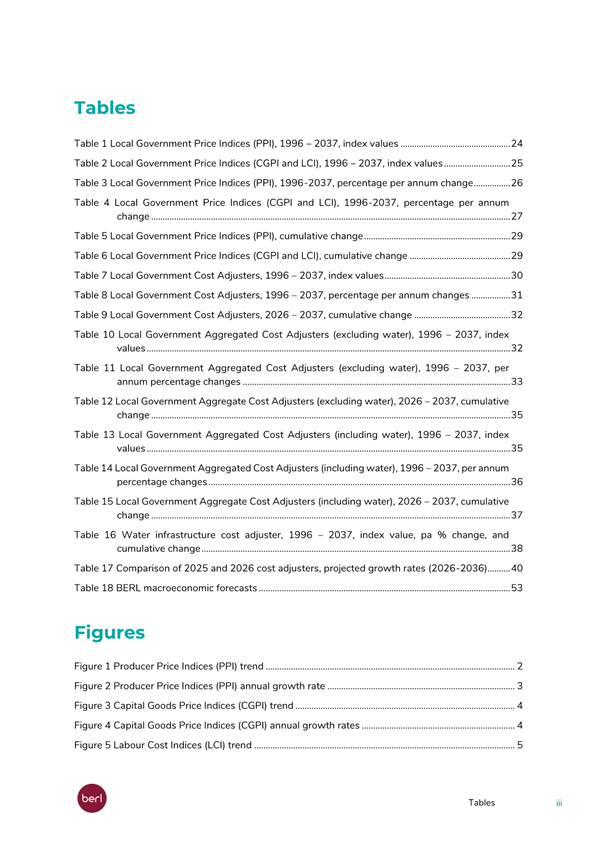
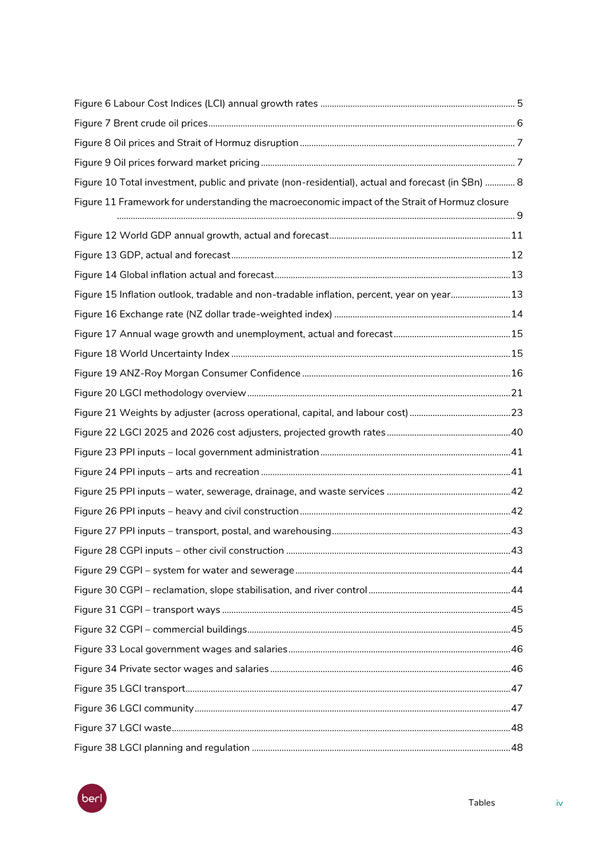
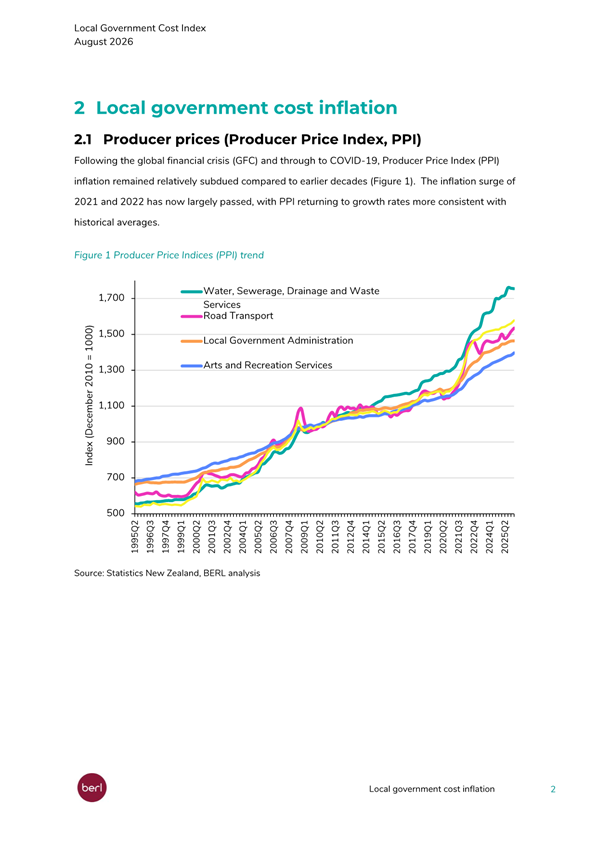
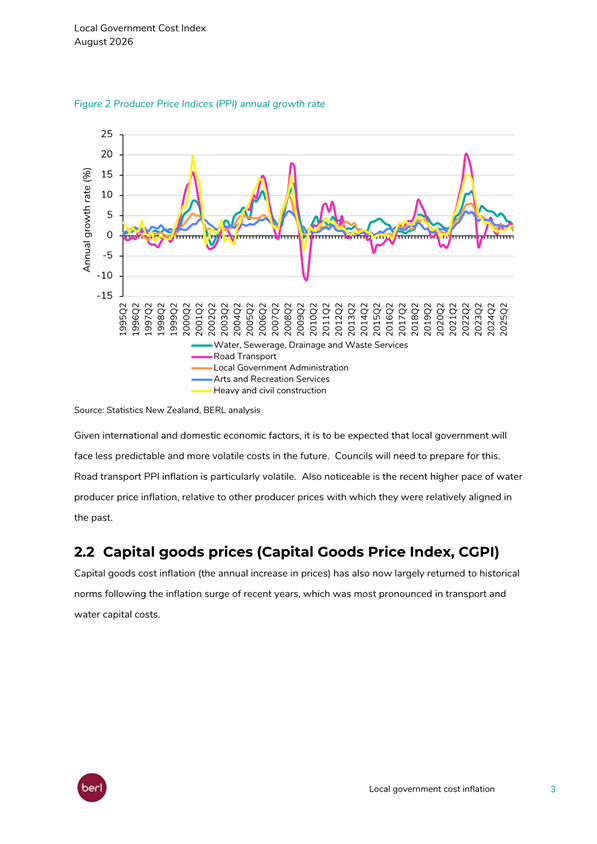
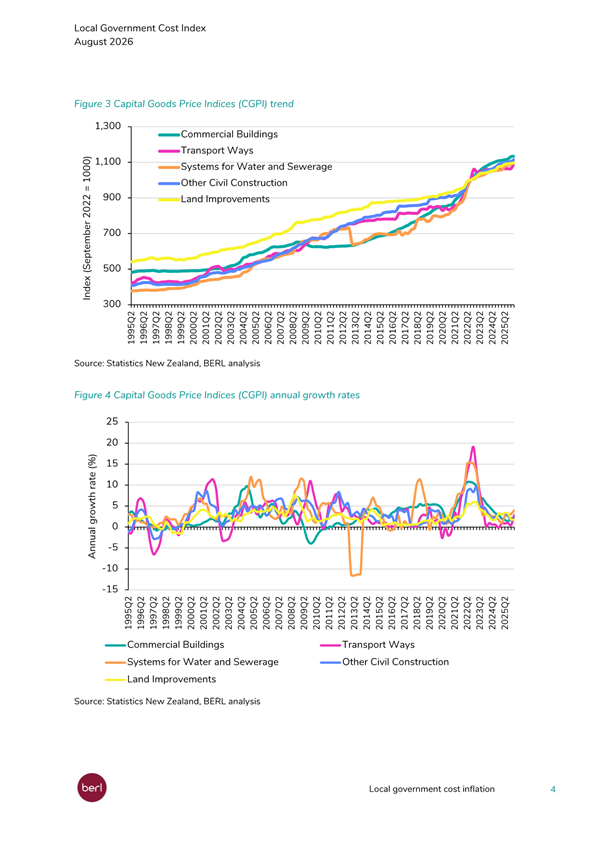
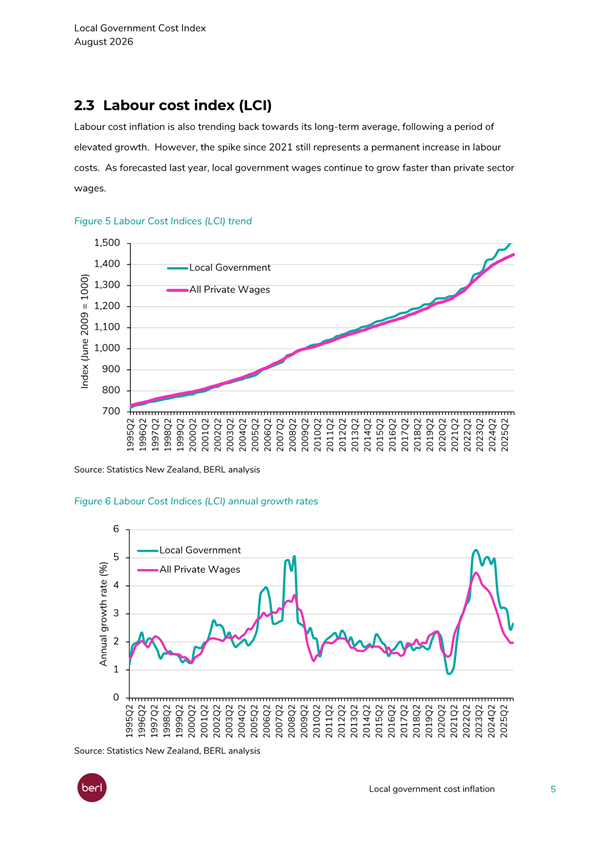
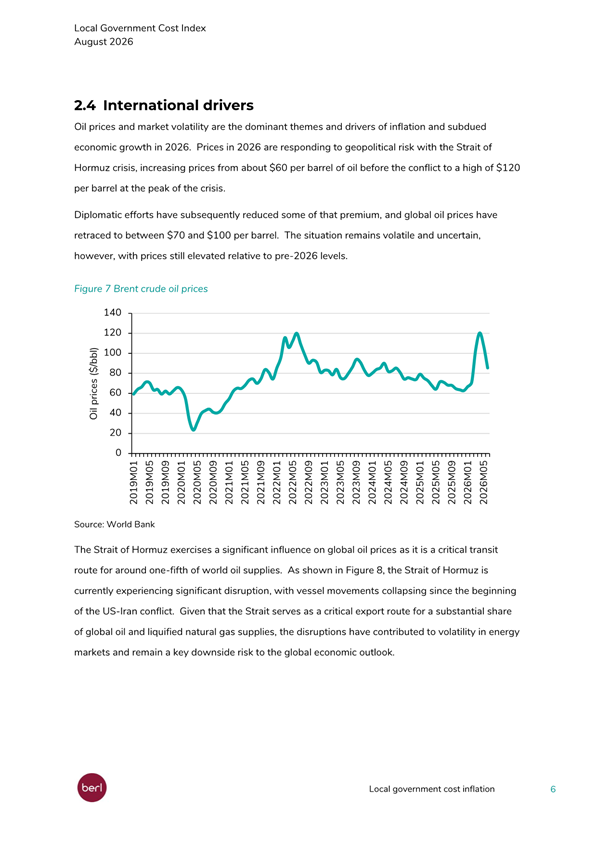
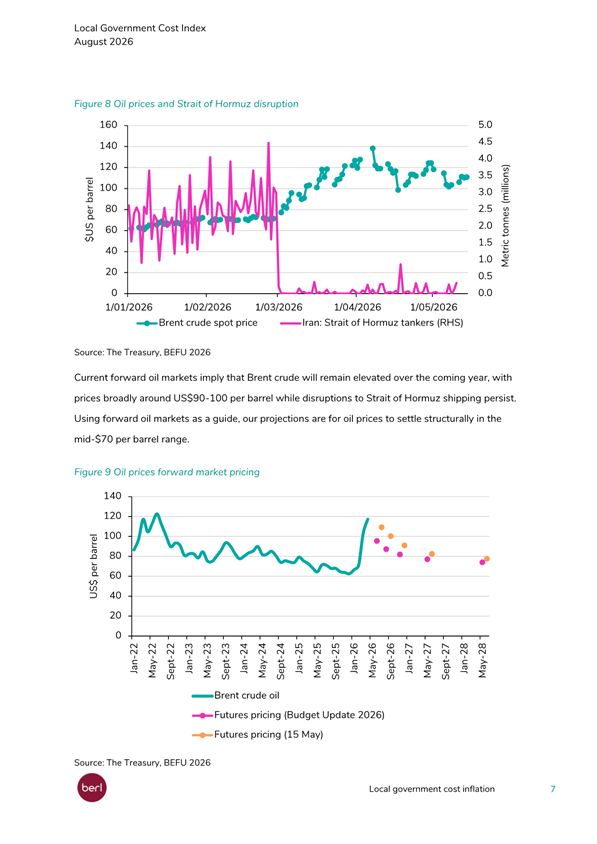
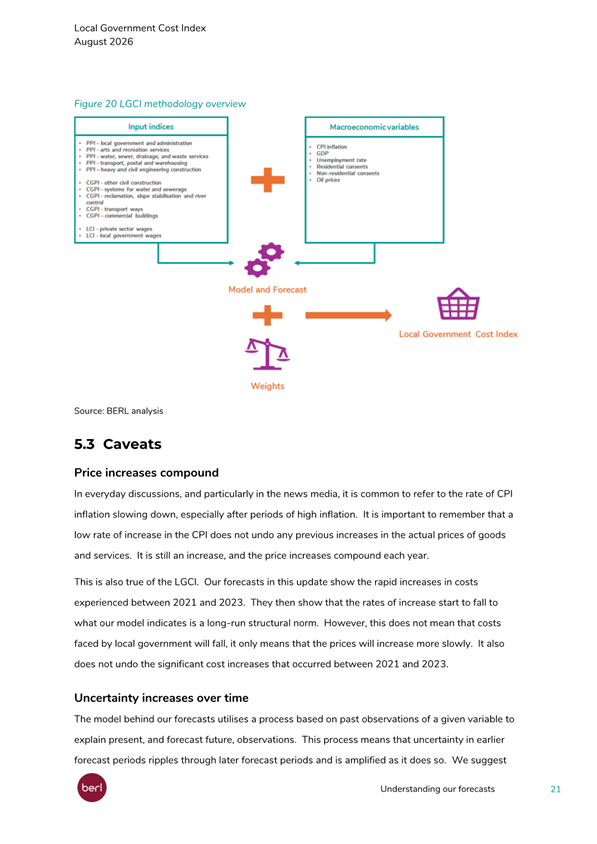
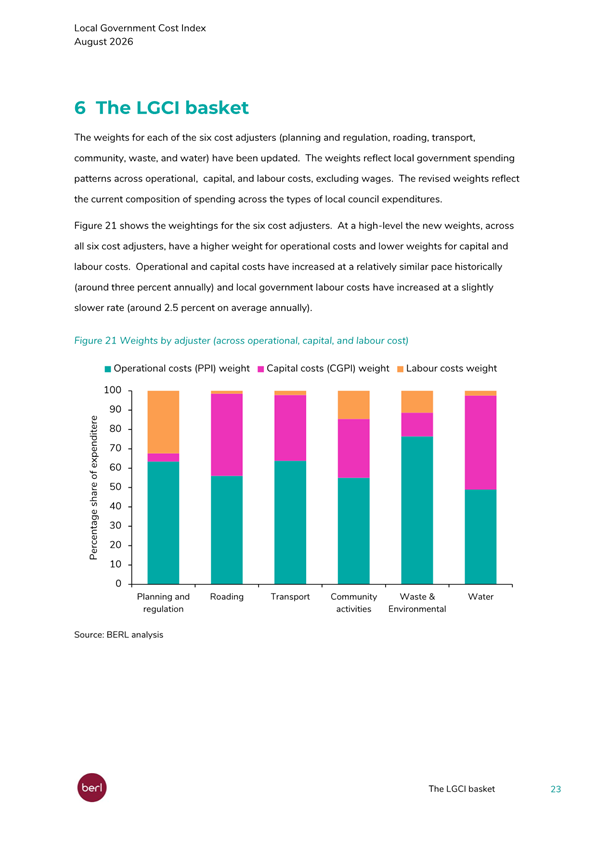
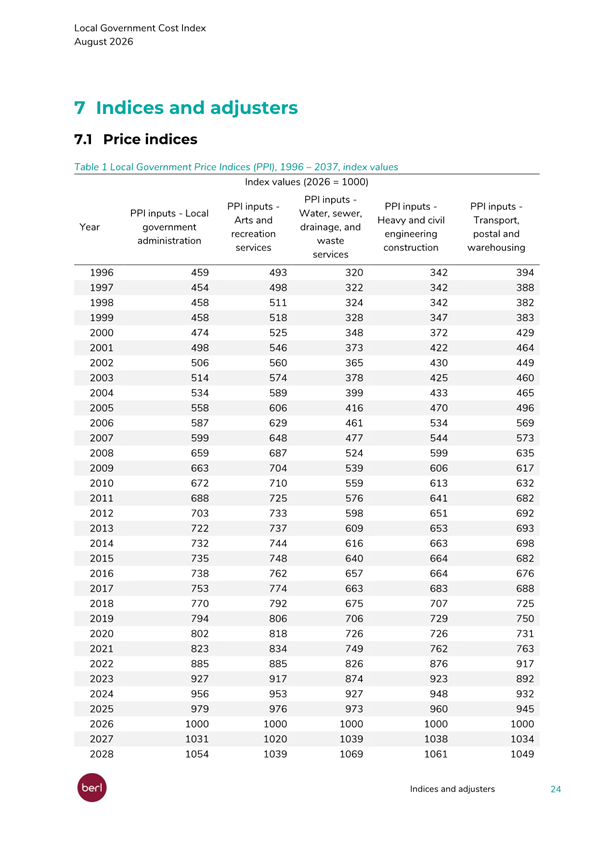
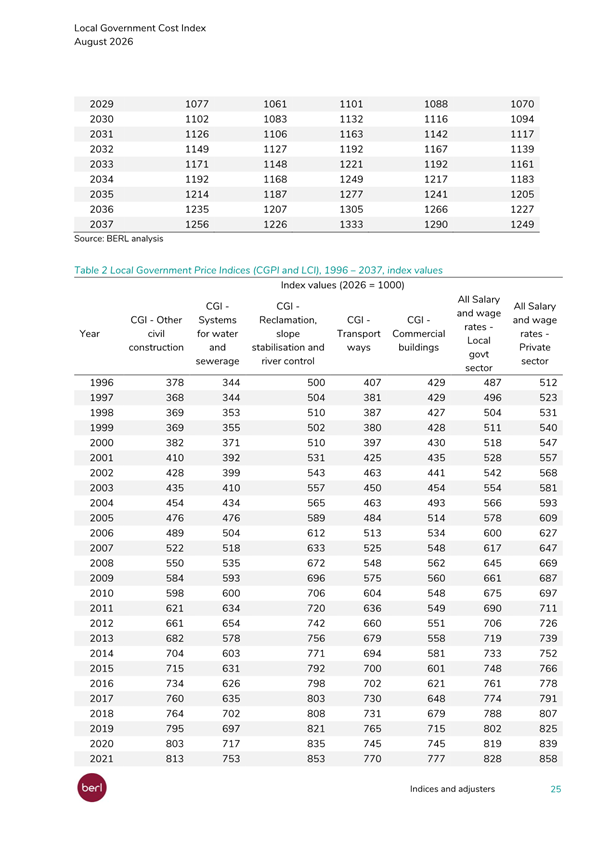
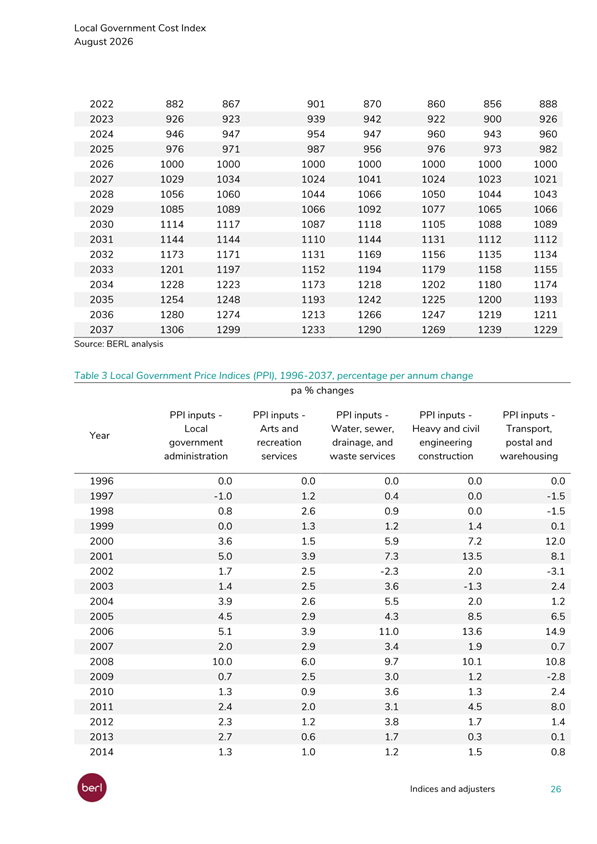
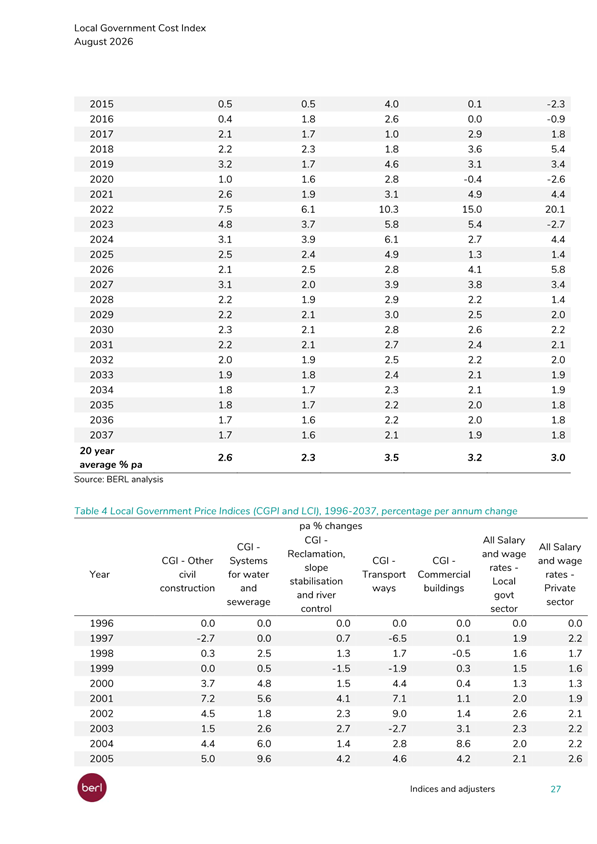
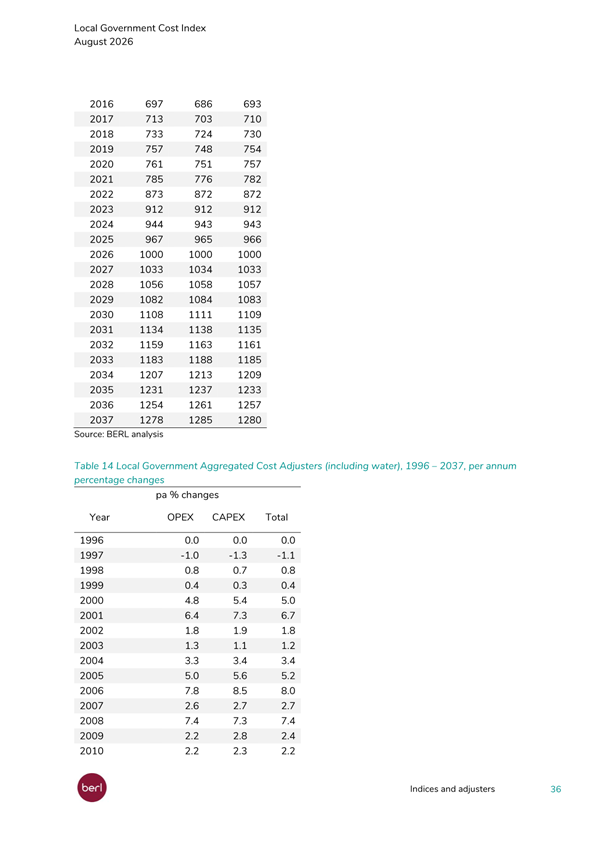
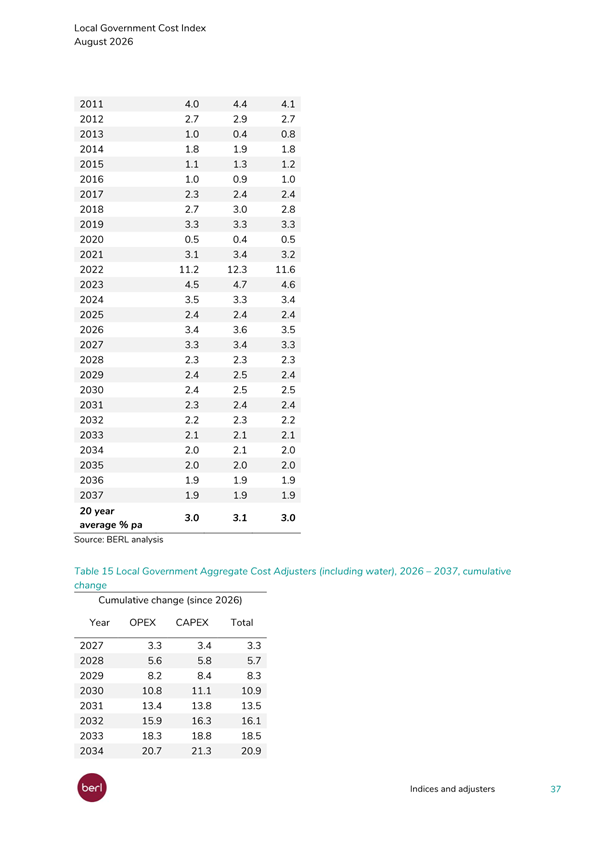
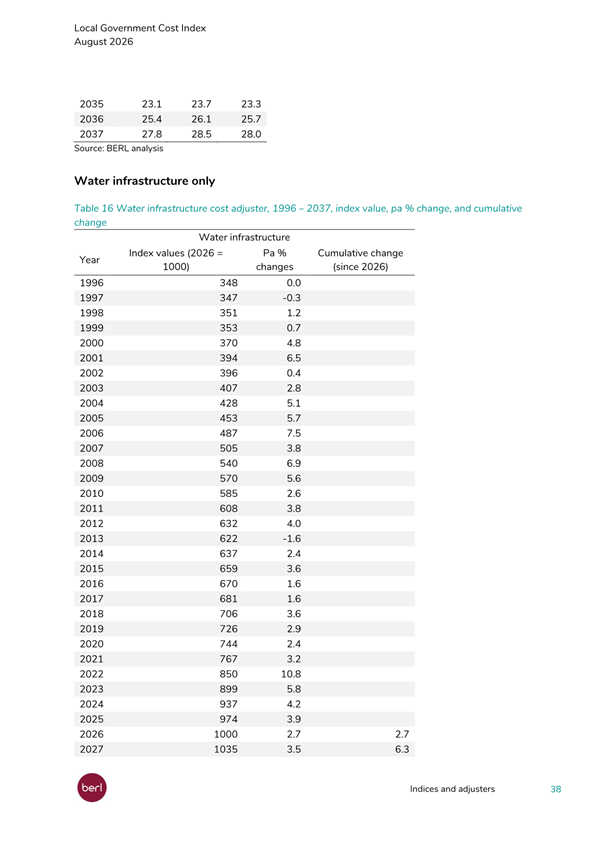
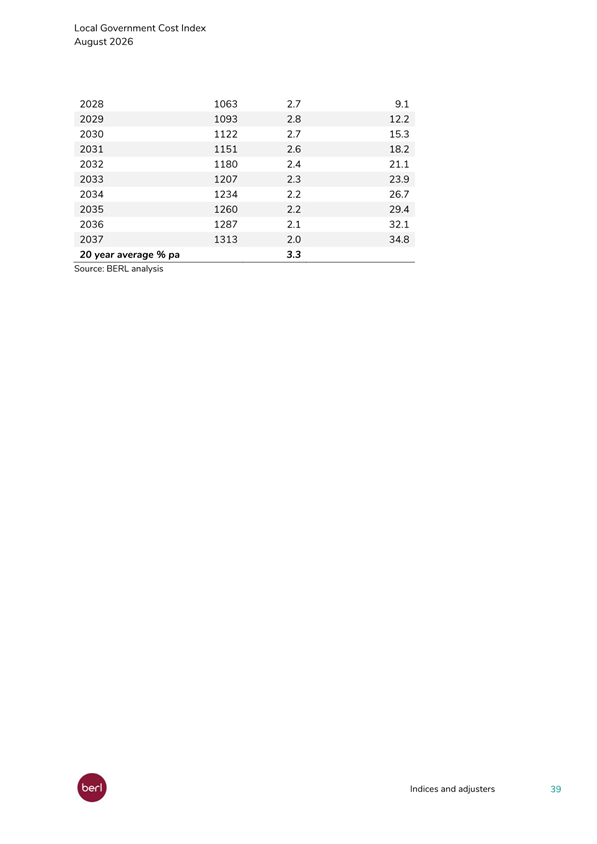
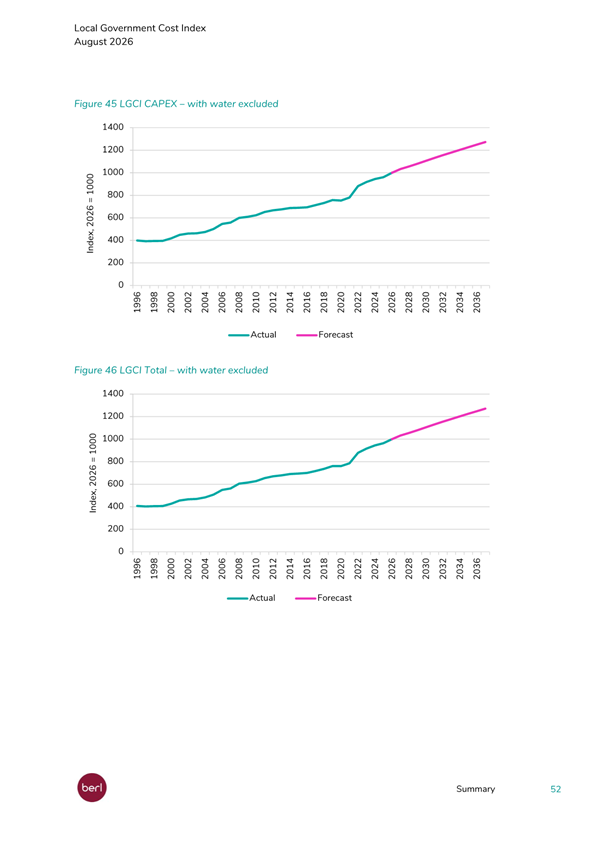
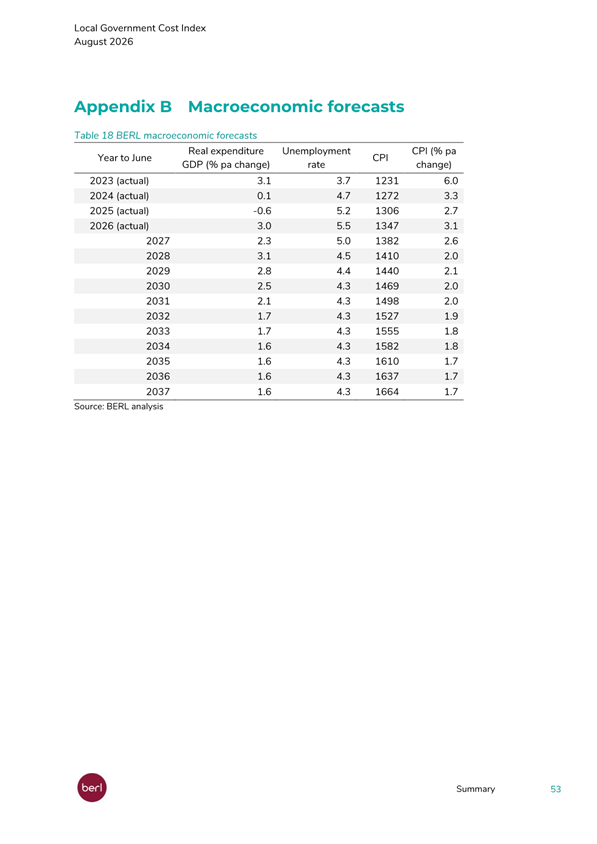
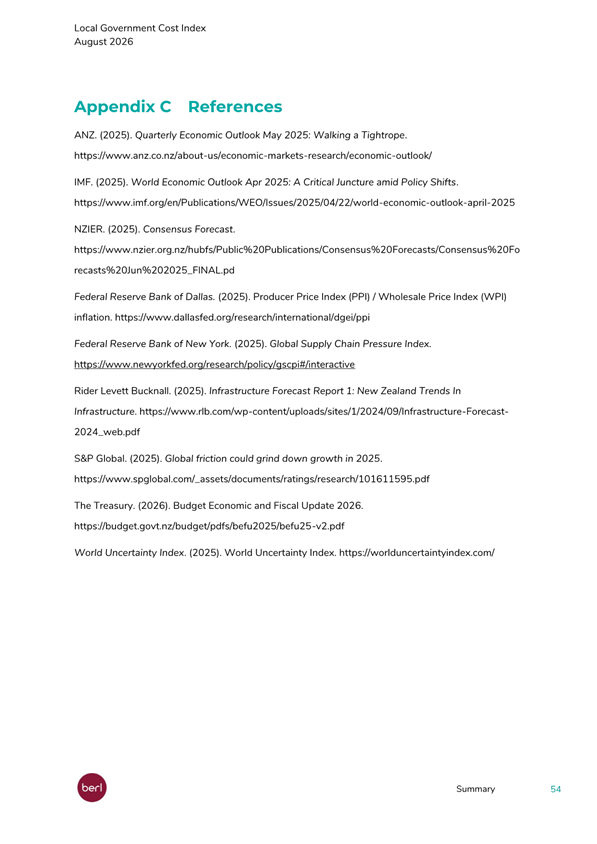
|
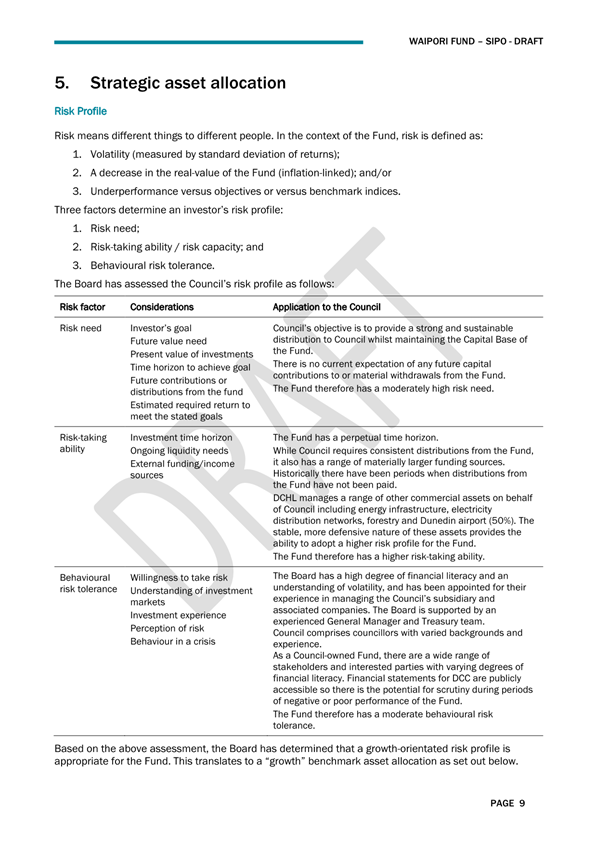
|
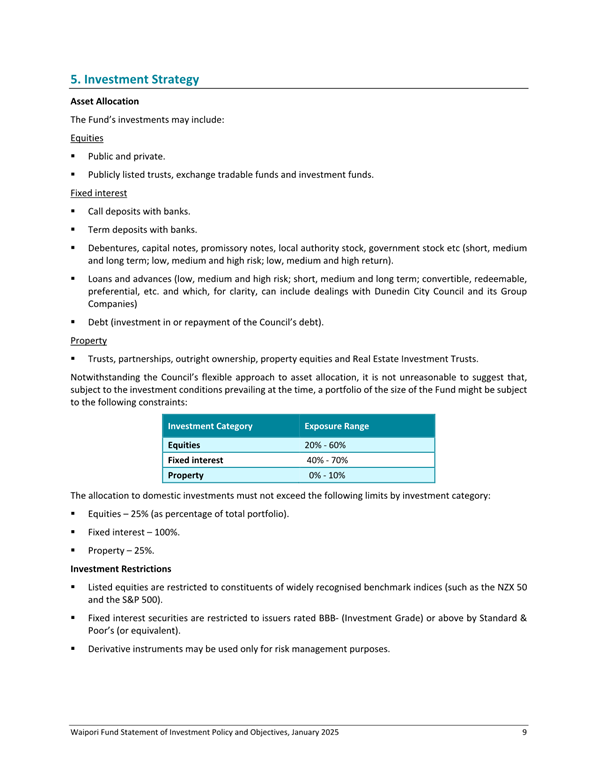
|
|
|
|
Members
|
Mayor Sophie Barker
|
Mr Jeffrey Broughton
|
|
|
Cr John Chambers
|
Cr Jo Galer
|
|
|
Cr Christine Garey
|
Cr Doug Hall
|
|
|
Mr Hoani Langsbury
|
Cr Marie Laufiso
|
|
|
Cr Russell Lund
|
Cr Mandy Mayhem
|
|
|
Cr Andrew Simms
|
Cr Mickey Treadwell
|
|
|
Cr Steve Walker
|
Cr Brent Weatherall
|
Senior Officer Carolyn
Allan, Chief Financial Officer
Governance Support Officer Lauren
Riddle
Lauren Riddle
Governance Support Officer
Telephone: 03 477 4000
governance.support@dcc.govt.nz
www.dunedin.govt.nz
Note: Reports
and recommendations contained in this agenda are not to be considered as
Council policy until adopted.
|
|
Finance and Performance
Committee
27 August 2026
|
ITEM TABLE OF CONTENTS PAGE
1 Public
Forum 4
2 Apologies 4
3 Confirmation
of Agenda 4
4 Declaration
of Interest 5
5 Confirmation
of Minutes 14
5.1 Finance and
Performance Committee meeting - 21 May 2026 15
Part
A Reports (Committee has power to decide these matters)
6 Dunedin
City Holdings Limited Group Update - Quarter Ending 30 June 2026 22
7 Investment
Framework 35
8 Waipori
Fund SIPO Review 51
9 Waipori
Fund - Quarter Ending 30 June 2026 138
10 Significant
Forecasting Assumptions - 10 Year Plan and Water Services Strategy 2027-37 146
11 Rating
method and financial policies review - 10 Year Plan 2027-37 234
12 Financial
Report - Period ended 30 June 2026 297
13 Items
for Consideration by the Chair 329
Resolution to Exclude the Public 330
|
|
Finance and Performance
Committee
27 August 2026
|
1 Public
Forum
At the close of the agenda no
requests for public forum had been received.
Public Forum registrations close
at 9.00am on Wednesday 26 August. Members of the public wishing to speak
to the Finance and Performance Committee please contact the Governance Support
Team at governance.support@dcc.govt.nz or alternatively phone 03 477
4000.
2 Apologies
At the close of the agenda no
apologies had been received.
3 Confirmation
of agenda
Note:
Any additions must be approved by resolution with an explanation as to why they
cannot be delayed until a future meeting.
|
|
Finance and Performance Committee
27 August 2026
|
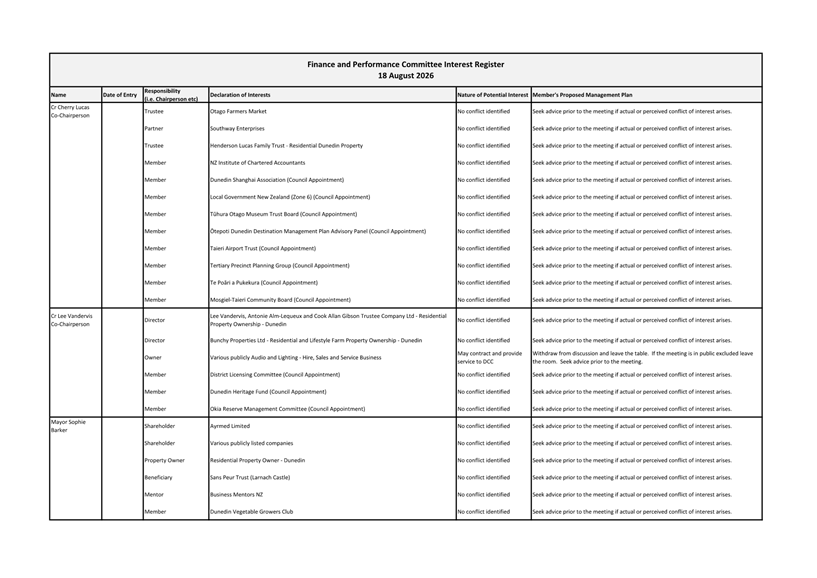
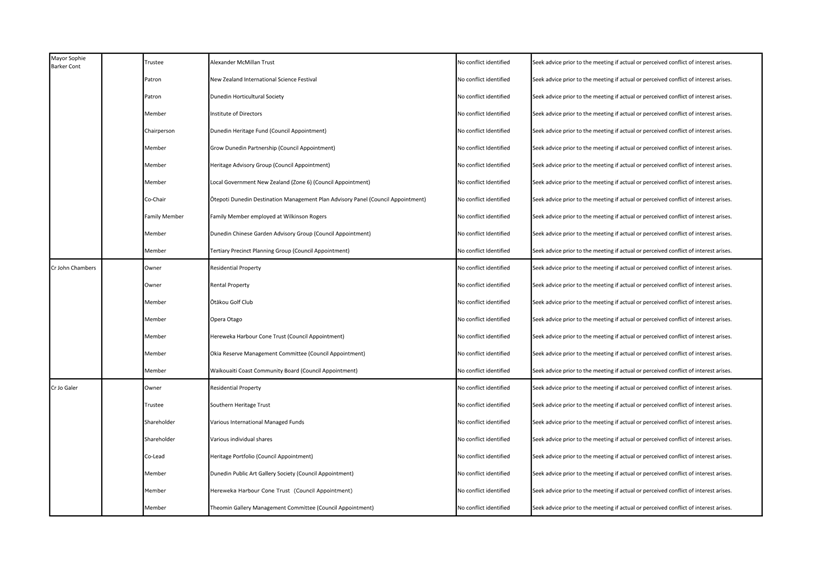
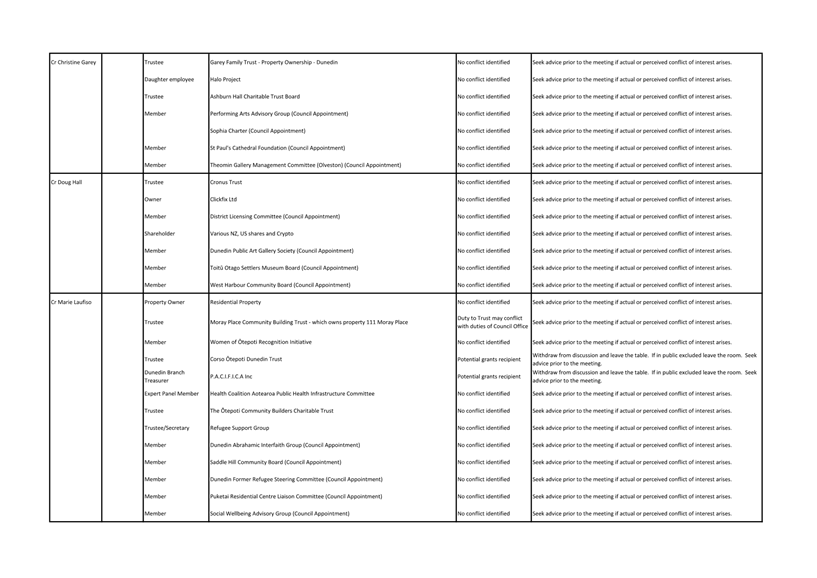
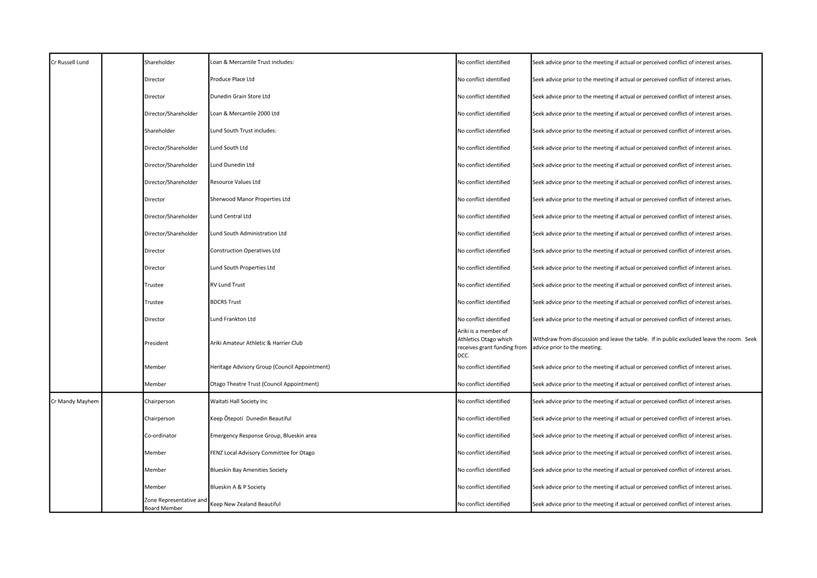
Declaration of Interest
EXECUTIVE SUMMARY
1. Members
are reminded of the need to stand aside from decision-making when a conflict
arises between their role as an elected representative and any private or other
external interest they might have.
2. Elected
members are reminded to update their register of interests as
soon as practicable, including amending the register at this meeting if
necessary.
3. Staff members are
reminded to update their register of interests as soon as practicable.
RECOMMENDATIONS
That the Committee:
a) Notes/Amends if
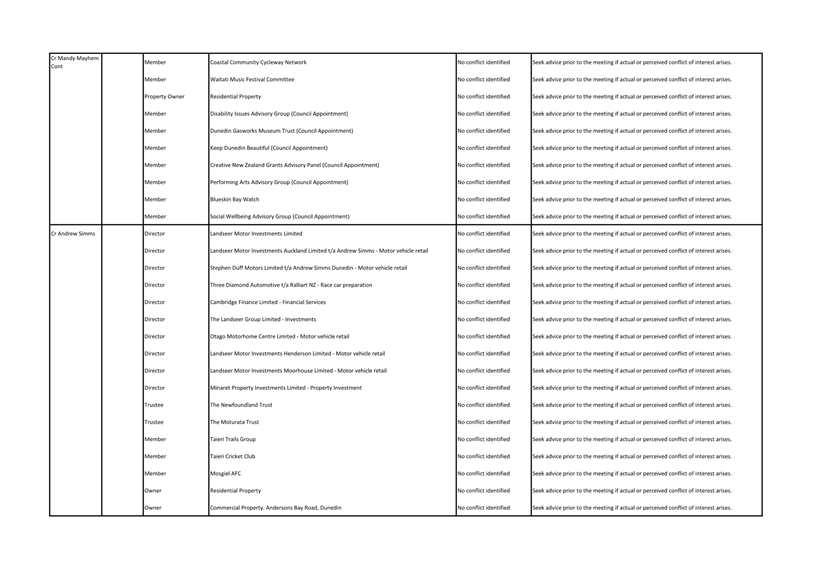
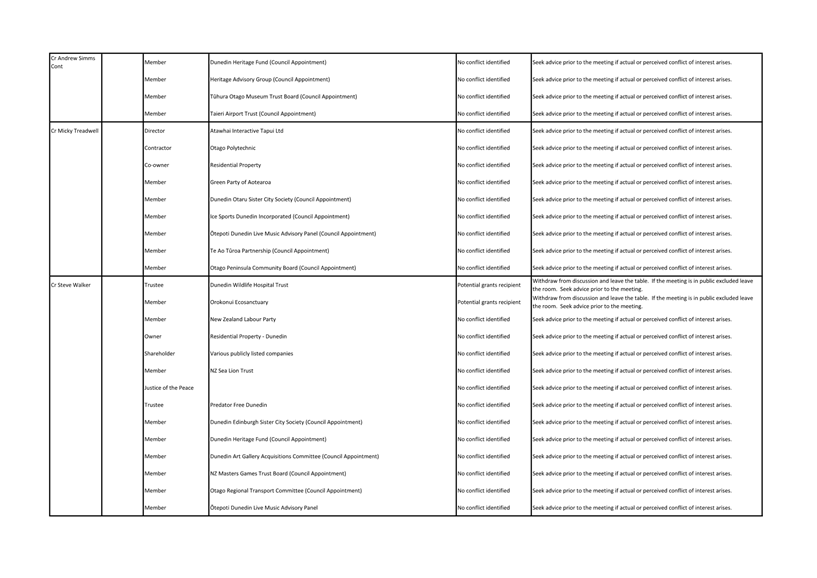
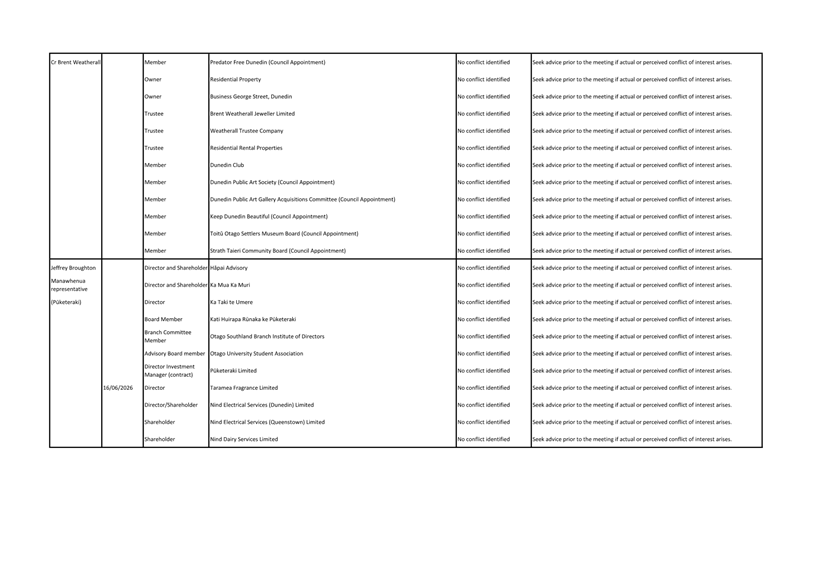
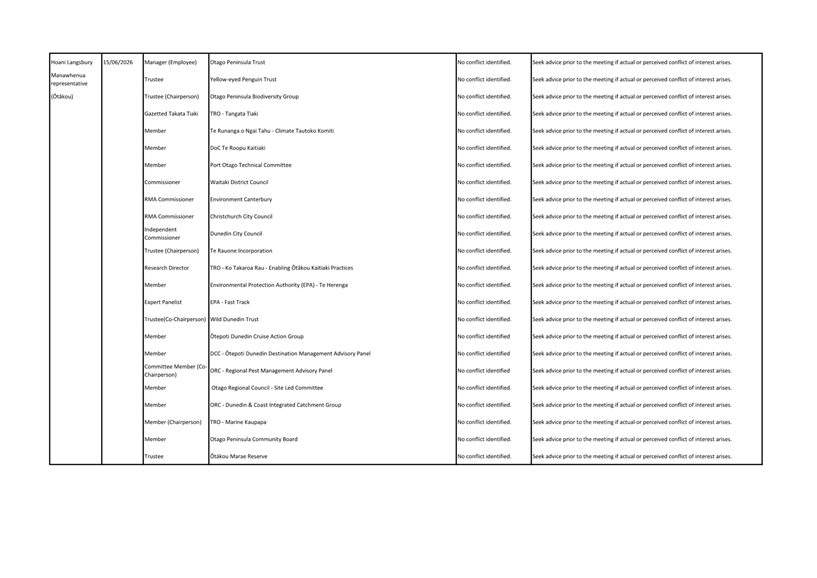
necessary the Elected Members' Interest Register attached as Attachment A; and
b) Confirms/Amends the
proposed management plan for Elected Members' Interests.
c) Notes the proposed
management plan for the Executive Leadership Team’s Interests.
Attachments
|
|
Title
|
Page
|
|
⇩a
|
Register of Interests -
August 2026
|
6
|
|
|
Finance and Performance Committee
27 August 2026
|
|
|
Finance and Performance Committee
27 August 2026
|
Confirmation
of Minutes
Finance
and Performance Committee meeting - 21 May 2026
RECOMMENDATIONS
That the Committee:
a) Confirms the public
part of the minutes of the Finance and Performance Committee meeting held on 21
May 2026 as a correct record.
Attachments
|
|
Title
|
Page
|
|
A⇩
|
Minutes of Finance and
Performance Committee meeting held on 21 May 2026
|
15
|
|
|
Finance and
Performance Committee
27 August 2026
|
Finance and Performance Committee
MINUTES
Minutes of an ordinary
meeting of the Finance and Performance Committee held in the Council Chamber,
Level 2, Dunedin Public Art Gallery, The Octagon, Dunedin on Thursday 21 May
2026, commencing at 09:00 a.m.
PRESENT
|
Chairperson
|
Cr Cherry Lucas
|
|
|
|
Cr Lee Vandervis
|
|
|
Members
|
Mayor Sophie Barker
|
Cr John Chambers
|
|
|
Cr Russell Lund
|
Cr Doug Hall
|
|
|
Cr Jo Galer
|
Cr Mandy Mayhem
|
|
|
Cr Mickey Treadwell
|
Cr Andrew Simms
|
|
|
Cr Brent Weatherall
|
Cr Steve Walker
|
|
|
Cr Russell Lund
|
|
|
IN ATTENDANCE
|
Sandy Graham (Chief Executive),
Carolyn Allan (Chief Financial Officer), Scott MacLean (General Manager City
Services), Nicola Morand (Manahautū - General Manager Community and
Strategy), Mike Costelloe (General Manager, Arts, Culture and Economic
Development), David Ward (General Manager 3 Waters, Property and Urban
Development), Tim Loan (Chairperson, DCHL Group Ltd), Peter Hocking (General
Manager DCHL), Richard Davey (Dunedin City Treasurer), Hayden McAuliffe
(Financial Services Manager), Tony Nelmes (Project Accountant), Anna Nilsen
(Group Manager Property)
|
Governance Support Officer Lauren
Riddle
Cr Cherry Lucas opened the meeting and welcomed attendees.
1 Public
Forum
There was no Public Forum.
|
2 Apologies
|
|
|
Moved (Cr Cherry Lucas/Cr Mandy Mayhem):
That the Committee:
Accepts the apologies
from Cr Christine Garey, Cr Marie Laufiso, Mr Jeffrey Broughton and Mr Hoani
Langsbury for absence.
Motion
carried (FAPCC/2026/002)
|
|
3 Confirmation
of agenda
|
|
|
A request was made for Item 9 - DCHL Group Update for the
quarter ending 31 March 2026 to be taken ahead of Item 6 – Overview of
Dunedin City Treasury Limited.
|
|
|
Moved (Cr Cherry Lucas/Cr Lee Vandervis):
That the Committee:
Confirms the agenda with
the following alteration that Item 9 - DCHL Group Update for the quarter
ending 31 March 2026 be taken ahead of Item 6 – Overview of Dunedin
City Treasury Limited.
Motion carried
|
4 Declarations
of interest
Members were
reminded of the need to stand aside from decision-making when a conflict arose
between their role as an elected representative and any private or other
external interest they might have.
· Cr Mandy Mayhem
requested her removal from FENZ Local Advisory Committee for Otago, as her 5
year appointment has been completed.
· Cr Jo Galer was
requested to provide her register of interests ahead of the next Council
meeting.
|
|
Moved (Cr Cherry Lucas/Cr Lee Vandervis):
That the Committee:
a) Amends the Elected Members' Interest Register, and
b) Amends the proposed management plan for Elected Members'
Interests.
c) Notes the proposed management plan for the Executive
Leadership Team’s Interests.
Motion
carried
|
5 Confirmation
of Minutes
|
5.1 Finance
and Performance Committee meeting - 19 March 2026
|
|
|
Moved (Cr Cherry Lucas/Cr Lee Vandervis):
That the Committee:
a) Confirms the public part of the minutes of the
Finance and Performance Committee meeting held on 19 March 2026 as a correct
record.
Motion
carried (FAPCC/2026/003)
|
Part
A Reports
|
9 Dunedin
City Holdings Limited Group Update - Quarter Ending 31 March 2026
|
|
|
The report provided a
quarterly update for the period ended 31 March 2026 for the Dunedin City
Holdings Limited (DCHL) Group.
|
|
|
Tim Loan (Chairperson, DCHL Group) and Peter Hocking
(General Manager DCHL) spoke to the report and responded to questions.
|
|
|
Moved (Cr Cherry Lucas/Cr Mandy
Mayhem):
That the Committee:
a) Notes the Dunedin City Holdings Limited Group Quarterly
Update for the period ended 31 March 2026.
Motion
carried (FAPCC/2026/004)
|
|
6 Overview
of Dunedin City Treasury Limited and Treasury Risk Management Policy
|
|
|
Richard Davey, Treasurer,
Dunedin City Treasury Limited spoke to a presentation on Dunedin City
Treasury Limited including the Treasury Risk Management Policy and responded
to questions.
|
|
Cr Doug Hall left the meeting at 09:49 a.m. and returned
to the meeting at 09:52 a.m.
|
|
|
Moved (Cr Cherry Lucas/Cr Lee
Vandervis):
That the Committee:
a) Notes the Overview of Dunedin City Treasury Limited and the
Treasury Risk Management Policy.
Motion
carried (FAPCC/2026/005)
|
|
7 Local
Government Funding Agency Covenant
|
|
|
The report sought Committee approval to
request the Local Government Funding Agency (LGFA) remove one of the four
Covenants as per the Dunedin City Treasury Limited (DCTL) outline of the rationale
and approach.
|
|
|
Carolyn Allan (Chief Financial Officer) and Richard Davey
(Treasurer, Dunedin City Treasury Ltd) spoke to the report and responded to
questions.
|
|
Cr Jo Galer left the
meeting at 10:18 a.m. and returned at 10:20 a.m.
|
|
|
Moved (Cr Cherry Lucas/Cr Brent
Weatherall):
That the Committee:
a) Notes the Local Government Funding Agency Covenant report.
b) Approves the approach outlined in the report,
that DCTL/DCC write to LGFA requesting that they consider extinguishing the
Net Interest/Annual Rates Income Covenant.
The Committee voted by
division
For: Crs
Mayor Sophie Barker, John Chambers, Doug Hall, Mandy Mayhem, Mickey
Treadwell, Steve Walker, Brent Weatherall and Cherry Lucas (8).
Against: Crs
Jo Galer, Russell Lund, Andrew Simms and Lee Vandervis (4).
Abstained: Nil
The division was declared CARRIED by 8 votes to 4
Motion
carried (FAPCC/2026/006)
|
|
8 Waipori
Fund - Quarter Ending 31 March 2026
|
|
|
The Dunedin City Treasury
Limited report provided information on the results of the Waipori Fund for
the quarter ended 31 March 2026.
|
|
|
Carolyn Allan (Chief Financial Officer) and Richard Davey
(Treasurer, Dunedin Treasury Ltd) spoke to the report and responded to
questions.
|
|
|
Moved (Cr Steve Walker/Cr Cherry
Lucas):
That the Committee:
a) Notes the report from Dunedin City Treasury Limited on the
Waipori Fund for the quarter ended 31 March 2026.
Motion
carried (FAPCC/2026/007)
|
|
|
Moved (Cr Cherry Lucas/Cr Steve Walker):
That the Committee:
Adjourn
the meeting for 15 minutes.
Motion
carried (FAPCC/2026/008)
|
|
|
The meeting adjourned at 10:46 a.m. and resumed at 11:00am
|
|
10 Financial
Strategy Compliance
|
|
|
The report provided a summary
of rate and debt limits, including group debt limits and the monitoring of
compliance against these limits.
|
|
|
Carolyn Allan (Chief Financial Officer) and Tony Nelmes
(Project Accountant) spoke to the report and responded to questions,
|
|
|
Moved (Cr Cherry Lucas/Cr Lee
Vandervis):
That the Committee:
a) Notes the Financial Strategy Compliance report.
Motion
carried (FAPCC/2026/009)
|
|
11 Debt
Repayment Policy Update
|
|
|
The report provided an update on the
development of a Debt Repayment Policy (Policy).
|
|
|
Sandy Graham (Chief Executive), Carolyn Allan (Chief
Financial Officer), Tony Nelmes (Project Accountant), and Hayden McAuliffe
(Financial Services Manager) spoke to the report and responded to questions.
Carolyn Allan (Chief Financial Officer) advised that the
report was a first draft of a Debt Repayment Policy and that councillor
workshops would be held as the policy developed.
|
|
|
Moved (Cr Cherry Lucas/Cr Brent
Weatherall):
That the Committee:
a) Notes the draft Debt Repayment Policy.
Motion
carried (FAPCC/2026/010)
|
|
12 Financial
Report - Period ended 31 March 2026
|
|
|
The report provided the financial results for the period ended 31
March 2026 and the financial position as at that date.
|
|
|
Carolyn Allan Chief Financial Officer) and Hayden
McAuliffe (Financial Services Manager) spoke to the report and responded to
questions.
|
|
|
Moved (Cr Cherry Lucas/Cr Lee
Vandervis):
That the Committee:
a) Notes the Financial Performance for the period ended 31
March 2026 and the Financial Position as at that date.
.Motion
carried (FAPCC/2026/011)
|
|
13 Items
for Consideration by the Chair
|
|
|
There we no items of consideration by the Chair.
|
|
Resolution to Exclude the Public
|
|
Moved (Cr Cherry Lucas/Cr Mandy Mayhem):
That the Committee:
Pursuant
to the provisions of the Local Government Official Information and Meetings
Act 1987, exclude the public from the following part of the proceedings of
this meeting namely:
|
General
subject of the matter to be considered
C1 Investment
Property Portfolio – Quarter ending 31 March 2026
|
Reasons for
passing this resolution in relation to each matter
S7(2)(b)(ii)- The
withholding of the information is necessary to protect information where
the making available of the information would be likely unreasonably to
prejudice the commercial position of the person who supplied or who is the
subject of the information.
|
Ground(s) under
section 48(1) for the passing of this resolution
|
Reason for
Confidentiality
|
This resolution is made in
reliance on Section 48(1)(a) of the Local Government Official Information and
Meetings Act 1987, and the particular interest or interests protected by
Section 6 or Section 7 of that Act, or Section 6 or Section 7 or Section 9 of
the Official Information Act 1982, as the case may require, which would be
prejudiced by the holding of the whole or the relevant part of the
proceedings of the meeting in public are as shown above after each item, and;
Adjourn
the meeting for five minutes.
Motion
carried (FAPCC/2026/012)
|
The meeting adjourned at
12:03pm and moved into Public Excluded and 12:08 p.m.
..............................................
CHAIRPERSON
|
|
Finance and Performance Committee
27 August 2026
|
Part
A Reports
Dunedin City Holdings Limited Group Update - Quarter Ending
30 June 2026
Department: Finance
EXECUTIVE SUMMARY
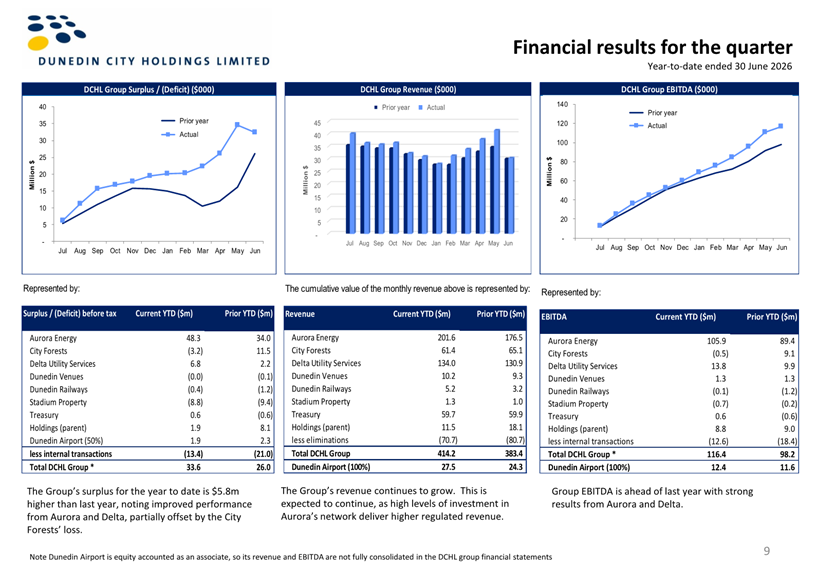
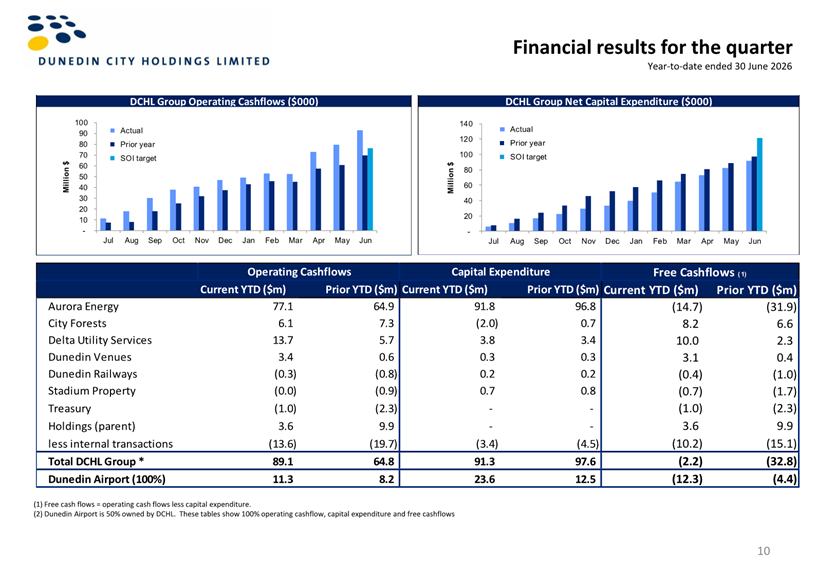
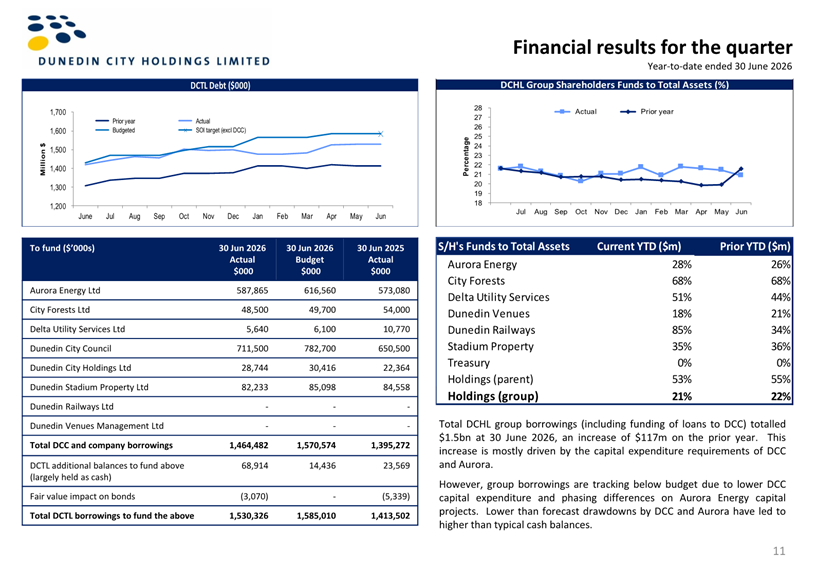
1 This
report provides a quarterly update for the period ended 30 June 2026 for the
Dunedin City Holdings Limited (DCHL) Group.
2 As
this is an administrative report only, there are no Summary of Considerations.
|
RECOMMENDATIONS
That the Committee:
a) Notes the Dunedin
City Holdings Limited Group Quarterly Update for the period ended 30 June
2026.
|
DISCUSSION
3 The
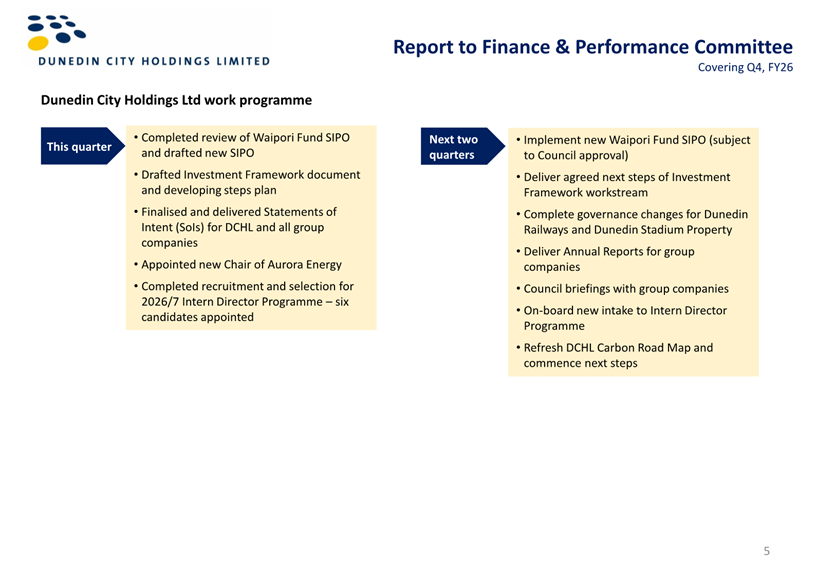
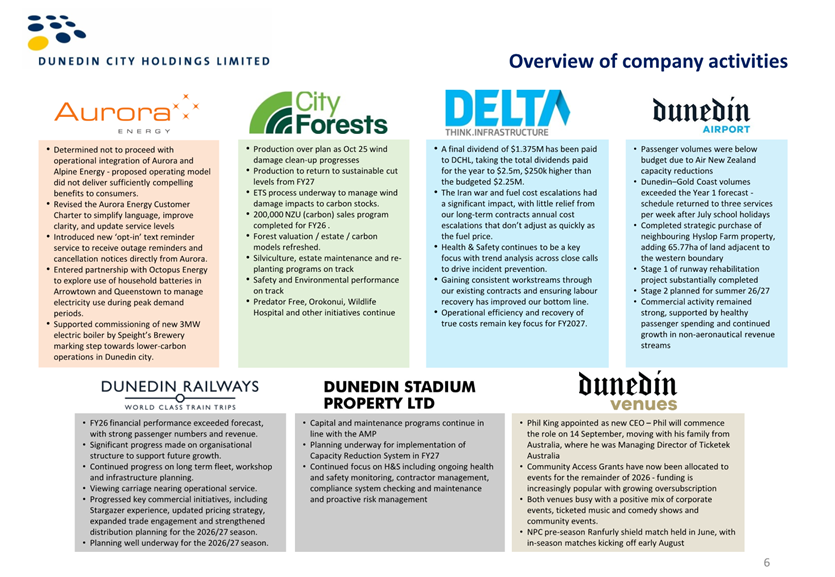
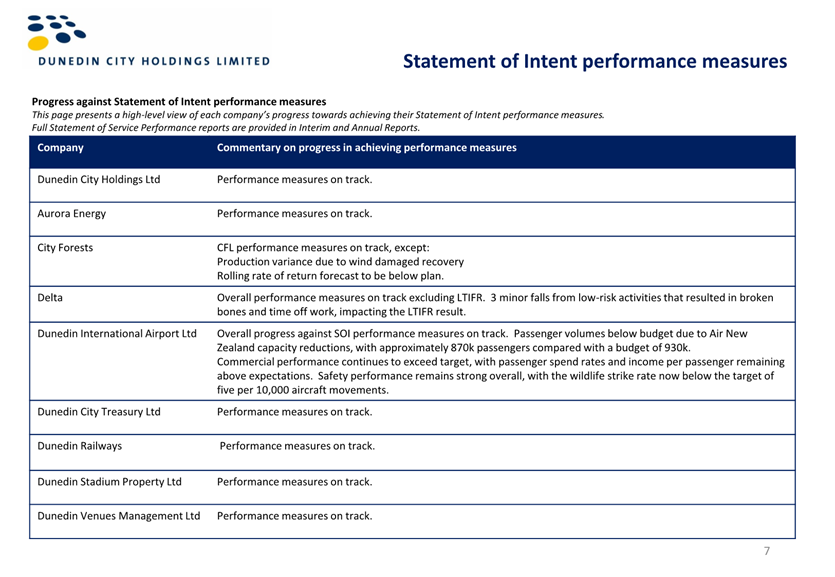
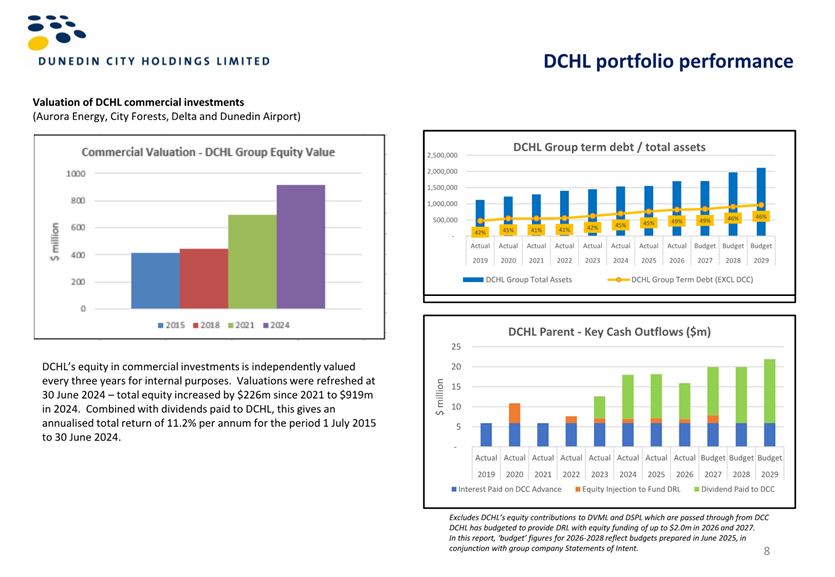
attached DCHL quarterly report for the period ended 30 June 2026 provides an
update for Councillors on the following:
· Year
to date financial results
· Areas
of focus/activity for each company this quarter
· Progress
towards achieving Statement of Intent measures
· Financial
performance of the group
· Group
funding
OPTIONS
4 As
this is a noting report, no options are provided.
NEXT STEPS
5 A
quarterly update for the period ended 30 September 2026 for the Dunedin City
Holdings Limited (DCHL) Group will be presented at a future Finance and
Performance Committee meeting.
Signatories
|
Authoriser:
|
Carolyn Allan - Chief Financial Officer
|
Attachments
|
|
Title
|
Page
|
|
⇩a
|
DCHL Quarterly Report
to 30 June 2026
|
24
|
|
|
Finance and Performance Committee
27 August 2026
|
|
|
Finance and Performance Committee
27 August 2026
|
Investment Framework
Department: Finance
EXECUTIVE SUMMARY
1 The
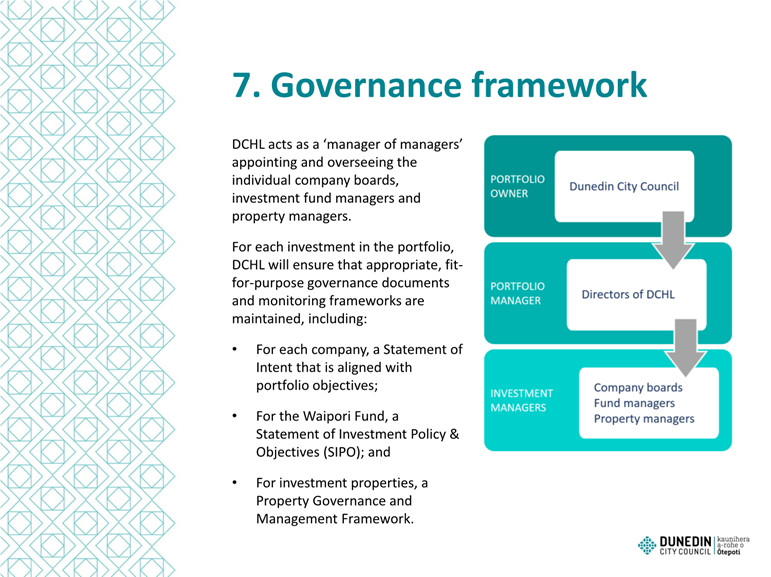
purpose of this report is to consider a draft Investment Framework prepared by
Dunedin City Holdings Limited (DCHL).
2 The
Investment Framework sets out how the Council defines, governs and manages its investment
portfolio, and what it expects those investments to deliver over time.
RECOMMENDATIONS
That the Committee:
a) Notes the Investment
Framework report.
b) Considers the
Investment Framework for endorsement.
BACKGROUND
3 In
the December 2024 Letter of Expectation to DCHL, Council requested that DCHL
undertake a review of the draft Investment Plan. The DCHL Board was asked to
present options to the DCC on how its investments, including the DCHL trading
companies, the Waipori Fund and the Council’s investment property
portfolio are managed and reported on.
4 In
its December 2025 Letter of Expectation to DCHL, Council requested that DCHL
and Council continue to work on the Investment Framework.
5 The
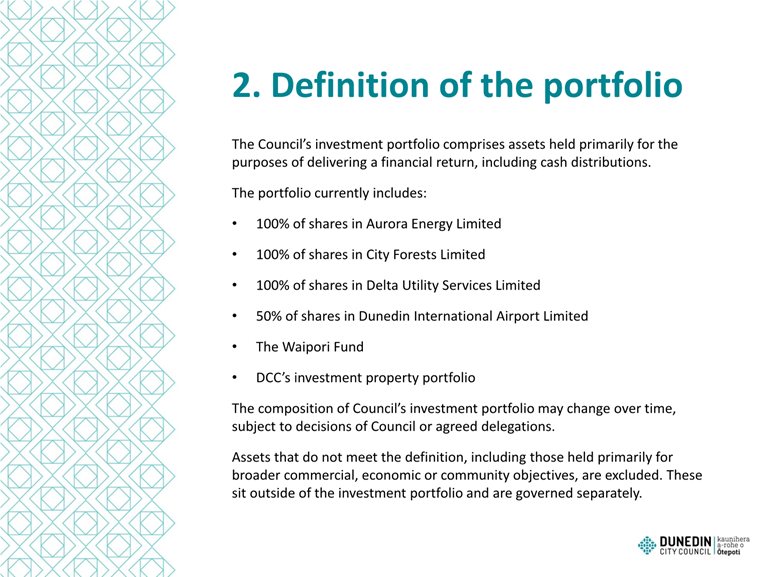
current investment structure comprises:
· The
Waipori Fund which is owned directly by Council, with management and reporting
of the Fund undertaken by Dunedin City Treasury Limited.
· The
investment property portfolio which is owned directly by Council and is part of
Council’s total property portfolio.
· DCHL
is wholly owned by Council. DCHL owns, on behalf of Council, the following
companies:
i) Aurora
Energy Limited
ii) City
Forests Limited
iii) Delta
Utility Services Limited
iv) Dunedin Stadium
Property Limited
v) Dunedin
Venues Management Limited
vi) Dunedin Airport
Limited (50%)
vii) Dunedin Railways
Limited
6 DCHL
provided a confidential report on the Investment Framework to a Council meeting
on 25 March 2026. The report sought Council endorsement of the revised
Investment Framework and recommended further engagement.
7 Council
noted that an Investment Framework will be presented to a future Council
meeting where endorsement of the framework will be sought.
DISCUSSION
8 The
draft Investment Framework is provided at Attachment A.
OPTIONS
Option One – Recommended Option
9 That
Council endorses the Investment Framework as presented.
Advantages
· It
provides a framework for how Council defines, governs and manages its
investment portfolio.
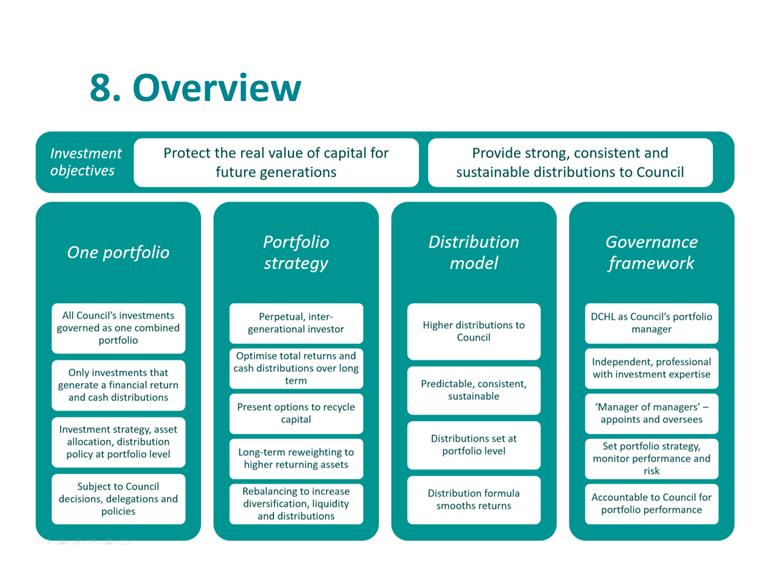
· The
investment framework provides a one portfolio approach for the management and
strategic oversight of Council’s investments.
· Provides
a consistent view of risk and diversification.
· Provides
clear investment objectives – to protect the real value of capital for
future generations and to provide strong, consistent and sustainable
distributions to Council.
· Optimises
total returns and cash distributions over the long term.
· Establishes
a distribution model which should result in a higher, predictable, consistent
and sustainable dividends.
Disadvantages
· No
disadvantages have been identified.
Option Two
10 Council
does not approve the Investment Framework.
Advantages
· No
advantages have been identified.
Disadvantages
· The
advantages in option one will not be realised.
NEXT STEPS
11 DCHL are
developing an implementation plan. An update will be provided to a Council
meeting in November.
Signatories
|
Authoriser:
|
Carolyn Allan - Chief Financial Officer
|
Attachments
|
|
Title
|
Page
|
|
⇩a
|
Draft Investment
Framework
|
40
|
|
SUMMARY OF CONSIDERATIONS
|
|
Fit with purpose of Local Government
This decision enables democratic local
decision making and action by, and on behalf of communities.
|
|
Fit with strategic framework
|
|
Contributes
|
Detracts
|
Not applicable
|
|
Social Wellbeing Strategy
|
☐
|
☐
|
✔
|
|
Economic Development Strategy
|
☐
|
☐
|
✔
|
|
Environment Strategy
|
☐
|
☐
|
✔
|
|
Arts and Culture Strategy
|
☐
|
☐
|
✔
|
|
3 Waters Strategy
|
☐
|
☐
|
✔
|
|
Future Development Strategy
|
☐
|
☐
|
✔
|
|
Integrated Transport Strategy
|
☐
|
☐
|
✔
|
|
Parks and Recreation Strategy
|
☐
|
☐
|
✔
|
|
Other strategic projects/policies/plans
|
✔
|
☐
|
☐
|
The Investment Framework is intended to support the
Financial Strategy and all the work of Council through the protection of its
investments, and through the future distribution of sustainable investment
returns.
|
|
Māori Impact Statement
There are no known impacts for Māori.
|
|
Sustainability
The Investment Framework considers the matter of sustainability
and financial resilience.
|
|
LTP/Annual Plan / Financial Strategy /Infrastructure
Strategy
The Investment Framework supports the Council’s
Financial Strategy.
|
|
Financial considerations
Financial considerations are discussed in the draft
Investment Framework.
|
|
Significance
This report is considered to be of low significance in
terms of the Council’s Significance and Engagement Policy.
|
|
Engagement – external
There has been engagement with Dunedin City Holdings Ltd.
|
|
Engagement - internal
There has been no internal engagement.
|
|
Risks: Legal / Health and Safety etc.
There are no identified risks.
|
|
Conflict of Interest
There are no known conflicts of interest.
|
|
Community Boards
There are no known implications for Community Boards.
|
|
|
Finance and Performance Committee
27 August 2026
|
|
|
Finance and Performance Committee
27 August 2026
|
Waipori Fund SIPO Review
Department: Finance
EXECUTIVE SUMMARY
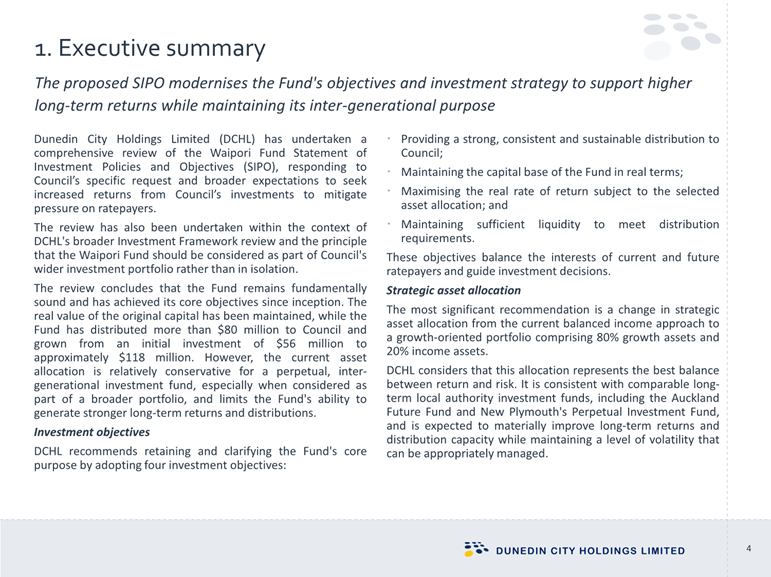
1 The
Waipori Fund (the Fund) has a Statement of Investment Policy and Objectives
(SIPO) that sets out the framework for governing the investment of the Fund.
2 Dunedin
City Holdings Ltd (DCHL) has undertaken a review of the SIPO, and a report on
the review along with a proposed revised SIPO and proposed Governance Agreement
for the Fund, is at Attachment A.
3 This
report proposes that the Committee make a decision on the proposed SIPO and
Governance Agreement.
4 The
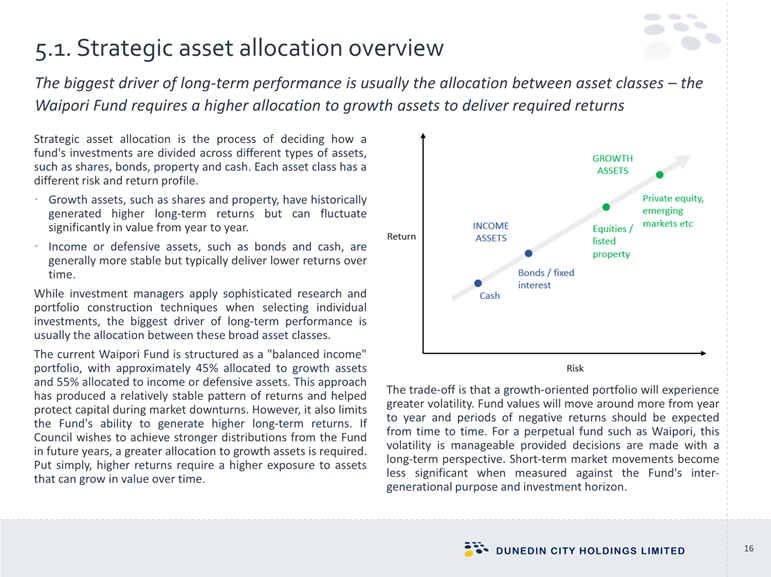
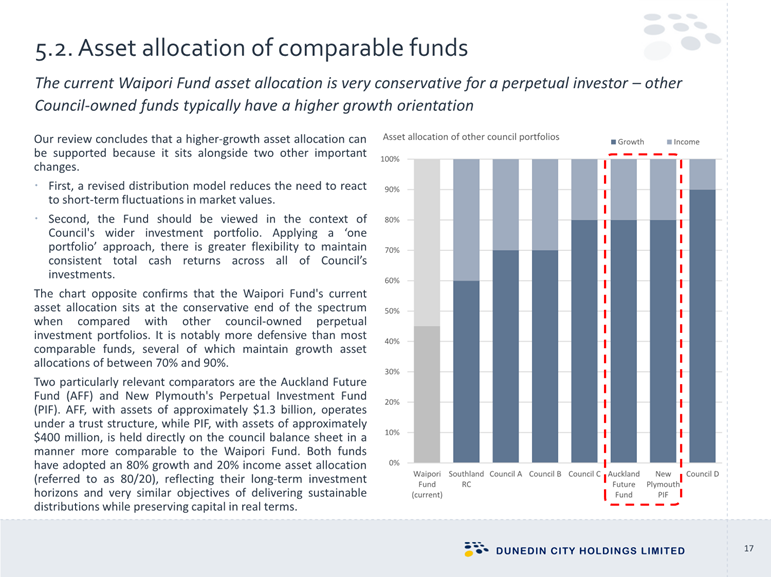
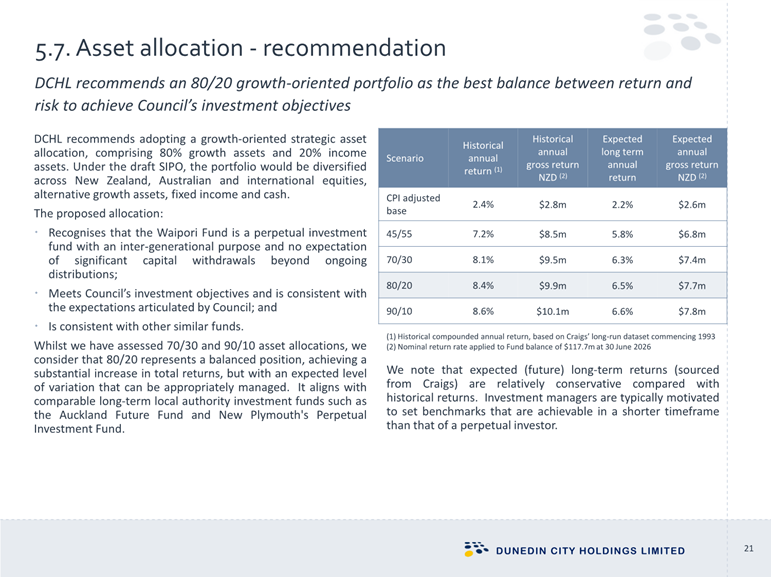
most significant change proposed in the SIPO relates to strategic asset
allocation. DCHL recommends that this is changed from the current balanced
income approach comprising circa 45% growth assets and 55% income assets to a
growth-oriented portfolio comprising 80% growth assets and 20% income assets.
DCHL considers that this allocation represents the best balance between return
and risk.
5 This
change requires Council to accept that the return objective is a long term one
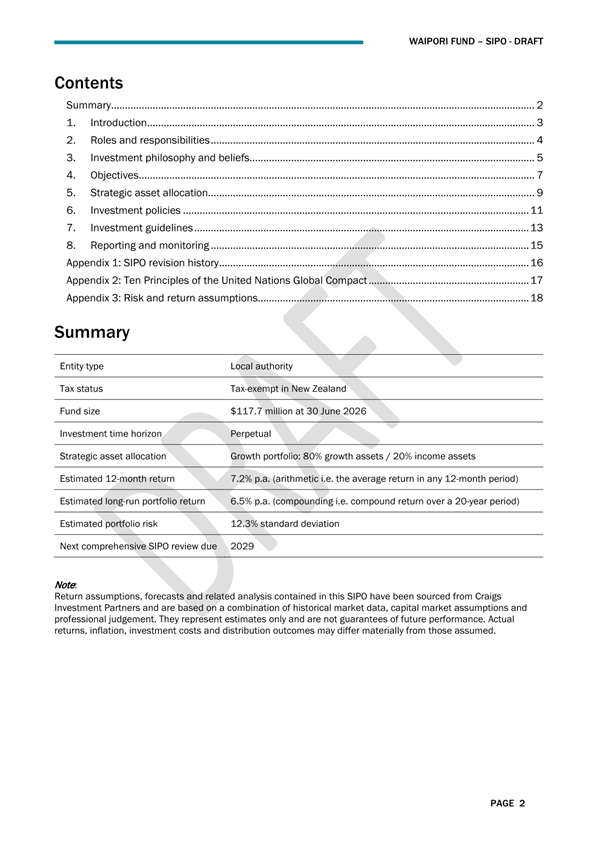
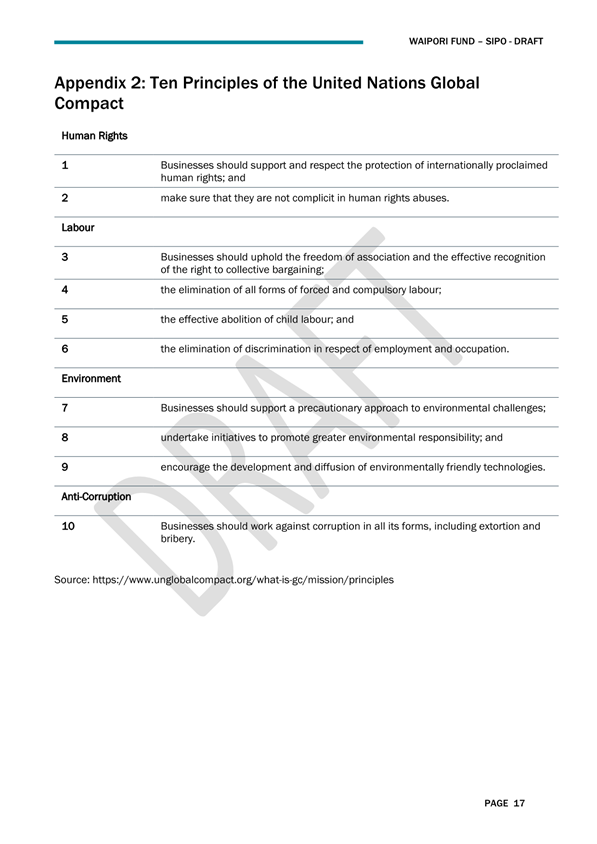
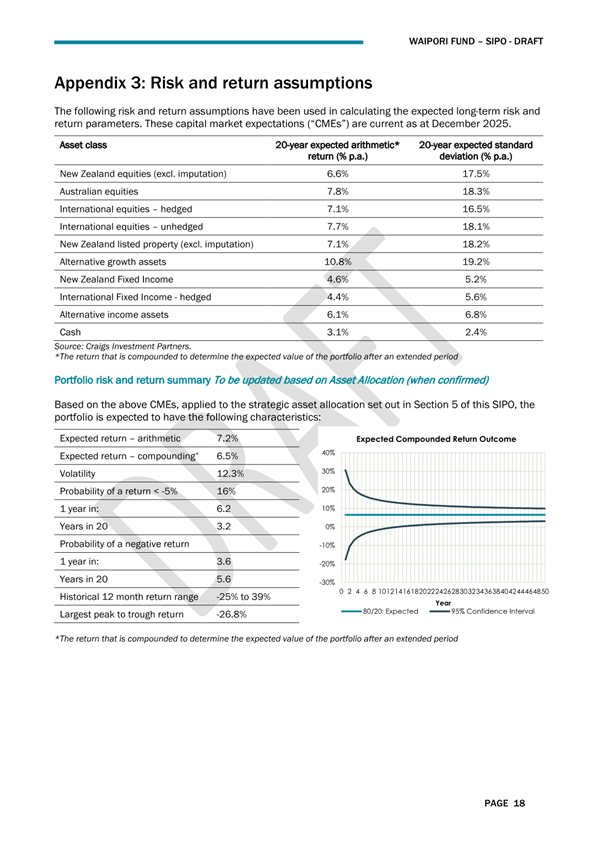
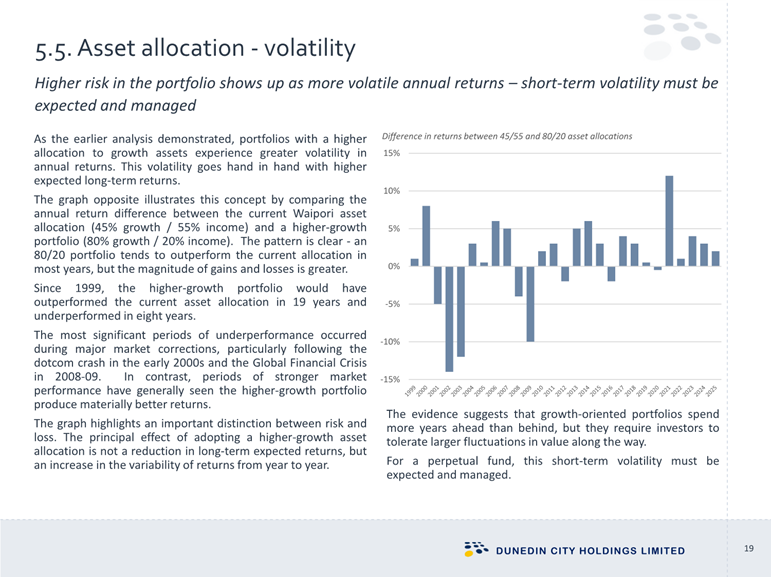
that may not be achieved in every measurement period. Short-term volatility
must be expected and managed. Evidence suggests that growth-oriented portfolios
spend more years ahead than behind, but they require investors to tolerate
larger fluctuations in value along the way.
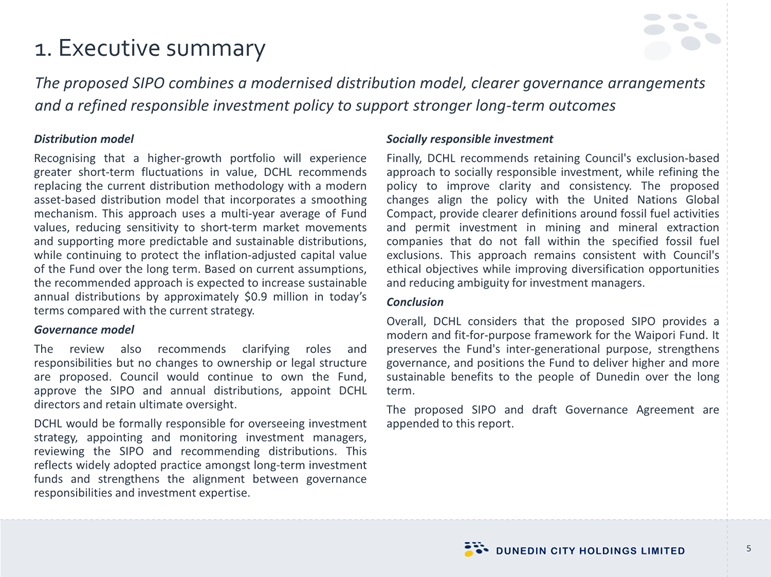
6 Other
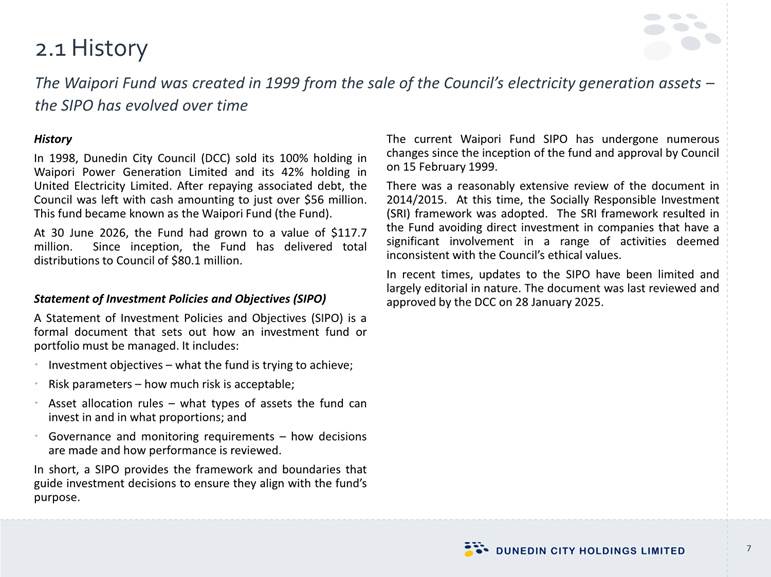
proposed changes to the SIPO include an asset-based distribution model
incorporating a smoothing mechanism and a transition period, to create a
buffer. It provides clearer governance arrangements and clarifies the socially
responsible investment provisions.
7 In
the medium to long term, these changes could result in consistently higher
distributions.
8 The
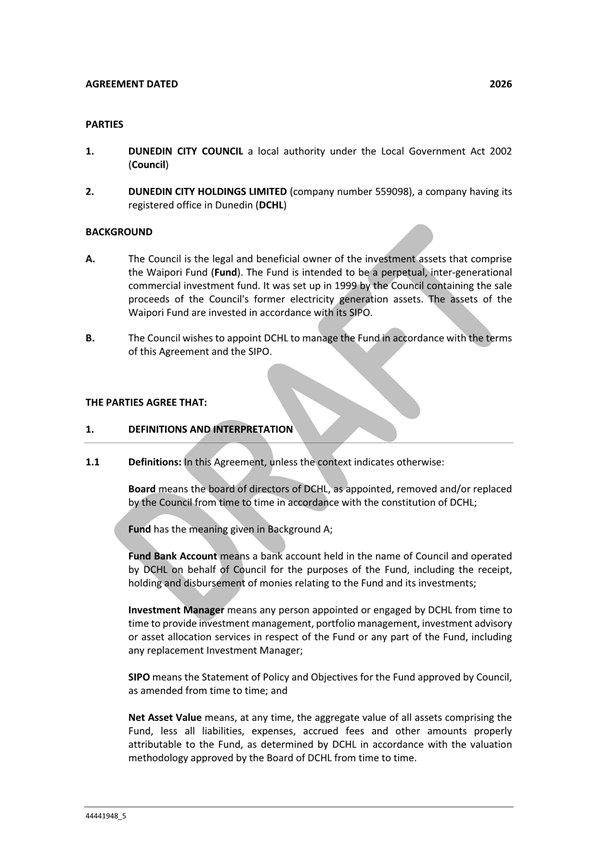
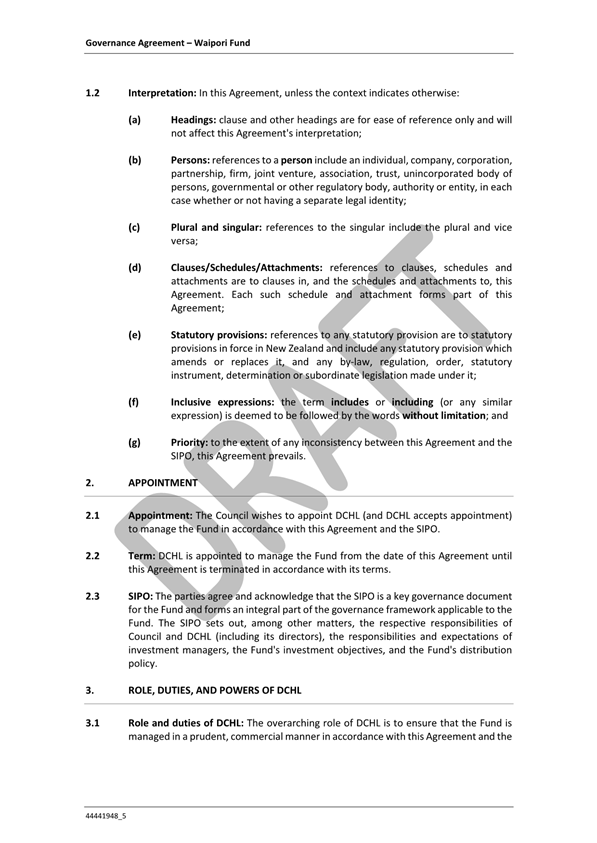
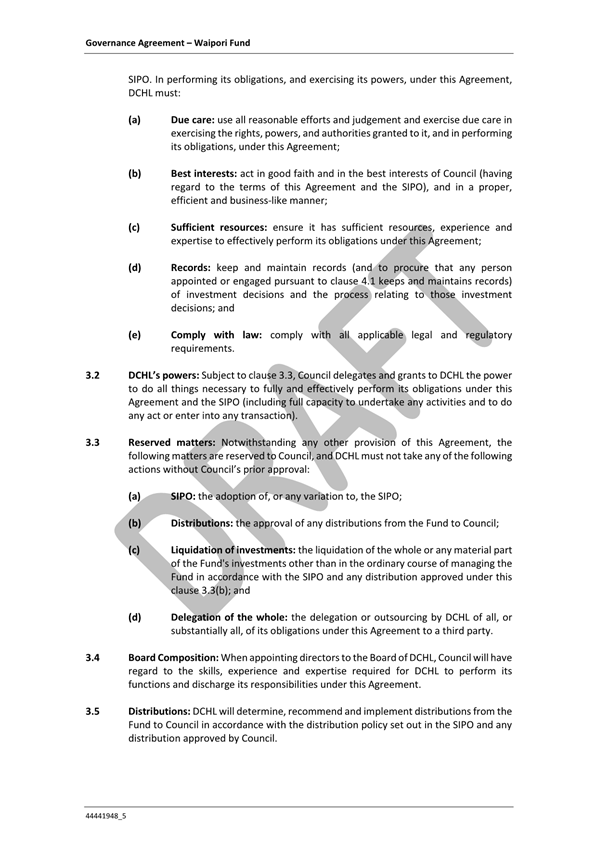
purpose of the proposed Governance Agreement is to formalise the relationship
that Council has with DCHL in its management of the Waipori Fund. It sets out
the terms under which DCHL is to manage the fund, documenting what is primarily
current practice.
RECOMMENDATIONS
That the Committee:
a) Notes the Waipori Fund
SIPO Review.
b) Approves an option for
updating the Waipori Fund Statement of Investment Policy Objectives.
c) Approves the draft Governance Agreement between DCC and DCHL.
BACKGROUND
9 The
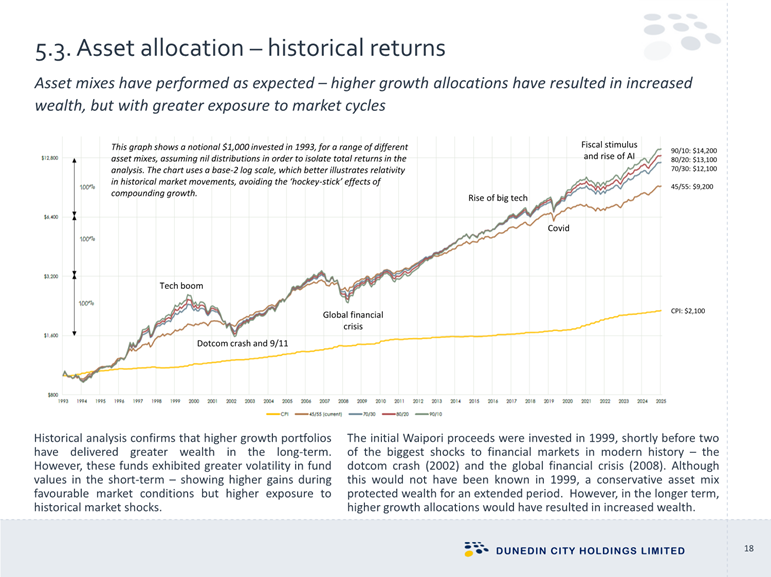
Waipori Fund (the Fund) was established in 1998 following the sale of the
Waipori Power Generation Limited and its holding in United Electricity Limited.
The value of the Fund when established was $56 million. At 30 June 2026, the
value of the Fund is $117.7 million.
10 A Statement
of Investment Policy and Objectives (SIPO) provides all parties involved in the
investment management of the Fund with clear guidance on how the assets of the
Fund are to be managed.
11 The SIPO
was last updated, with minor changes for clarification, in January 2025. The
current SIPO is provided at Attachment B. At that time, Council was in the
process of developing an Investment Plan. In its December 2024 Letter of
Expectation to DCHL, Council requested that DCHL undertake a review of the
draft Investment Plan. The DCHL Board was asked to present options to the DCC
on how its investments, including the DCHL trading companies, the Waipori Fund
and the Council’s investment property portfolio are managed and reported
on.
12 At the
time, it was agreed by Council that until the Investment Plan is completed and
approved by Council, it is recommended that the current asset allocation
included in the SIPO be unchanged.
13 It was also
noted that there is currently no specific management agreement in place for the
Waipori Fund. It was recommended that a formal agreement be developed between
DCC and DCHL, the Fund Manager. This work has been undertaken, and the proposed
Governance Agreement is at Attachment A.
14 Work by
DCHL to develop an Investment Framework for the DCC in ongoing. An update on
this process is provided in a separate report on this agenda. However, in the
December 2025 Letter of Expectation to DCHL, Council requested that DCHL:
“Review the Waipori Fund Statement of Investment
Policy and Objectives (SIPO), and present options to Council for consideration,
with different risk appetites along with expected returns, with a view to
maximising return on investment.”
DISCUSSION
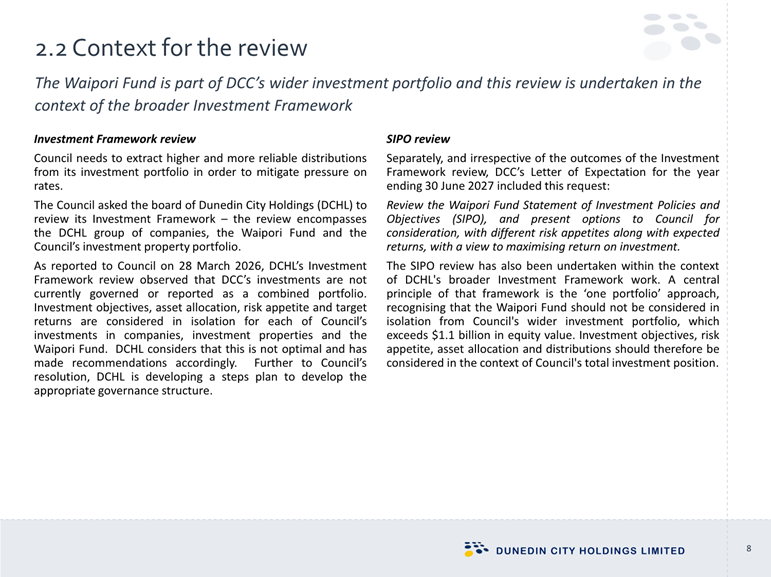
15 DCHL has
completed its review of the Waipori Fund SIPO. DCHL’s report is at
Attachment A. Appended to its report are:
a) A
proposed SIPO, and
b) A draft
Governance Agreement between DCC and DCHL.
SIPO review
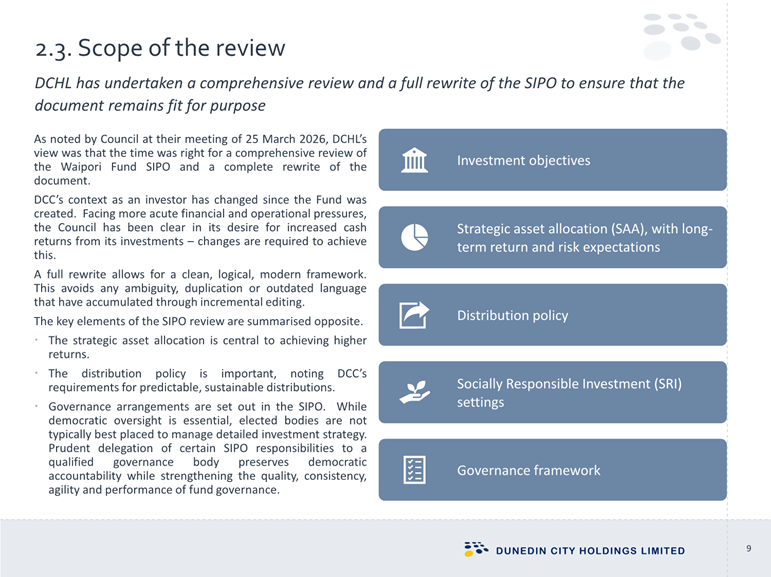
16 In response
to Councils request, DCHL has completed a comprehensive review of the current
SIPO. It has undertaken its review in the context of:
a) Council’s
expectation to seek increased returns from investments to mitigate pressure on
ratepayers, and
b) DCHL’s
broader Investment Framework work. A central principle of this work is the
‘one portfolio’ approach, which recognises that the Fund should not
be considered in isolation to the wider investment portfolio of Council.
17 DHCL
concluded that:
a) the
Fund remains fundamentally sound and has achieved its core objectives with the
real value of the original capital based being maintained, while the fund has
distributed more than $80 million to Council, and
b) the current
asset allocation of the Fund is relatively conservative for a perpetual,
intergenerational investment fund, and this limits the Fund’s ability to
generate stronger long-term returns and distributions.
18 DCHL recommends
that Council retain but clarify the Fund’s core purpose by adopting four
investment objectives to balance the interests of current and future ratepayers
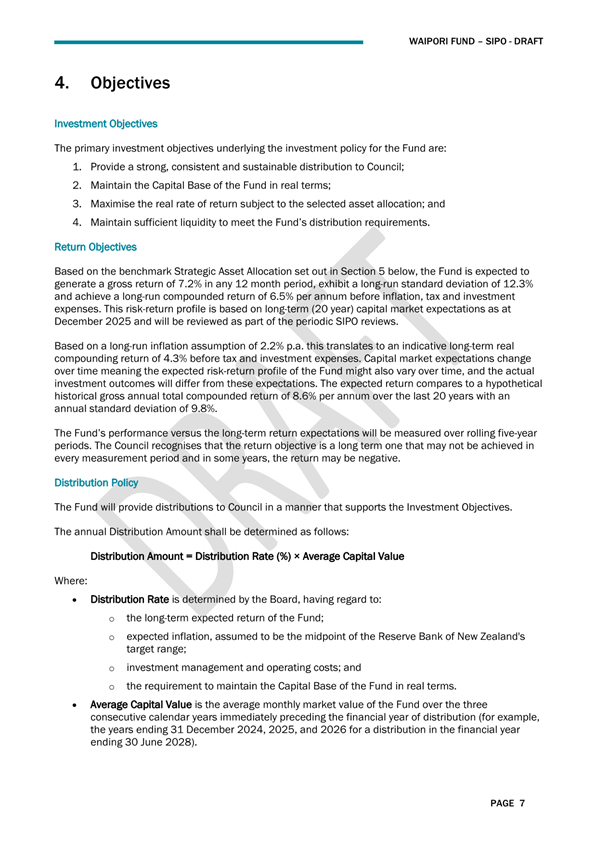
and guide investment decisions. The objectives are:
i) Provide
a strong, consistent and sustainable distribution to Council;
ii) Maintain
the capital base of the Fund in real terms;
iii) Maximise
the real rate of return subject to the selected asset allocation; and
iv) Maintain
sufficient liquidity to meet the Fund’s distribution requirements.
19 DCHL
proposes a revised SIPO that it believes provides a modern and fit-for-purpose
framework for the Fund. The key changes are:
a) Strategic
Asset Allocation – this is the most significant change from the current
balanced income approach comprising circa 45% growth assets and 55% income
assets to a growth-oriented portfolio comprising 80% growth assets and 20%
income assets. DCHL considers that this allocation represents the best balance
between return and risk.
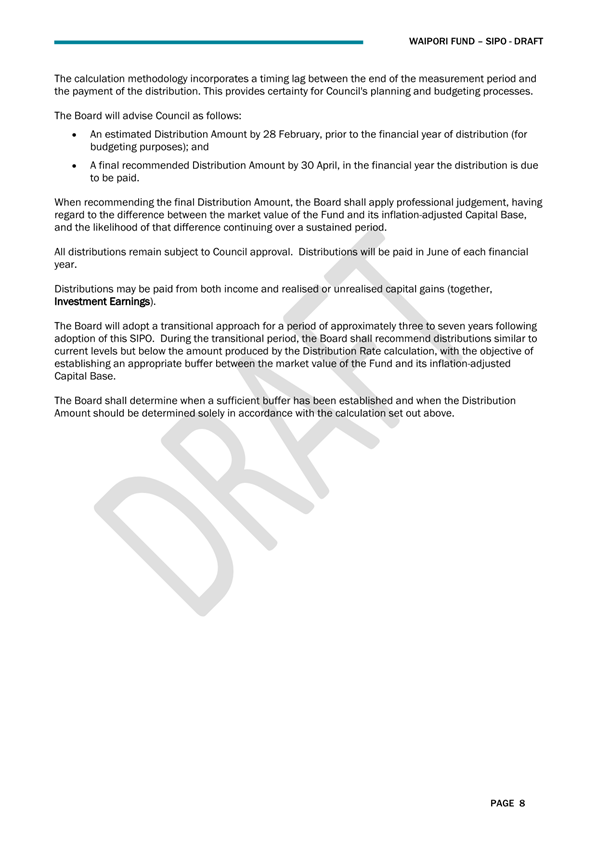
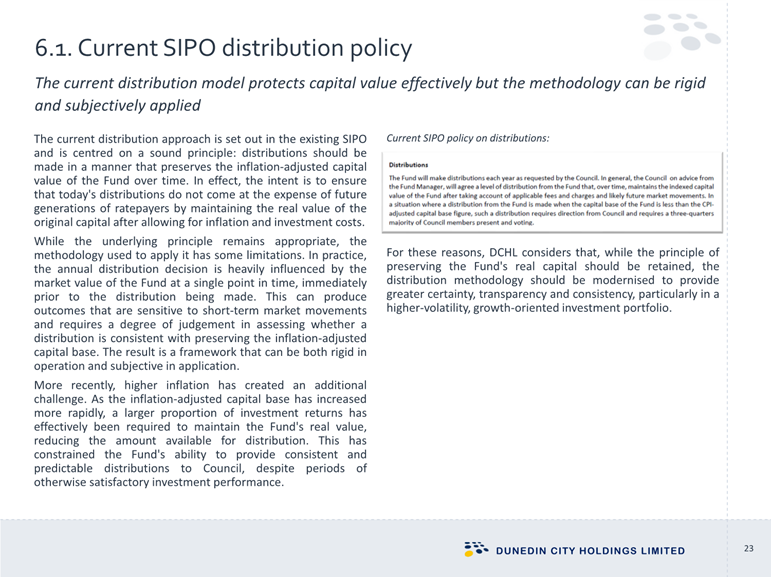
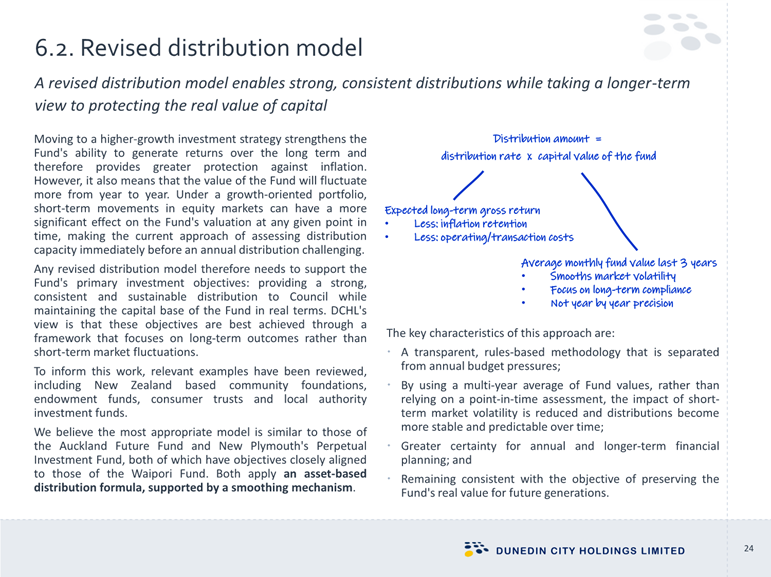
b) Distribution
Model - the current model, where the annual distribution is heavily influenced
by the market value of the Fund at a single point in time, is replaced with an asset-based distribution model that incorporates a
smoothing mechanism. It sets a multi-year average of the Fund values which
reduces sensitivity to short-term market movements and supports a more
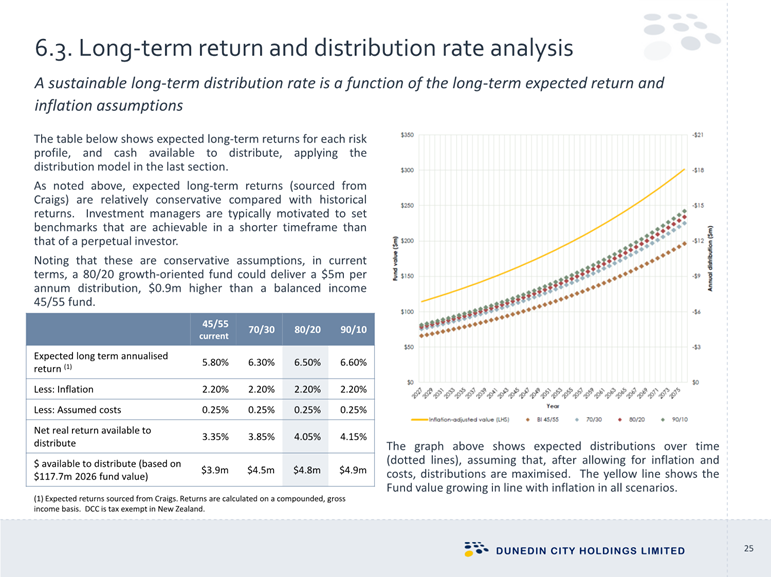
predictable and sustainable distribution. Based on current assumptions,
expected annual distributions would increase by approximately $0.8 million in
today’s terms.
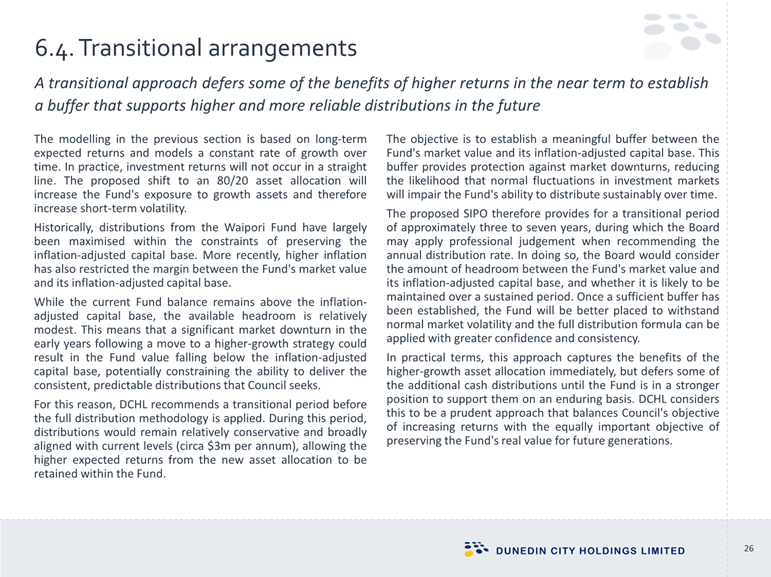
i) DCHL
recommends a transition period before the full distribution methodology is
applied. This would enable the establishment of a buffer to support higher
returns during periods of short-term volatility. It will take three to seven
years, during which time, DCHL will apply professional judgement when
recommending the annual distribution rate.
c) Governance
Model – clearer governance arrangements with no change to ownership or
legal structure. Council will continue to own the Fund, approve the SIPO and
annual distributions. DCHL will have responsibility for oversight of the
investment strategy, appointing and monitoring investment managers, reviewing
the SIPO and recommending distributions.
d) Socially
Responsible Investment – the proposed SIPO retains the exclusion-based
approach to socially responsible investment, with refinements to improve
clarity and consistency.
Risk
20 At
a recent risk workshop including elected members and management, an indicative
risk appetite for financial sustainability, using the table below, was
identified as conservative to balanced.
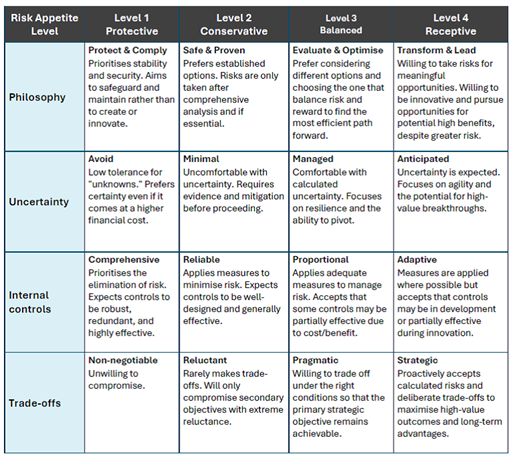
21 Council's
current SIPO adopts a relatively low risk/return profile, with a maximum
allocation of 60% to equities. This is considered consistent with the conservative financial
sustainability risk appetite.
22 The
proposed increase to a maximum of 80% equities would result in a higher
risk/return profile. While this would move beyond a conservative investment
approach, it remains consistent with a balanced
risk appetite, reflecting a greater willingness to accept investment market
volatility in return for higher long-term returns.
23 DCHL also
assessed the Council’s risk profile by determining risk need, risk taking
ability and behavioural risk tolerance. DCHL concluded that a growth-orientated
risk profile is deemed to be appropriate for the Fund.
24 Higher
returns require a higher exposure to assets that can grow in value over time.
The trade-off is that a growth-oriented portfolio will experience greater
volatility.
25 The DCHL report states that evidence suggests growth-oriented
portfolios spend more years ahead than behind, but they require investors to
tolerate larger fluctuations in value along the way.
Mitigations
and controls
26 The
proposed SIPO provides that the return objective is a long term one that may
not be achieved in every measurement period. Short-term volatility must be
expected and managed. Decisions would be made with a long-term perspective.
27 The
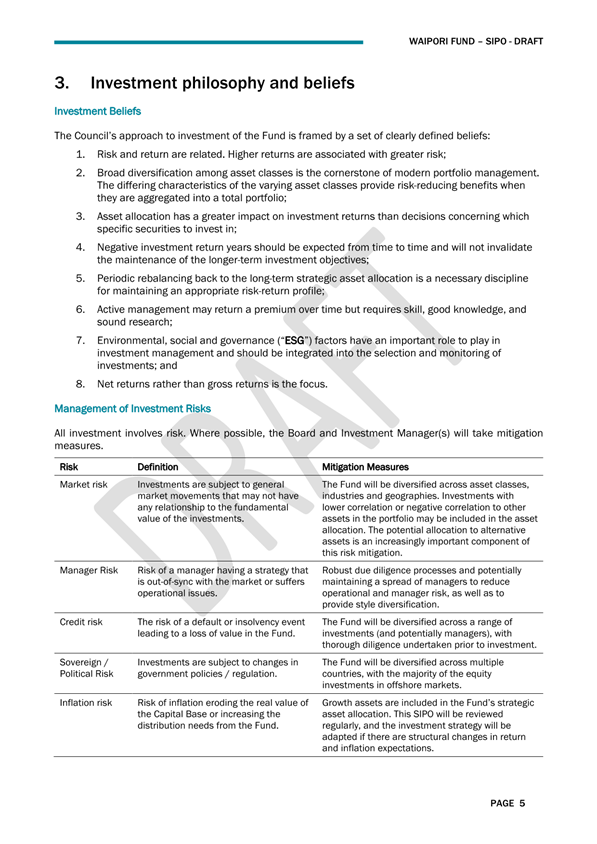
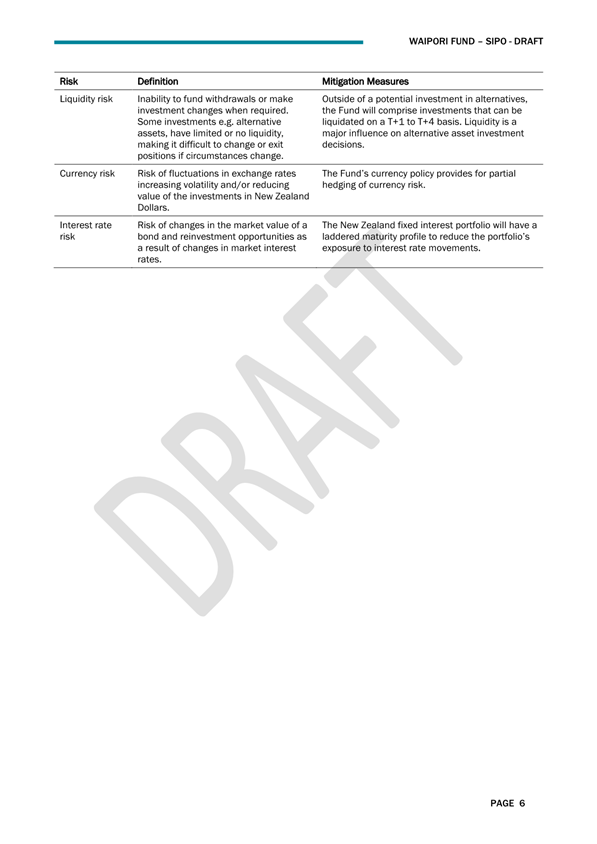
proposed SIPO provides a summary table of risks and mitigation measures that
will be taken by the Board of DCHL and Investment Managers. Along with these,
there are additional measures, some of which are highlighted in the paragraphs
below.
28 The
proposed transition period, which creates a buffer, lets the Fund grow to build
in the buffer.
29 The
proposed distribution model uses a rolling three year average period which
provides a smoothing effect against the increased volatility in the Fund.
30 Appropriate
diversifications across sectors of the portfolio are clearly identified in the
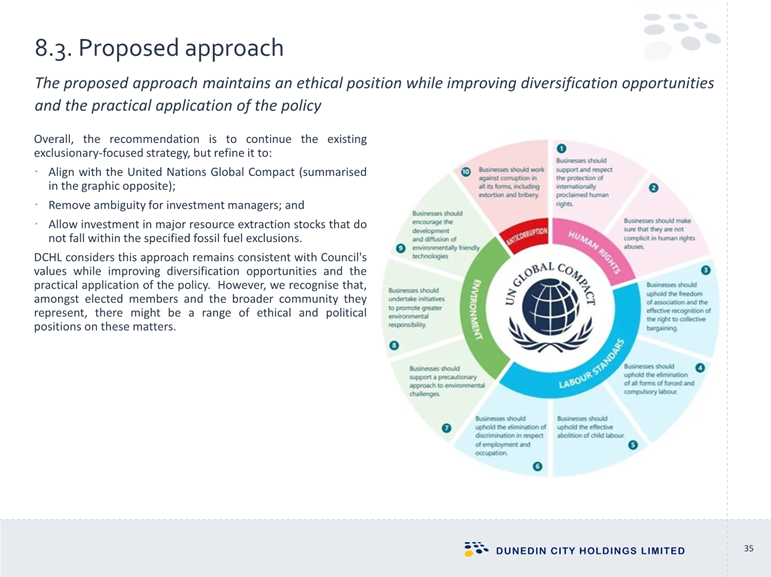
proposed SIPO. This includes alignment with the United Nations Global Compact,
which provides a widely recognised and objective framework for assessing
environmental, social and governance issues.
31 Holding
limit percentages and exposure limits would apply across the total portfolio.
32 Performance
is measured and reviewed. The DCHL Board will monitor performance on a regular
basis, and Council would continue to receive regular reporting on Fund
performance and how the Fund is being managed to achieve its objectives.
33 The fixed
interest portfolio will have a laddered maturity profile, i.e., a spread of
maturity dates.
Governance Agreement
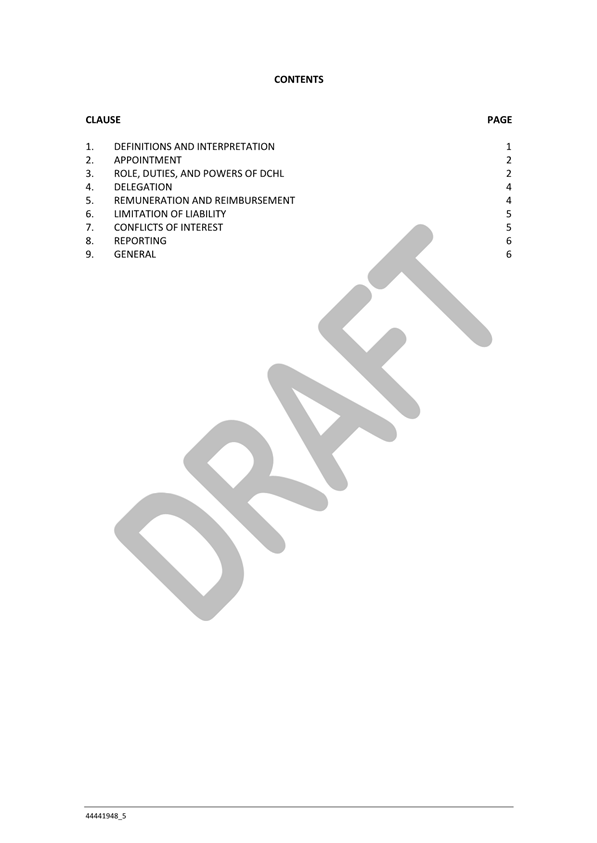
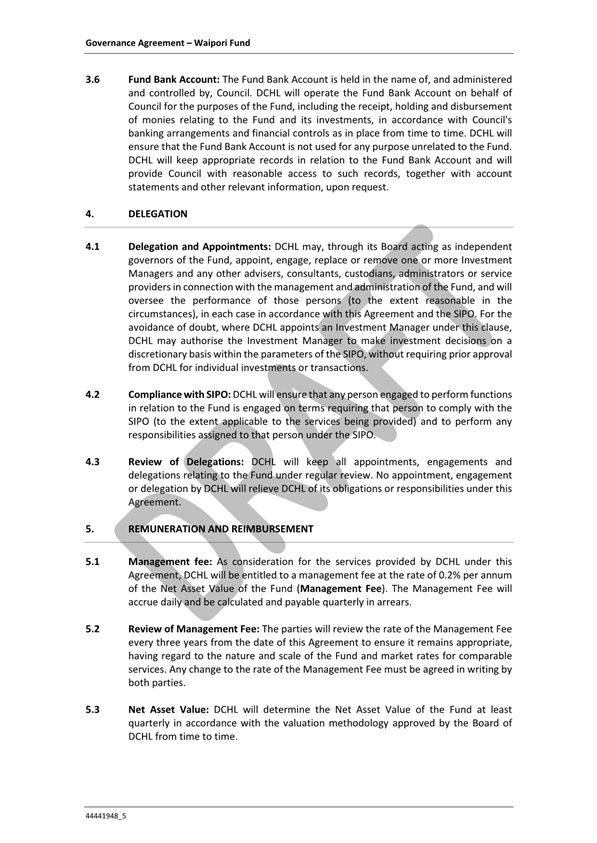
34 DCHL has
drafted a proposed Governance Agreement. This agreement formalises the
relationship that Council has with DCHL in its management of the Waipori Fund.
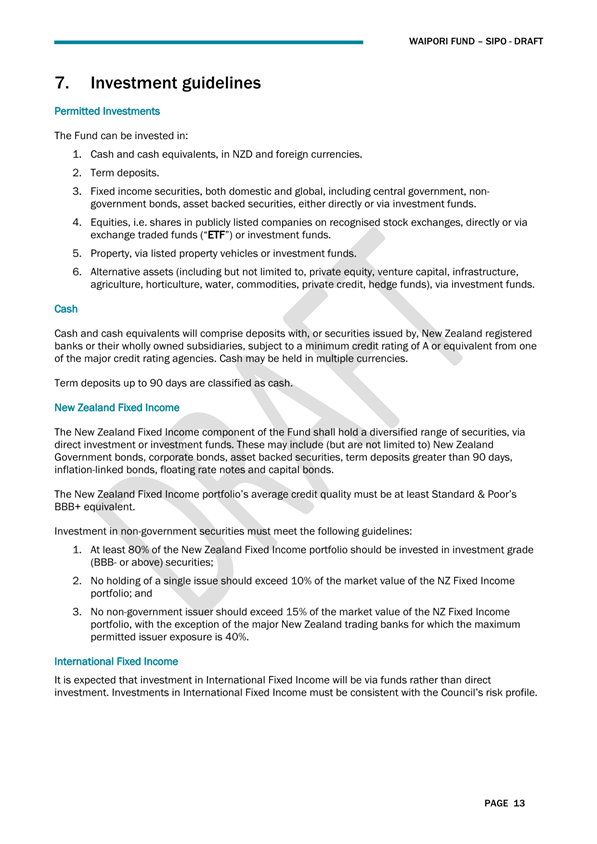
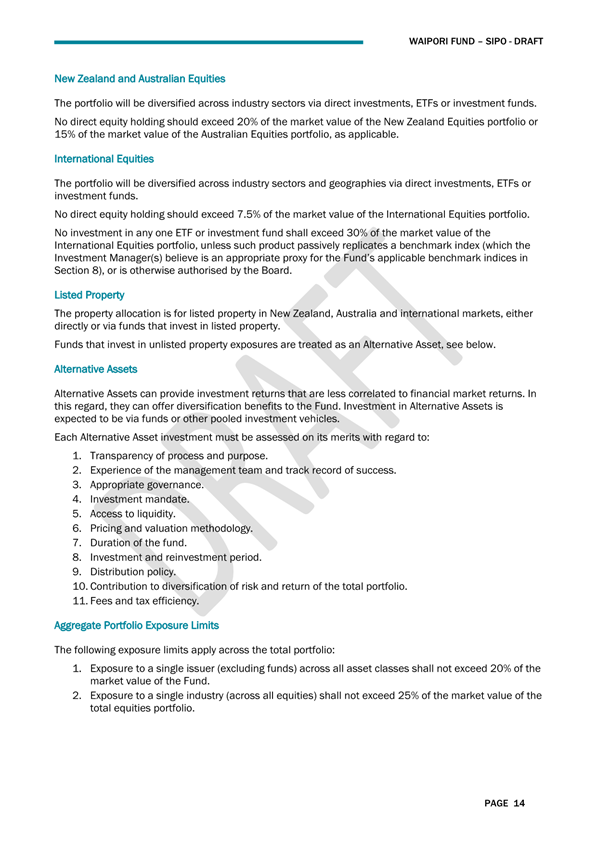
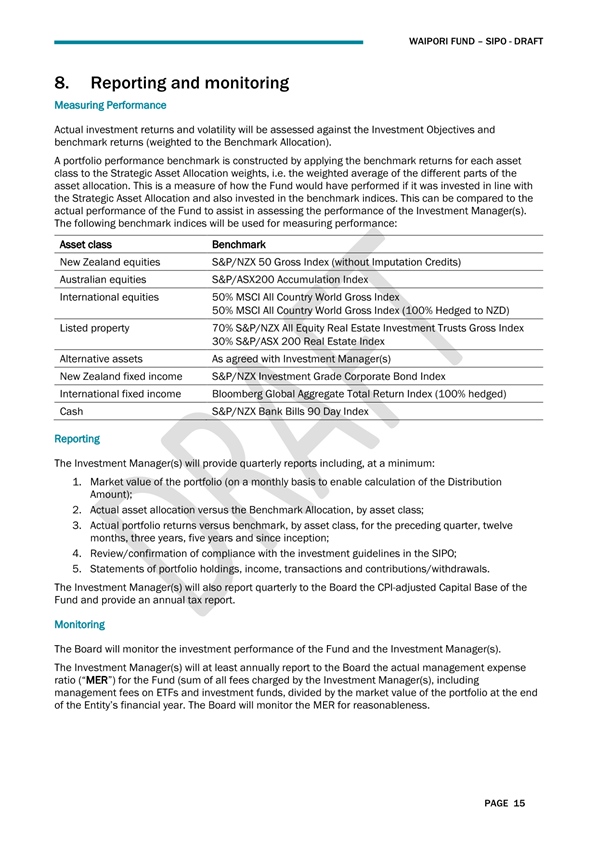
It includes the following:
a) Roles,
duties, and powers of DCHL – ensure the fund is managed in a prudent,
commercial manner.
b) Delegations
– ability to appoint, engage, replace, or remove one or more Investment
Managers, and any other advisors and consultants etc.
c) Remuneration
and reimbursement – a management fee would be payable at the rate of 0.2%
per annum of the Net Asset Value of the Fund.
d) Limitation
of liability – DCHL will have no liability for investment losses in value
of the Fund for any act or omission in connection with the Fund, unless
attributable to fraud, wilful misconduct or wilful breach of the agreement, or
gross negligence.
e) Conflicts
of interest – DCHL to maintain policies and procedures for
identification, disclosure, and management of conflicts of interest.
f) Reporting
– to provide quarterly reports to Council, and any additional reporting
as agreed.
Other matters
35 Section
29.1 of Standing Orders provides that the DCC may only divest all or any part
of the Waipori Fund by a three-quarters majority of the members present and
voting.
36 Divest
means converting, in any way whatsoever, the Waipori Fund for a use other than
as set out in the SIPO.
37 Any
recommendations made by DCHL for a distribution of the Fund will also be
assessed under this Standing Order.
38 Further to
a Councillor request regarding the use of the anglicised spelling of Waipori,
we will engage with Mana Whenua to seek their views on the potential use of
Waipōuri as an alternative spelling for the Waipori Fund.
OPTIONS
39 The
Committee is asked to consider three options relating to the Fund SIPO discussed
below.
Option One – Approve the proposed SIPO
40 This option
would approve the proposed SIPO prepared by DCHL and provided in Attachment A.
Advantages
· Supports
the Council’s desire for higher and more reliable distributions over the
medium to long-term.
· Larger
exposure to equities should deliver higher growth over the long term. This
should translate into the ability to pay out more in distributions over the
long run.
· In
the medium to long term, consistently higher distributions. Based on current
assumptions, an increase in annual distributions of approximately $0.8 million
in today’s terms is expected.
· A
larger exposure to equities (growth assets) is a better hedge against
inflation. The higher the risk the higher the return.
· The
revised distribution policy, including a smoothing mechanism, provides more
certainty, transparency, and consistency.
· A
transition period of three to seven years will maintain the current level of
distribution, with the aim of developing a “buffer” over the
inflation-adjusted capital base. This will result in the Fund being better
placed to withstand variation in market returns and inflation and consistently
provide higher distributions.
· Environmental,
social and governance settings are clarified.
Disadvantages
· The
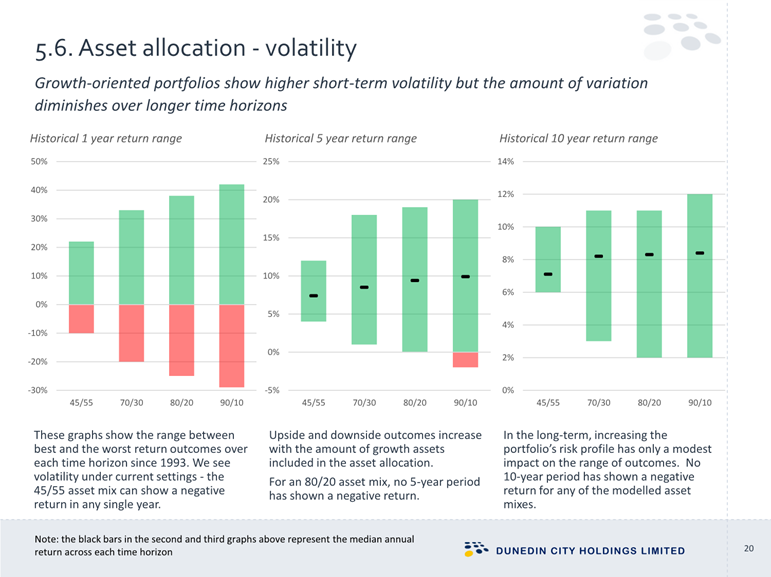
principal effect of adopting a higher-growth asset allocation is an increase in
the variability of returns from year to year. More volatility and, in some
years, the return on the Fund may be negative. Growth-oriented portfolios show
higher short-term volatility, but the amount of variation diminishes over
longer-term horizons.
· Despite
a larger exposure to equities (more risk), and increased volatility in the
Fund, the amount of distribution won’t increase in the near term. This
means that returns would favour future ratepayers over todays.
Option Two – Approve the proposed SIPO in principle,
but with further matters to be considered
41 Under this
option, the Committee would approve the SIPO as proposed in principle, but
Councillors may identify further matters that they would like to be considered
for inclusion or removal from the proposed SIPO.
Advantages
· As
per Option One.
· Provides
an avenue for amending the proposed SIPO for any identified matters for
consideration.
Disadvantages
· As
per Option One.
· Further
work would be required, and there would be a delay in approving a new SIPO for
the Waipori Fund.
Option Three – Do not approve the proposed SIPO
42 Under this
option, the Committee would not approve the proposed SIPO, but ask DCHL to
start the process again using different parameters, as directed by the
Committee.
Advantages
· A
SIPO would be developed that incorporates the requirements of the Committee.
Disadvantages
· Further
work would be required, and there would be a delay in approving a new SIPO for
the Waipori Fund.
NEXT STEPS
43 DCHL will
be notified of the decision made by Council with respect to the proposed SIPO
and Governance Agreement.
44 If
required, any amendments made to the SIPO will be presented to this Committee
and/or Council at a later date for approval.
45 If
approved, the Governance Agreement, subject to a legal review, will be entered
into.
Signatories
|
Authoriser:
|
Carolyn Allan - Chief Financial Officer
|
Attachments
|
|
Title
|
Page
|
|
⇩a
|
Review Report, Proposed
SIPO, Governance Agreement
|
61
|
|
⇩b
|
Waipori Fund SIPO
approved January 2025
|
125
|
|
SUMMARY OF CONSIDERATIONS
|
|
Fit with purpose of Local Government
This decision enables democratic local
decision making and action by, and on behalf of communities.
|
|
Fit with strategic framework
|
|
Contributes
|
Detracts
|
Not applicable
|
|
Social Wellbeing Strategy
|
☐
|
☐
|
✔
|
|
Economic Development Strategy
|
☐
|
☐
|
✔
|
|
Environment Strategy
|
☐
|
☐
|
✔
|
|
Arts and Culture Strategy
|
☐
|
☐
|
✔
|
|
3 Waters Strategy
|
☐
|
☐
|
✔
|
|
Future Development Strategy
|
☐
|
☐
|
✔
|
|
Integrated Transport Strategy
|
☐
|
☐
|
✔
|
|
Parks and Recreation Strategy
|
☐
|
☐
|
✔
|
|
Other strategic projects/policies/plans
|
☐
|
☐
|
✔
|
There are no direct contributions to the Strategic
Framework.
|
|
Māori Impact Statement
Council budgets and how they are funded impact broadly
across all Dunedin communities including Māori. The adoption of Te Taki
Haruru – Māori Strategic Framework signals Council’s
commitment to mana whenua and to its obligations under the Treaty of
Waitangi.
|
|
Sustainability
Sustainability is an underlying principle of the
DCC’s strategic framework. The proposed SIPO addresses financial
sustainability in terms of sustainable long term distributions and socially
responsible investment.
|
|
Zero carbon
The proposed SIPO for the Waipori Fund have no expected
implications for city and DCC emissions. The Waipori Fund SIPO notes that the fund seeks to avoid
direct investment in companies that have a significant involvement in a range
of activities deemed to be inconsistent with the Council’s ethical
position, including fossil fuel extraction. This aligns with the Zero Carbon
Policy, by minimising the emissions impact of DCC’s activities.
|
|
LTP/Annual Plan / Financial Strategy /Infrastructure
Strategy
Summary information on the Waipori Fund is included within
the Financial Strategy. The development of the Financial Strategy for the
2027-37 Long Term Plan will incorporate the revised assumptions that would
result from the proposed SIPO.
|
|
Financial considerations
The proposed SIPO sets out how the assets of the Waipori
Fund are to be managed. The financial impacts of the proposed SIPO, including
the increased variability in financial results are discussed in detail in the
report.
|
|
Significance
The decision to move from a conservative to balanced
management Fund is considered to be of low significance in terms of the
Council’s Significance and Engagement Policy.
|
|
Engagement – external
The proposed SIPO and draft governance agreement have been
prepared by DCHL.
|
|
Engagement - internal
The proposed SIPO and draft governance agreement have been
discussed with management.
|
|
Risks: Legal / Health and Safety etc.
Risks are considered in the body of the report.
|
|
Conflict of Interest
There are no known conflicts of interest.
|
|
Community Boards
There are no known implications for the Community Boards.
|
|
|
Finance and Performance Committee
27 August 2026
|
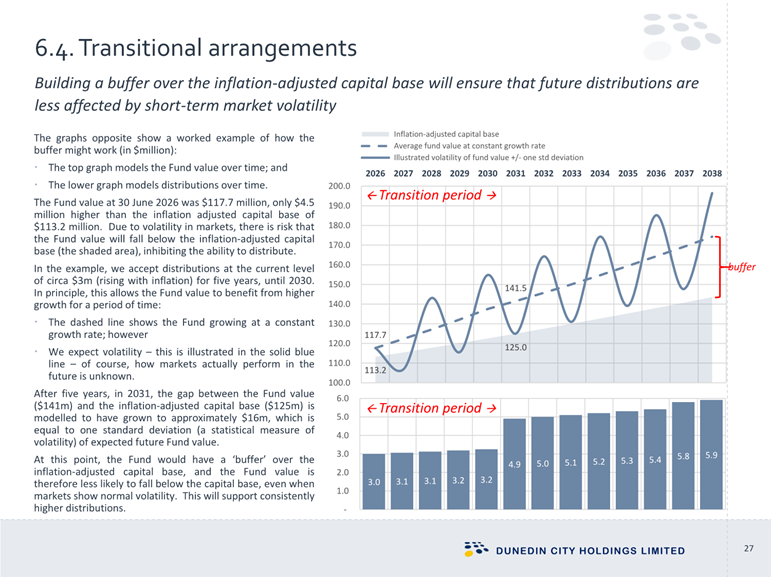
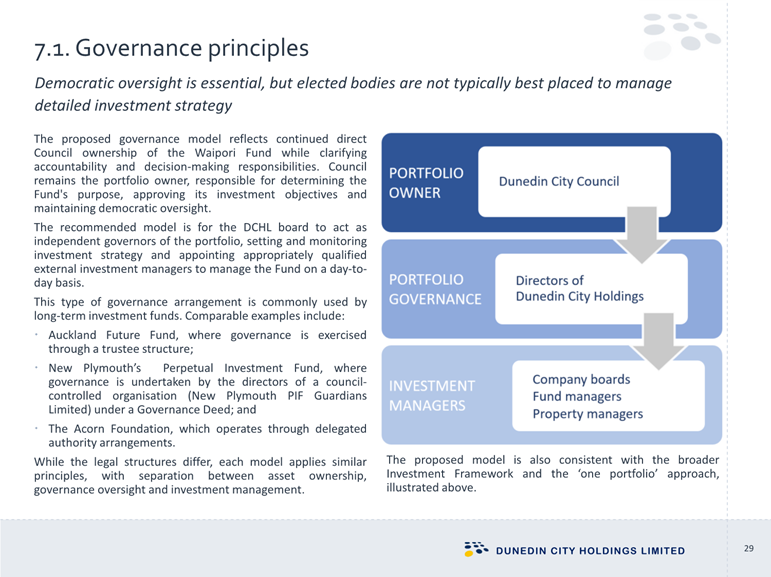
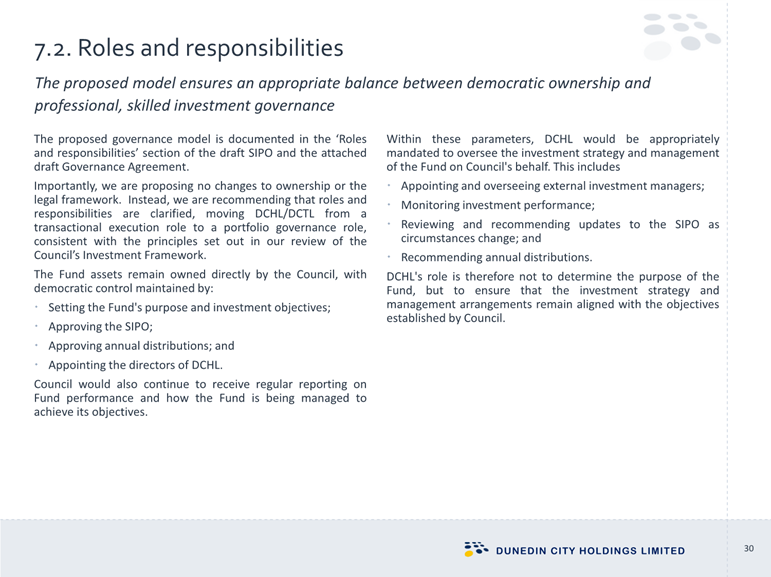
|
|
Finance and Performance Committee
27 August 2026
|
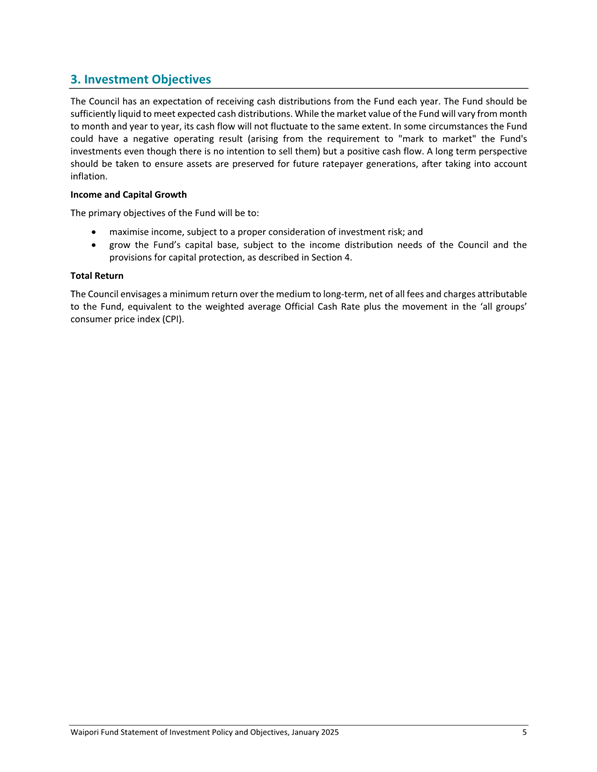
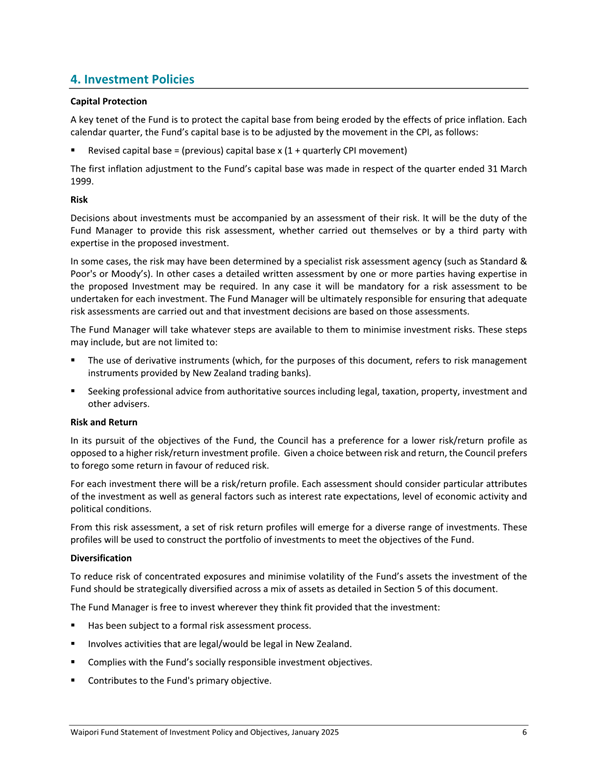
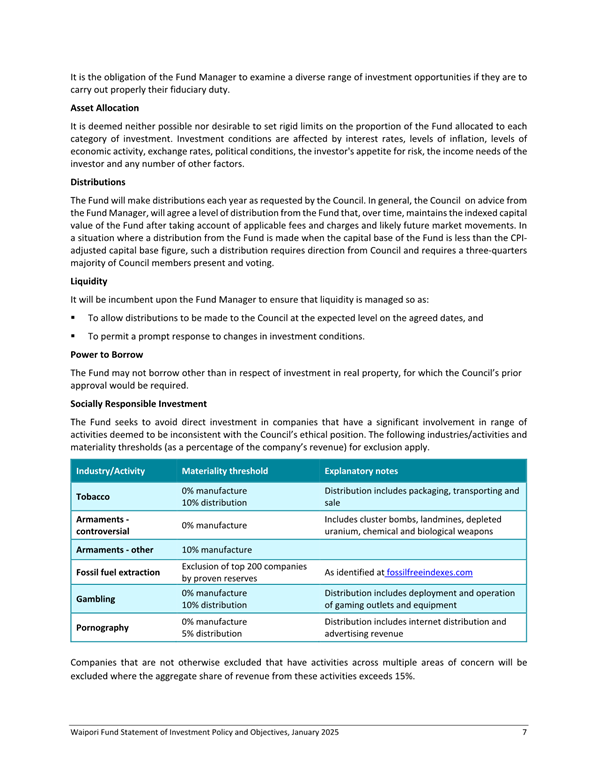
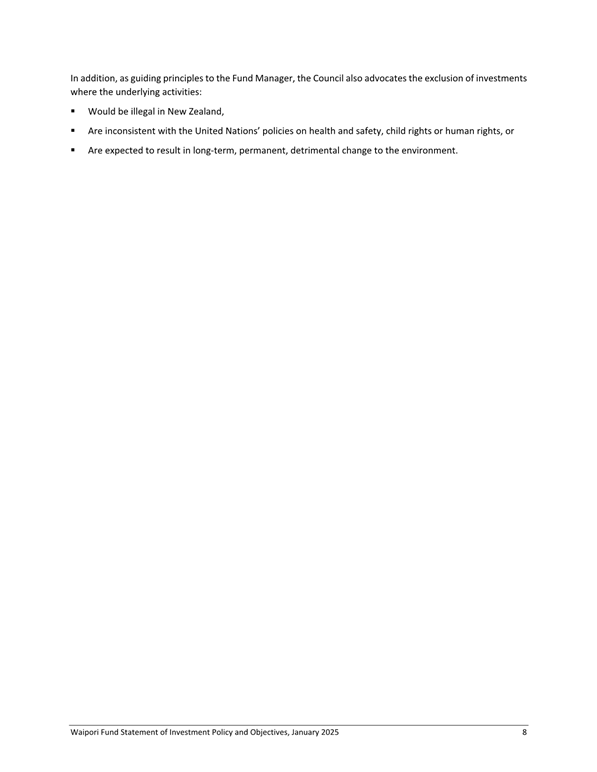
|
|
Finance and Performance Committee
27 August 2026
|
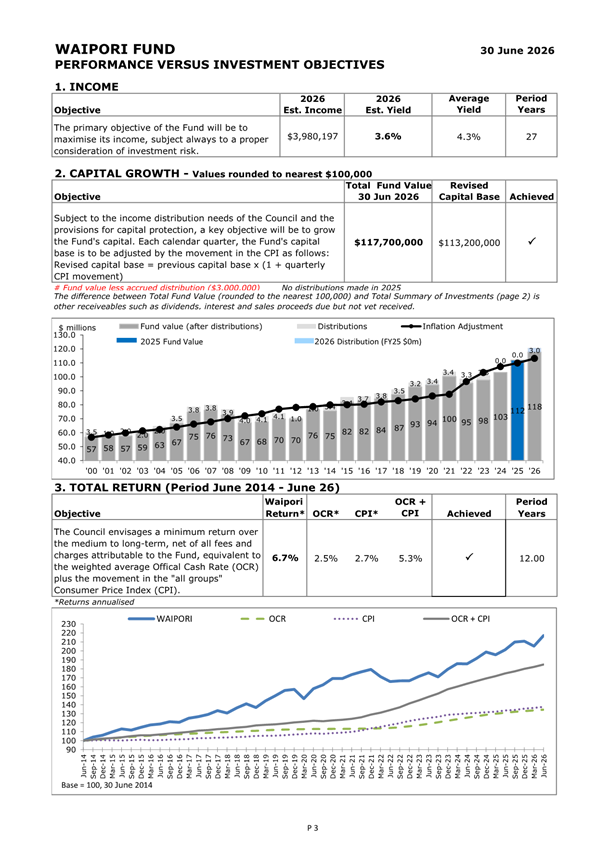
Waipori Fund - Quarter Ending 30 June 2026
Department: Finance
EXECUTIVE SUMMARY
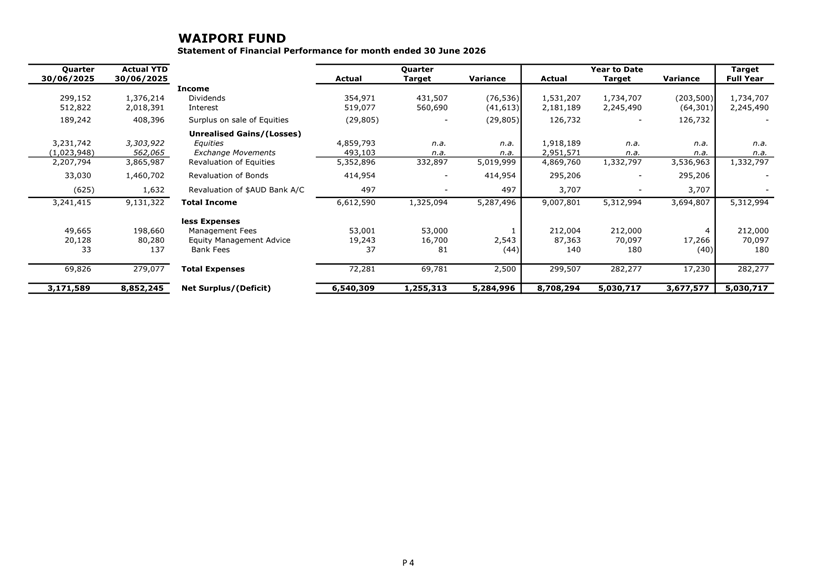
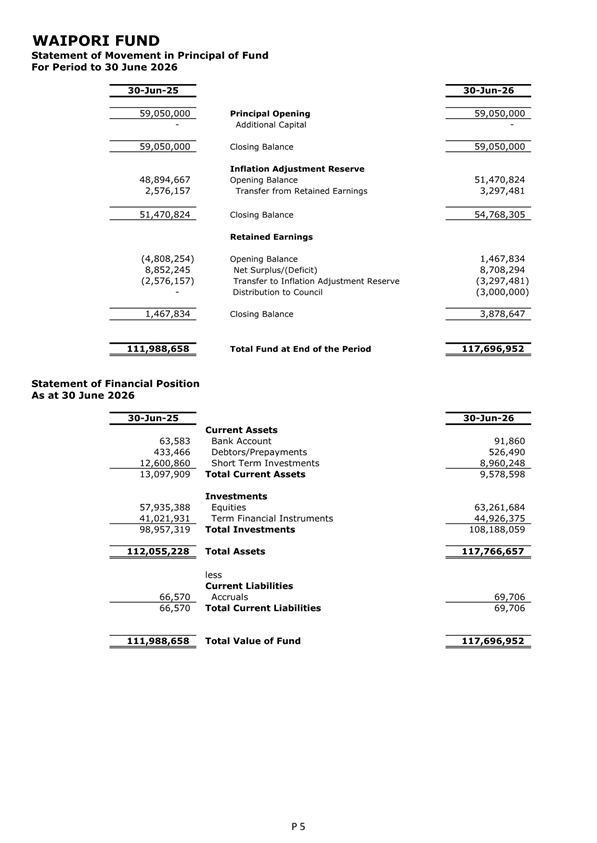
1 The
attached report from Dunedin City Treasury Limited provides information on the
results of the Waipori Fund for the quarter ended 30 June 2026.
RECOMMENDATIONS
That the Committee:
a) Notes the report from
Dunedin City Treasury Limited on the Waipori Fund for the quarter ended 30 June
2026.
DISCUSSION
2 The
Waipori Fund Statement of Investment Policy and Objectives (SIPO) requires
quarterly reporting on the performance and financial position of the fund.
3 Dunedin
City Treasury Limited has provided the Waipori Fund report for the June 2026
quarter. The report is provided as Attachment A.
OPTIONS
4 As
this is a noting report, no options are provided.
NEXT STEPS
5 Quarterly
reporting on the performance and financial position of the fund will be
provided to future meetings of either the Finance and Performance Committee or
Council.
Signatories
|
Authoriser:
|
Carolyn Allan - Chief Financial Officer
|
Attachments
|
|
Title
|
Page
|
|
⇩a
|
Waipori Fund Quarterly
Report - 30 June 2026
|
141
|
|
SUMMARY OF CONSIDERATIONS
|
|
Fit with purpose of Local Government
This decision enables democratic local
decision making and action by, and on behalf of, communities.
|
|
Fit with strategic framework
|
|
Contributes
|
Detracts
|
Not applicable
|
|
Social Wellbeing Strategy
|
☐
|
☐
|
✔
|
|
Economic Development Strategy
|
☐
|
☐
|
✔
|
|
Environment Strategy
|
☐
|
☐
|
✔
|
|
Arts and Culture Strategy
|
☐
|
☐
|
✔
|
|
3 Waters Strategy
|
☐
|
☐
|
✔
|
|
Future Development Strategy
|
☐
|
☐
|
✔
|
|
Integrated Transport Strategy
|
☐
|
☐
|
✔
|
|
Parks and Recreation Strategy
|
☐
|
☐
|
✔
|
|
Other strategic projects/policies/plans
|
☐
|
☐
|
✔
|
Reporting on the performance of the Waipori Fund does not
contribute directly to the Strategic Framework.
|
|
Māori Impact Statement
Investment returns from the Waipori Fund impact on the
level of rates payable and therefore impact across all Dunedin communities
including Māori.
|
|
Sustainability
There are no impacts for sustainability.
|
|
Zero carbon
There
are no impacts for zero carbon.
|
|
LTP/Annual Plan / Financial Strategy /Infrastructure
Strategy
There are no implications for LTP / Annual Plan /
Financial Strategy / Infrastructure Strategy.
|
|
Financial considerations
Financial considerations are presented in the Waipori Fund
report for the June 2026 quarter.
|
|
Significance
This report is considered to be of low significance in
terms of the Council’s Significance and Engagement Policy.
|
|
Engagement – external
There has been no external engagement.
|
|
Engagement - internal
There has been no internal engagement.
|
|
Risks: Legal / Health and Safety etc.
There are no identified risks.
|
|
Conflict of Interest
There are no known conflicts of interest.
|
|
Community Boards
There are no implications for Community Boards.
|
|
|
Finance and Performance Committee
27 August 2026
|
|
|
Finance and Performance Committee
27 August 2026
|
Significant Forecasting Assumptions - 10 Year Plan and
Water Services Strategy 2027-37
Department: Corporate Policy and Civic
EXECUTIVE SUMMARY
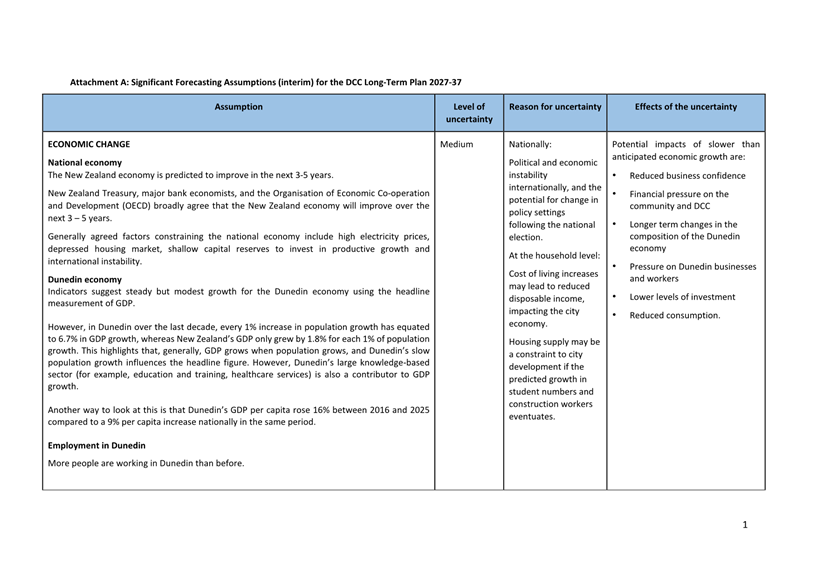
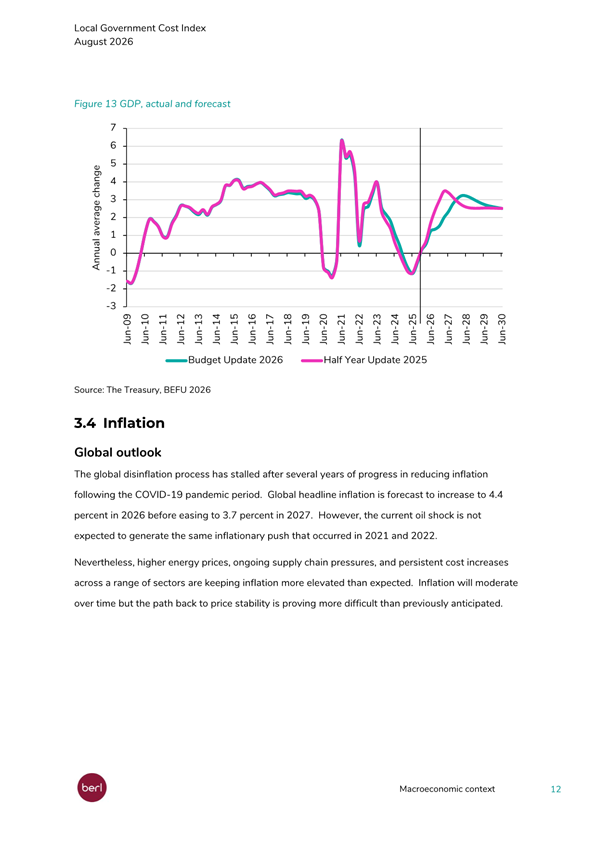
1 The
purpose of this report is to seek the Council’s approval of the draft
Significant Forecasting Assumptions (SFAs) that are to be used in development of
the 10 Year Plan 2027-37 (10 Year Plan) and the Water Services Strategy 2027-37
(Water Services Strategy).
2 The
draft SFAs are at Attachment A.
3 The
supporting information and data for the SFAs are based on the best available
information at time of preparing this report, with potential for material
variation.
RECOMMENDATIONS
That the Committee:
a) Approves the draft significant
forecasting assumptions at Attachment A for the purposes of developing the
10-Year Plan 2027-37 and consulting with the community.
b) Notes that the
information and data supporting these assumptions is interim and that Council
will be updated if further information or updated data becomes available.
BACKGROUND
Significant
forecasting assumptions are a legislative requirement for Long Term Plans and
Water Services Strategies.
4 The
Council is required to adopt a 10 Year Plan and Water Services Strategy every
three years, under the Local Government Act 2002 (LGA) and Local Government
(Water Services) Act 2025 (LGWSA) respectively.
5 Schedule
10, clause 17 of the LGA, and schedule 3, clause 8 of the LGWSA, require
identification of all SFAs and risks underlying the financial estimates.
6 Without
limiting the generality of the above, the financial estimates are based on the
following assumptions:
a) How
long the Council expects its significant assets to remain in service before
they need to be replaced or renewed; and
b) How the
Council expects to fund the future replacement or renewal of those significant
assets.
7 Where
a SFA involves a high level of uncertainty, the long-term plan must identify
the fact of that uncertainty and an estimate of the potential effects of that
uncertainty on the financial estimates.
DISCUSSION
Why do the Long Term Plan and Water Services
Strategy include SFAs?
8 The
SFAs provide Council and the community with an agreed basis for making 10 year
forecasts when the future is uncertain.
9 Using
consistent significant forecasting assumptions:
a) provides
a common planning basis for activities, budgets, asset plans, infrastructure
planning, and financial forecasting;
b) explicitly
identifies any uncertainties;
c) supports
informed decision-making;
d) provides
transparency to the community to better understand choices and trade-offs in
the Plan;
e) supports
audit assurance by presenting supportable and realistic SFAs.
What are the main SFAs that other councils have
used in their most recent Plans?
10 A number of
assumptions were common amongst the 2024-34 Plans for other metropolitan
councils, neighbouring provincial councils, and Auckland Council:
a) Population
growth and demographic change assumptions, underpinning demand for services and
infrastructure (including water services);
b) Climate
change and its impacts, including flooding, severe weather and resilience
requirements;
c) Legislative
reform uncertainty was assumed to continue;
d) Natural
hazards and environmental risks were assumed to influence infrastructure
planning for some councils, or recovery needs for others;
e) Specific to
some councils, like Queenstown-Lakes District Council, tourism-driven seasonal
peaks and rapid urban development and housing demands were assumed.
What are the main SFAs to be used for
Council’s 10 Year Plan and Water Services Strategy 2027-37?
11 The main
significant forecasting assumptions to be included are:
a) Legislative
and regulatory changes
b) Economic
change (including the city’s economic profile and trends)
c) Demographic
changes (total population, ethnic makeup, and age shifts)
d) Growth
and Urban Development changes (households, dwellings, rating-units, land-use
and development patterns)
e) Natural
hazards (resilience and civil defence)
f) Climate
change (climate predictions, mitigation, adaptation, and resilience)
g) Water
Services (in brief)
h) Service
levels
i) Infrastructure
condition and renewals (as infrastructure planning drivers)
j) Deliverability
k) Financial
assumptions
12 Legislative
and regulatory changes are a key source of uncertainty for long term planning.
13 Dunedin
City Council and Queenstown-Lakes District Council submitted a joint Head Start
proposal in August 2026. A decision as to whether the proposal will proceed to
detailed development is expected from the government September 2026, with final
approvals expected in Q2 2027. For any Head Start proposal that is approved,
implementation is expected to begin in mid-2028.
14 A recent
presentation from the Audit Office recommended a ‘business as
usual’ assumption with high uncertainty in situations where decisions
have not yet been made. This type of assumption should be accompanied with a
disclosure to provide context around the uncertainty.
15 It is
likely that some assumptions, including those relating to legislative and
regulatory change, will need to be updated during the development of the 10
Year Plan and Water Services Strategy; where this occurs, an update will be
brought back to Council for consideration.
16 The
majority of SFAs have been included at Attachment A. However, some additional
assumptions will be included in a future update to Council, including
additional financial assumptions, and those for the Waste activity and infrastructure
valuations.
17 The SFAs
will inform the key drivers, challenges and opportunities that the DCC faces in
the period covered by the 10 Year Plan and Water Services Strategy. Examples
include meeting changing needs, such as building resilience to natural hazards,
increases or decreases to levels of service, or delivering on the city-wide and
DCC emission reduction targets.
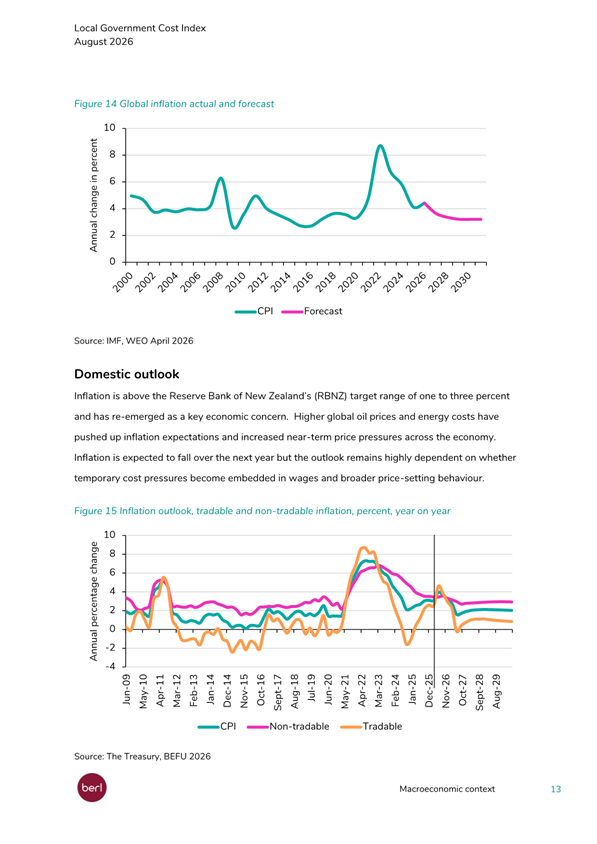
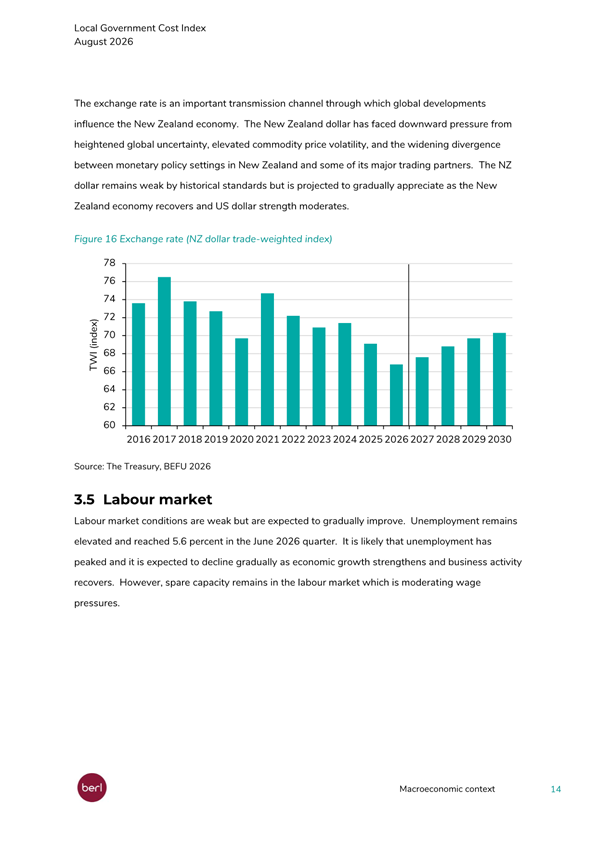
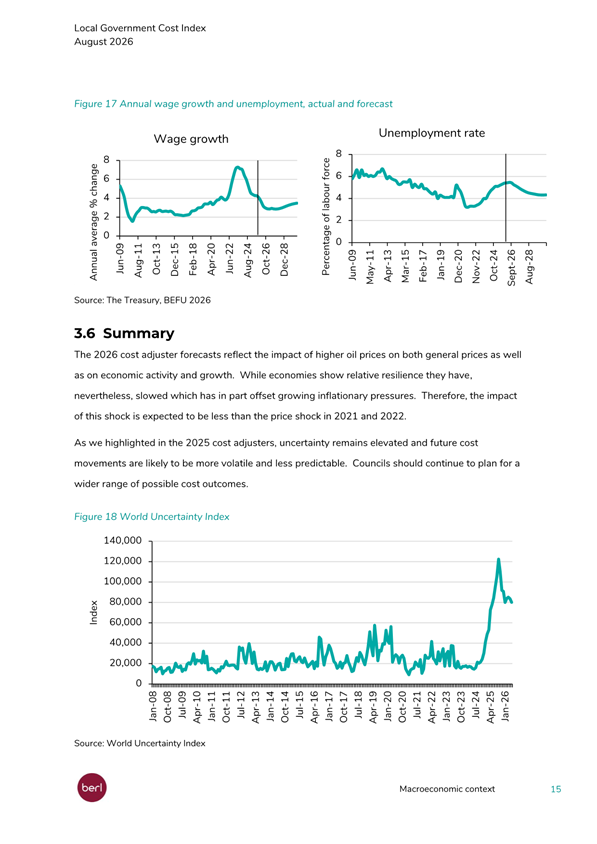
18 The
financial assumptions included at Attachment A include interest rates,
inflation rates, and NZ Transport Agency Waka Kotahi (NZTA) funding assistance
rate assumptions to be used over the 10 year period.
19 Where
possible, external advice has been used to support the assumptions made. For
example, the interest rate assumptions have been provided by Dunedin City
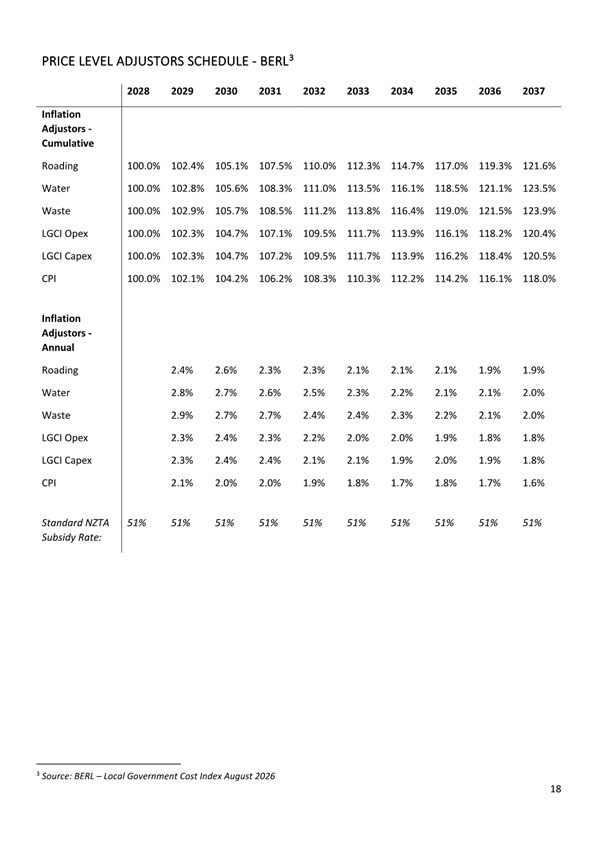
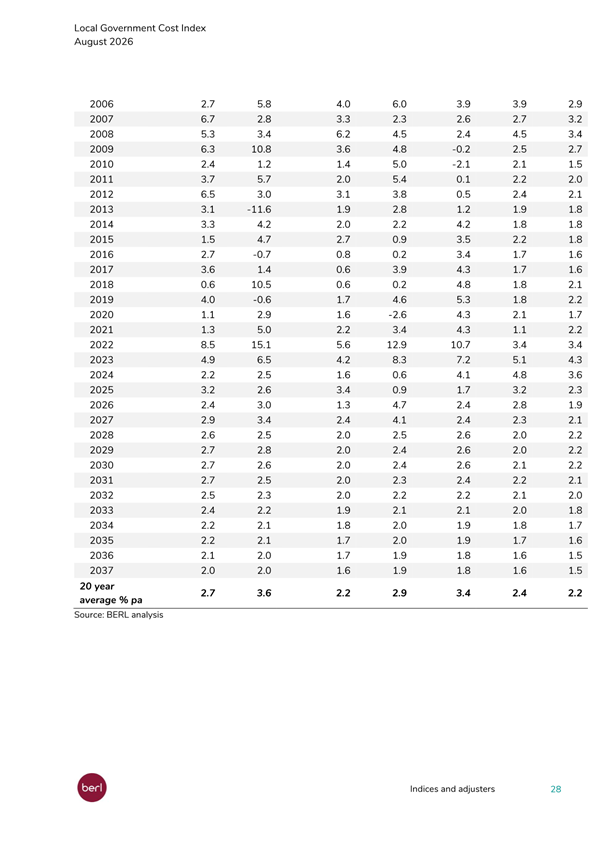
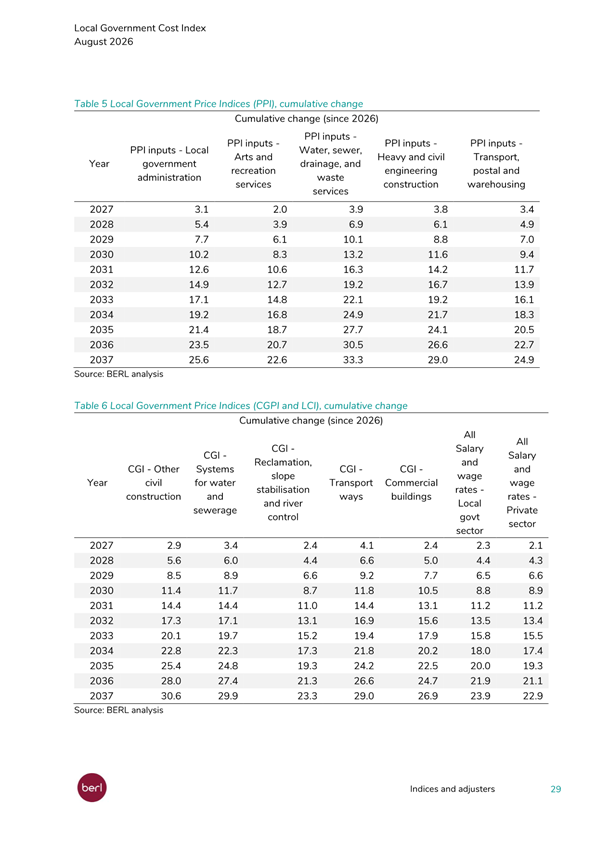
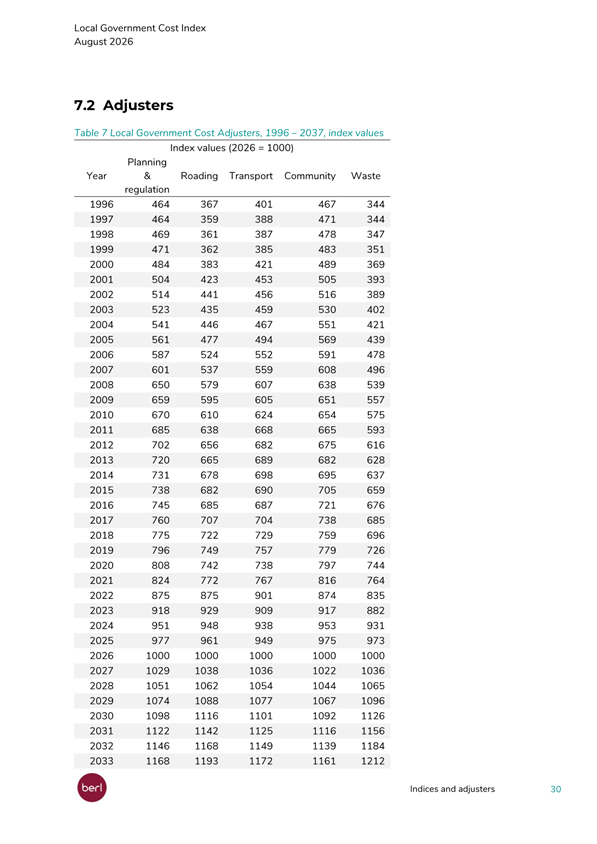
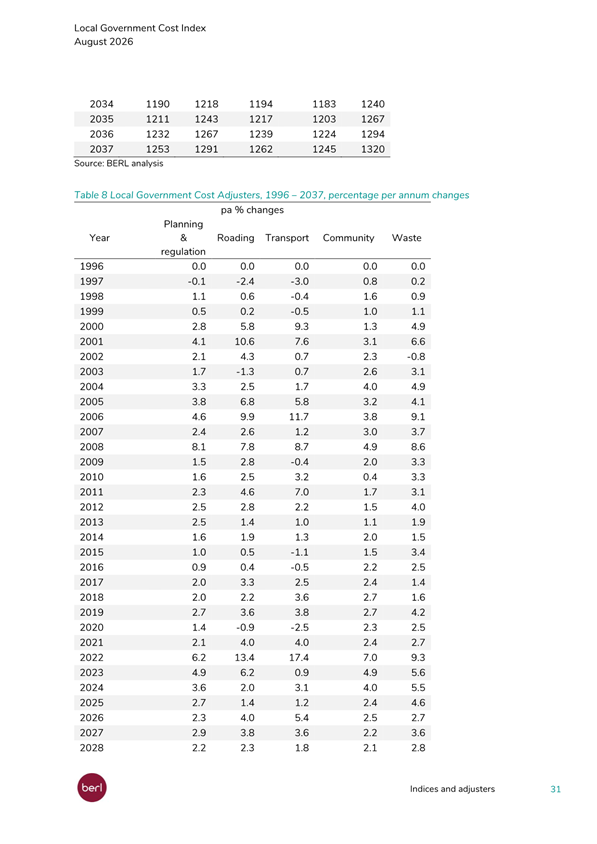
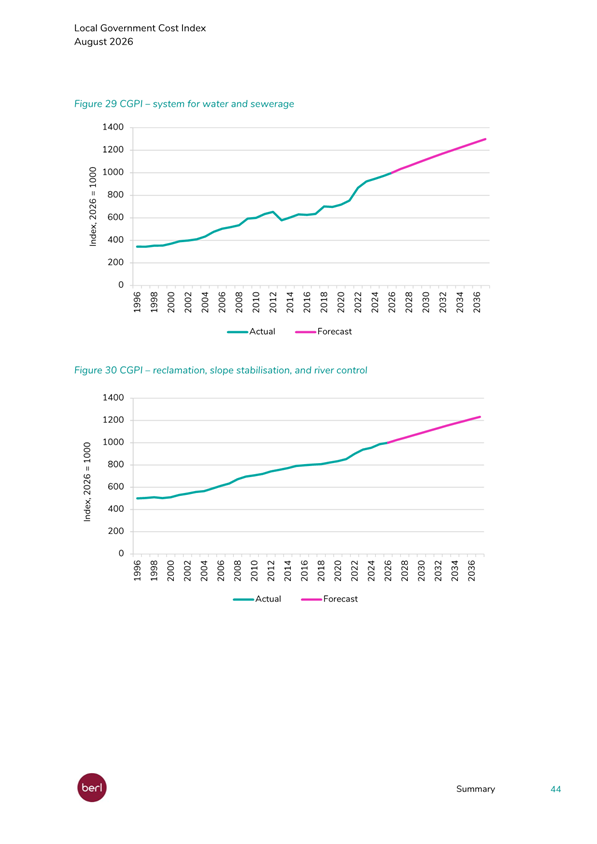
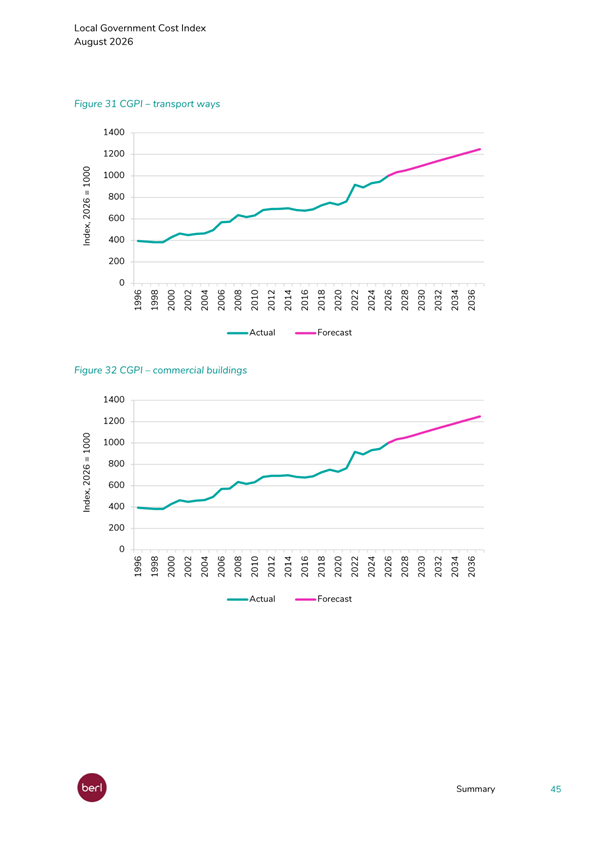
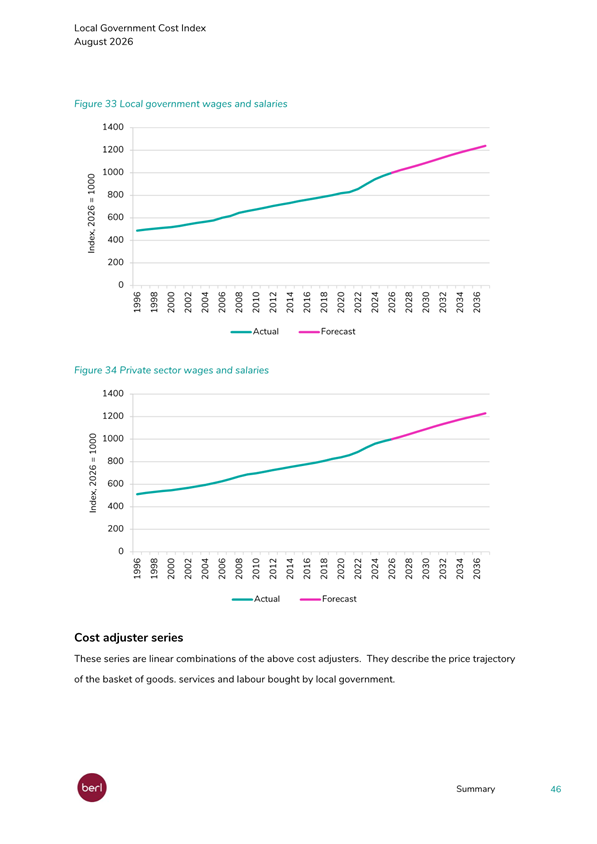
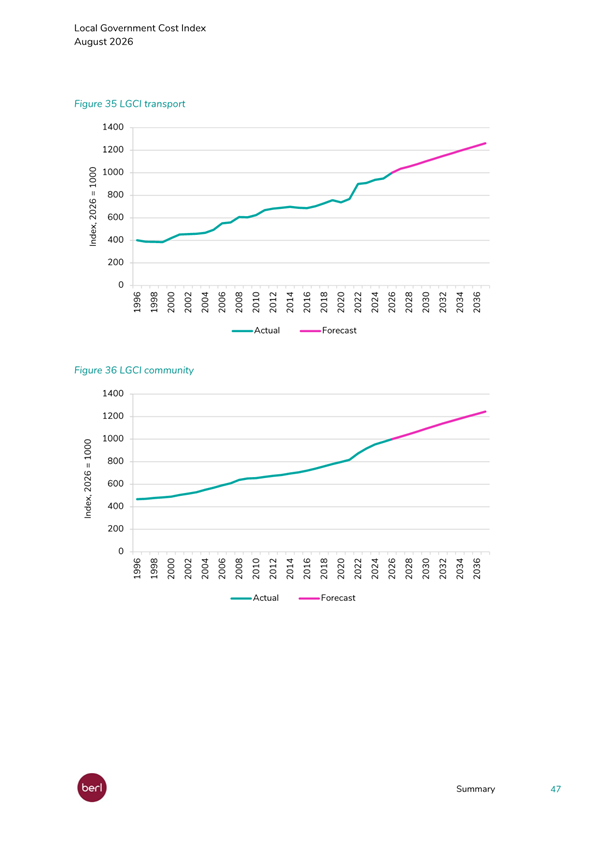
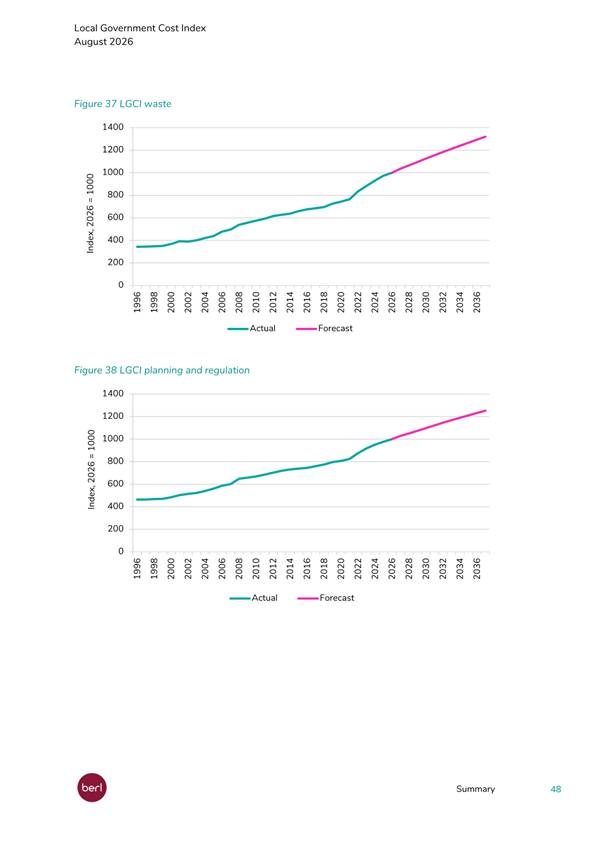
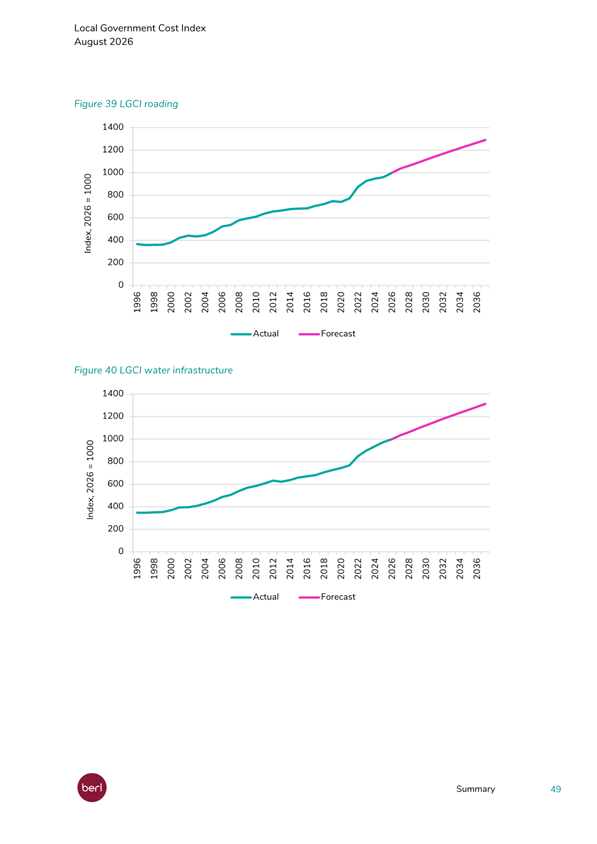
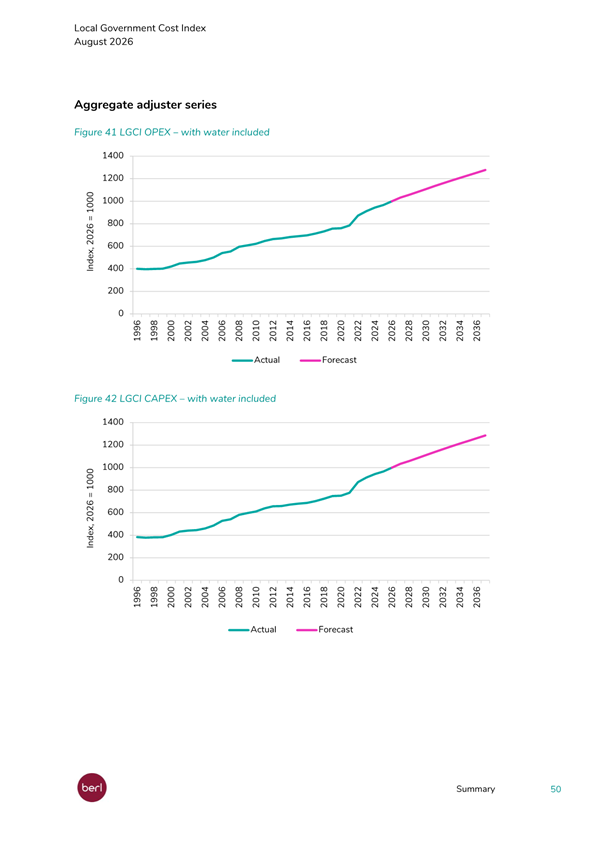
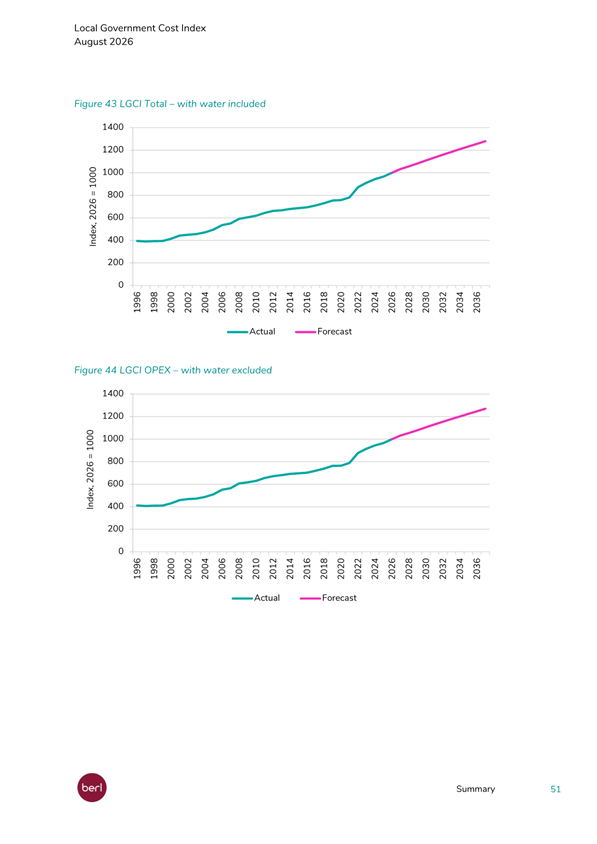
Treasury Limited (DCTL), and BERL has provided interim inflation rates
(Attachment B).
20 It is
assumed that the applicable standard funding assistance rate will be 51%
throughout the 10 year period.
21 The table
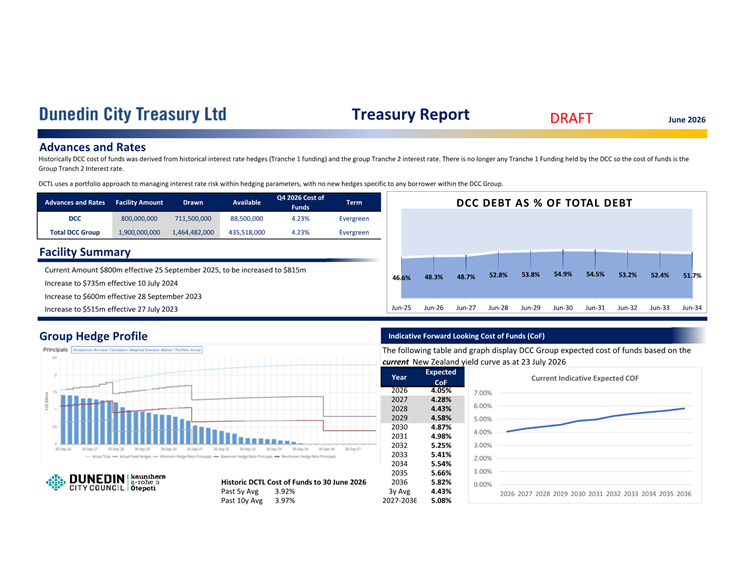
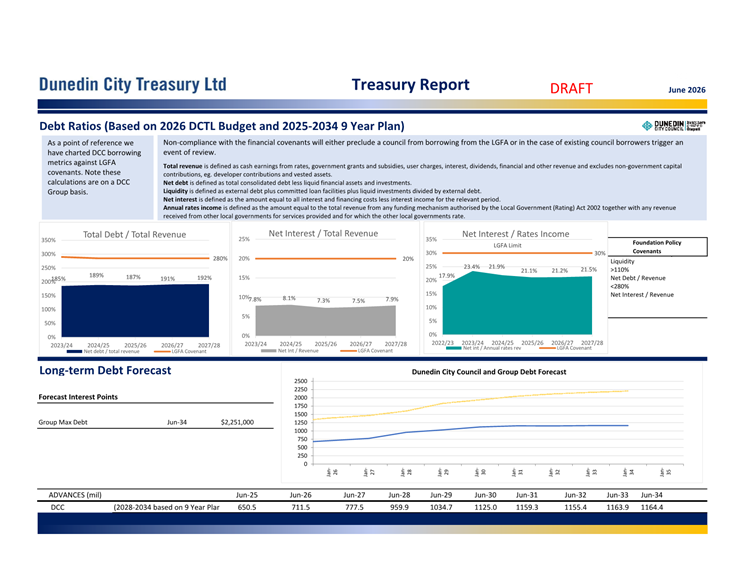
below presents the interest rate assumptions from the June 2026 Treasury Report
provided by DCTL. The full report is available at Attachment C. These
assumptions will be used in developing the financial forecasts for the 10 Year
Plan and the Water Services Strategy.
|
Financial Year
|
Expected Interest Rate
|
|
2027/28
|
4.43%
|
|
2028/29
|
4.58%
|
|
2029/30
|
4.87%
|
|
2030/31
|
4.98%
|
|
2031/32
|
5.25%
|
|
2032/33
|
5.41%
|
|
2033/34
|
5.54%
|
|
2034/35
|
5.66%
|
|
2035/36
|
5.82%
|
|
2036/37
|
*
|
22 Note that
the assumption for 2036/37 (i.e., year 10) has not yet been forecast by DCTL.
The interest rate for this year will be assumed as 5.82% until an updated
forecast is available later in 2026.
OPTIONS
23 The LGA
requires that Council’s 10 Year Plan and Water Services Strategy rely on significant
forecasting assumptions. Options have not been presented but Council may decide
to modify the significant forecasting assumptions.
NEXT STEPS
24 Staff will
use the agreed interim SFAs for the development of the 10 Year Plan and Water
Services Strategy.
25 The
Significant Forecasting Assumptions will be reviewed in late 2026 when updated
information is expected to become available, and again in early 2027. This will
help to ensure that the 10 Year Plan and Water Services Strategy are developed
using the best available information.
26 Staff will
periodically bring updates to the Council as forecasting information becomes
available or changes.
Signatories
|
Author:
|
Rula Abu-Safieh Talahma - Senior Policy Analyst
Janet Fraser - Corporate Planner
|
|
Authoriser:
|
Carolyn Allan - Chief Financial Officer
|
Attachments
|
|
Title
|
Page
|
|
⇩a
|
Draft interim
Significant Forecasting Assumptions - 10 Year Plan and Water Services
Strategy 2027-37
|
153
|
|
⇩b
|
Draft DCTL Treasury
Report - June 2026
|
171
|
|
⇩c
|
BERL interim cost
adjustors
|
173
|
|
SUMMARY OF CONSIDERATIONS
|
|
Fit with purpose of Local Government
This decision enables democratic local
decision making and action by, and on behalf of communities, and promotes the
social, economic, environmental and cultural wellbeing of the Dunedin
communities in the present and for the future.
|
|
Fit with strategic framework
|
|
Contributes
|
Detracts
|
Not applicable
|
|
Social Wellbeing Strategy
|
✔
|
☐
|
☐
|
|
Economic Development Strategy
|
✔
|
☐
|
☐
|
|
Environment Strategy
|
✔
|
☐
|
☐
|
|
Arts and Culture Strategy
|
✔
|
☐
|
☐
|
|
3 Waters Strategy
|
✔
|
☐
|
☐
|
|
Future Development Strategy
|
✔
|
☐
|
☐
|
|
Integrated Transport Strategy
|
✔
|
☐
|
☐
|
|
Parks and Recreation Strategy
|
✔
|
☐
|
☐
|
|
Other strategic projects/policies/plans
|
✔
|
☐
|
☐
|
The 10 Year Plan contributes to all of the objectives and
priorities of the strategic framework as it describes the Council’s
activities, the community outcomes, and provides a long term focus for
decision making and coordination of the Council’s resources, as well as
a basis for community accountability.
|
|
Māori Impact Statement
Council budgets impact broadly across all Dunedin
communities including Māori. The adoption of Te Taki Haruru –
Māori Strategic Framework signals Council’s commitment to mana
whenua and to its obligations under the Treaty of Waitangi. Mana whenua and
mātāwaka will have an opportunity to engage in the 10 Year Plan
2027-37 consultation process.
|
|
Sustainability
Sustainability is an underlying principle of the
DCC’s strategic framework. Significant forecasting assumptions support
sustainability through ensuring that the 10 Year Plan 2027-37 is developed
with the best available information about what the Council and the community
can expect in the future.
|
|
LTP/Annual Plan / Financial Strategy /Infrastructure
Strategy
This report provides details of the assumptions being made
to assist the development of the 10 Year Plan.
|
|
Financial considerations
Financial forecasting assumptions are outlined in the
report and its attachment.
|
|
Significance
The 10 Year Plan is significant and will be consulted on
using the Special Consultative Procedure.
|
|
Engagement – external
There has been no external engagement in the preparation
of the draft interim assumptions. However, information from BERL and DCTL has
been used to inform some of the assumptions.
|
|
Engagement - internal
Relevant staff from across Council have been involved in
the development of the draft interim assumptions.
|
|
Risks: Legal / Health and Safety etc.
The level of uncertainty for each of the assumptions made,
and the effect of the uncertainty is included in the report.
|
|
Conflict of Interest
There are no known conflicts of interest.
|
|
Community Boards
This report has no specific implications for Community
Boards. Community Boards will be consulted with as part of the 10 Year Plan
2027-37 process.
|
|
|
Finance and Performance Committee
27 August 2026
|
|
|
Finance and Performance Committee
27 August 2026
|
|
|
Finance and Performance Committee
27 August 2026
|
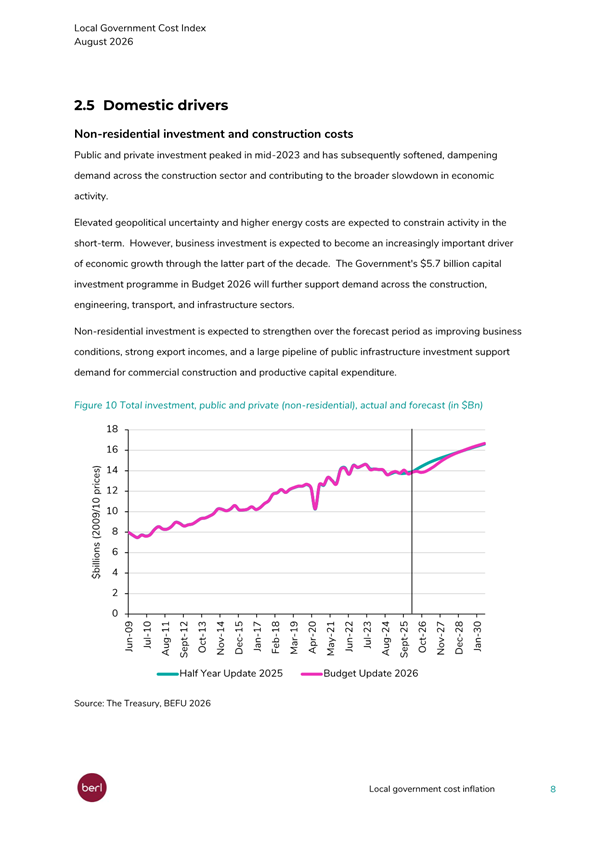
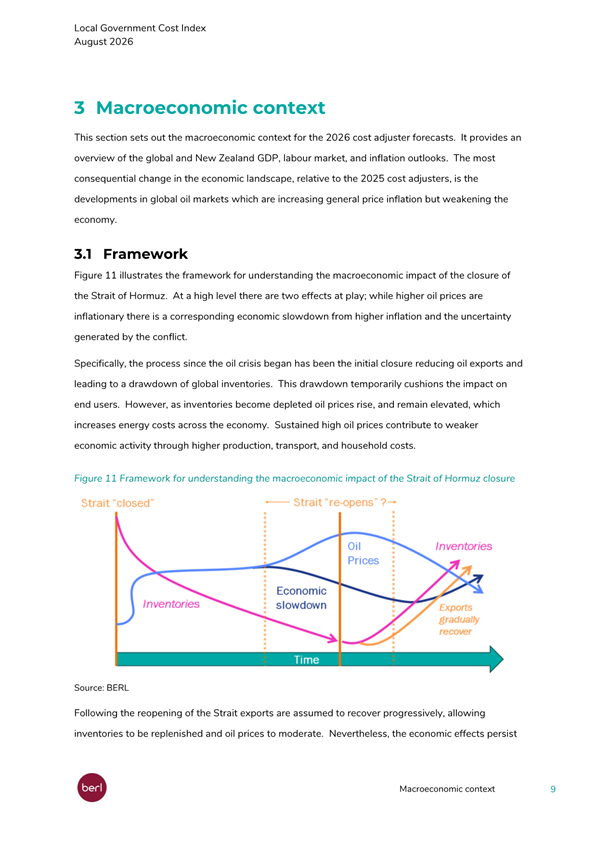
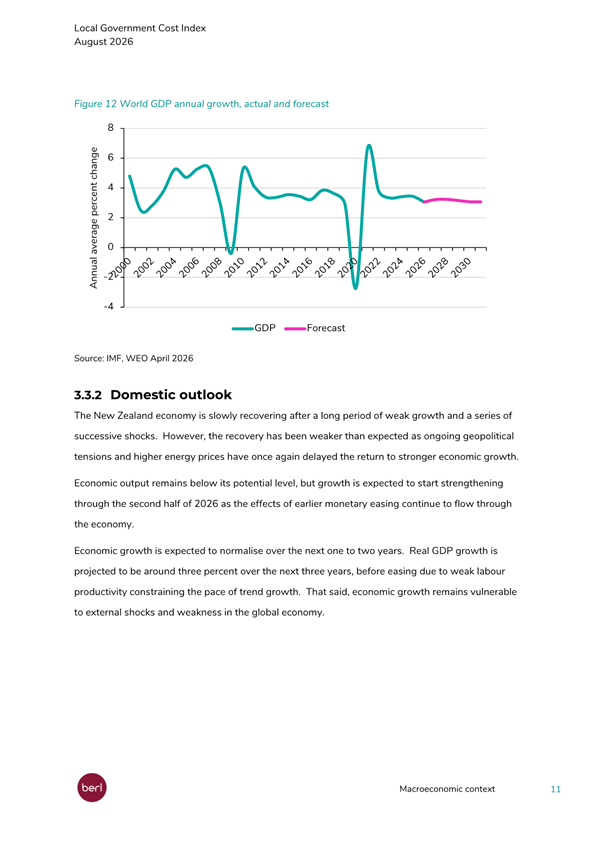
|
|
Finance and Performance Committee
27 August 2026
|
Rating method and financial policies review - 10 Year Plan
2027-37
Department: Civic, Finance and Corporate Policy
EXECUTIVE SUMMARY
1 This
report seeks the Committee’s direction on a range of matters following a
Rating and Financial Policy Review workshop on 15 July 2026.
2 The
review provides an opportunity to assess whether existing rating and financial
policies remain appropriate, equitable, transparent, and aligned with Council's
strategic objectives.
3 Through
the recent workshop, several areas were identified that the Committee may wish
staff to investigate further. Direction is sought on which matters should
proceed to detailed investigation and option development as part of the 10 Year
Plan 2027-37 (10 Year Plan).
RECOMMENDATIONS
That the Committee:
a) Notes the Rating and Financial Policy Review report.
b) Provides direction on
which matter(s) should be investigated further and reported back to Council for
consideration, which may include those listed below and/or any other matter(s)
raised by the Committee:
i) Rating treatment of Forsyth Barr Stadium.
ii) Funding and rating treatment of the Tertiary Area.
iii) Rating options for heritage buildings.
iv) Rating options for vacant buildings and/or abandoned land.
v) Development of affordability measures for inclusion in the
Financial Strategy of the 10 Year Plan 2027-37.
vi) Review of rates remission and postponement policy.
c) Notes that the Revenue
and Financing Policy will be reviewed as part of the development of the 10 Year
Plan 2027-37.
BACKGROUND
Rating
4 The
purpose of the Local Government (Rating) Act 2002 (Rating Act) is to provide
local authorities with the legal framework to set, assess, collect, and recover
rates to fund local government activities. The Act also aims to ensure that
rating decisions are made transparently and through appropriate consultation
processes, and that ratepayers can understand how their rates have been
determined.
5 Under
the Rating Act, councils are required to:
a) Set
and assess rates in accordance with the rating powers and methodologies
specified in the Act.
b) Ensure
rates are set through transparent decision-making processes that align with the
requirements of the Local Government Act 2002.
c) Maintain
a Rating Information Database and rates records for all rating units within
their district.
d) Issue rates
assessments and invoices that accurately reflect a ratepayer's liability.
e) Apply rates
consistently and in accordance with statutory provisions relating to rateable
and non-rateable land.
f) Adopt
policies for the remission and postponement of rates where required by
legislation.
g) Comply
with specific legislative requirements relating to certain land uses, including
educational establishments, Māori freehold land, and other categories of
land addressed by the Act.
6 Properties
that are ‘non-rateable’ under the Act are exempt from general rates
but are still liable for water supply, refuse disposal or sewage disposal
targeted rates, where applicable. Examples of non-rateable properties include
schools and universities, public hospitals and churches.
7 Dunedin
City Council (DCC) currently charges general and targeted rates to ratepayers.
a) General
rates are based on a property’s capital value (CV) and apply to all
rateable properties. DCC currently has seven general rate differential
categories based on land use:
i) Residential
ii) Lifestyle
iii) Commercial
iv) Farmland
v) Residential
Heritage B&B
vi) Water Services
Utilities
vii) Stadium: 10,000+ Seat
Capacity
b) Targeted
rates are charged to identifiable groups of ratepayers to fund particular
services or activities.
8 The
Rating Act provides the ability for councils to charge Uniform Annual General
Charges (UAGC); this is a fixed, flat fee on every rateable property,
regardless of CV. DCC does not currently charge a UAGC.
9 At
its meeting on 4 March 2026, Council considered items relating to the draft
Annual Plan 2026/27, including the rating method and the addition of a new
general rate differential for water services utilities. Council resolved:
Moved (Cr
Cherry Lucas/Mayor Sophie Barker):
That the
Council:
a) Approves
an increase in the Community Services targeted rate for the 2026/27 year of
$3.30, taking the rate to $124.30 including GST.
b) Approves
an increase in the Stadium 10,000 plus seat differentiated rates for the
2026/27 year based on the June 2025 Local Government Cost Index of 2.7%.
c) Approves
the creation of a new general rate differential for water services utilities of
1.34
d) Approves
the current rating method for the setting of all other rates for the 2026/27
year.
e) Notes
that a full review of the general rate differential will be completed as part
of the 10 Year Plan 2027-37.
Motion carried (CNL/2026/062)
10 The Annual
Plan 2026/27 rating method is at Attachment A.
11 Other changes
previously made to the way DCC rates include:
a) Reduction
in the general rate differential factor for commercial properties from 3.09 to
2.5 (completed in 2015/16);
b) Reduction
in the general rate differential factor for farmland from 0.9 to 0.8 (completed
in 2015/16); and
c) Increase
in the general rate differential factor for commercial properties in Strath
Taieri from 1.0 to 2.5 (completed in 2017/18).
Financial Policies
12 Under the
Local Government Act (LGA), DCC is required to include a Revenue and Financing
Policy in its 10 Year Plan 2027-37.
13 The current
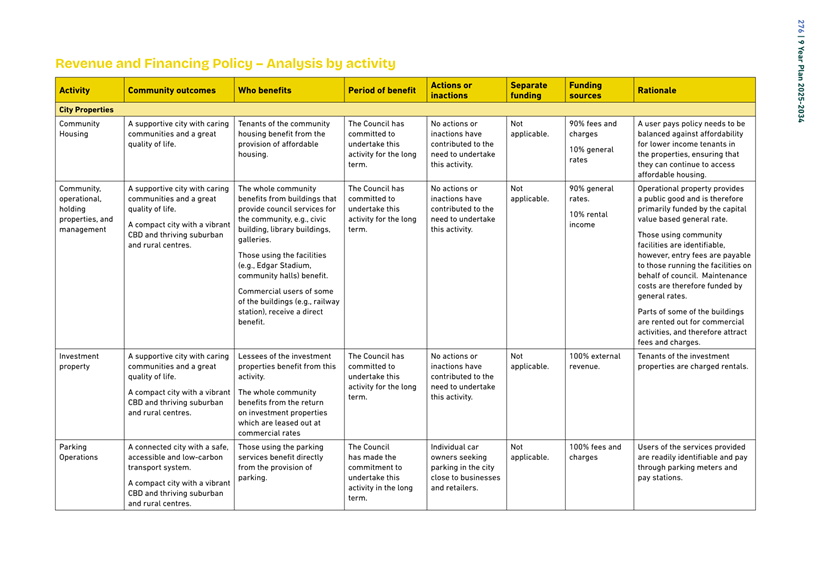
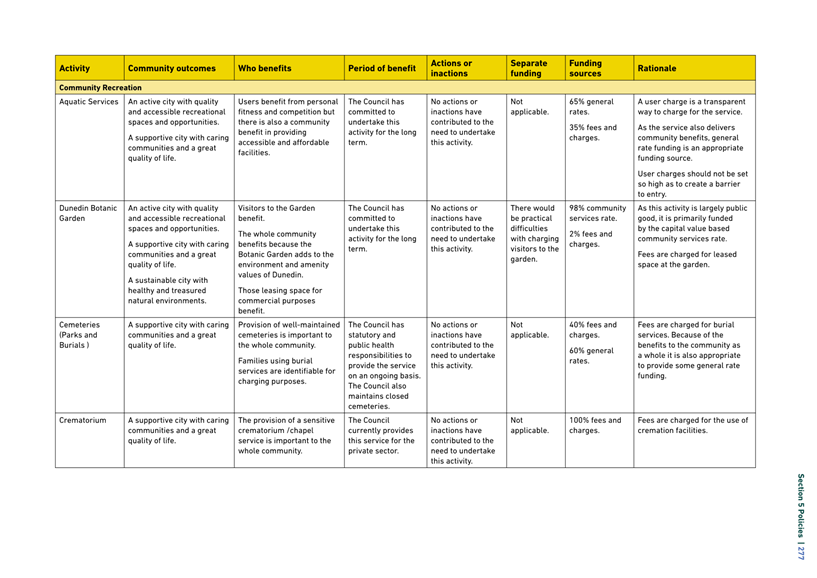
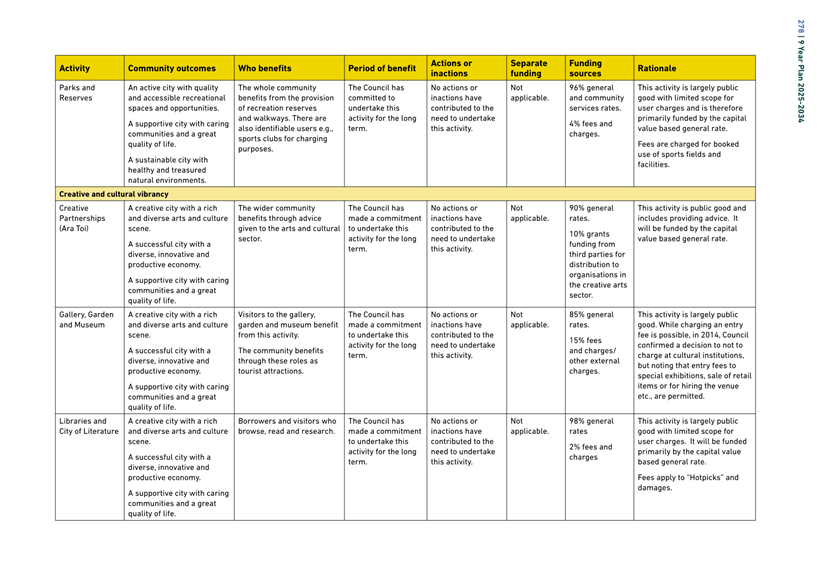
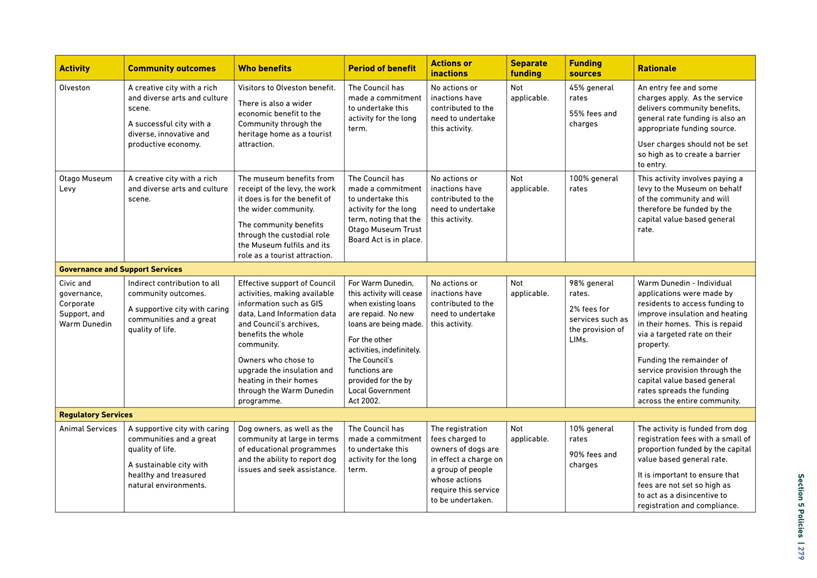
Revenue and Financing Policy, which is part of the 9 Year Plan 2025-34, is at
Attachment B.
14 The Revenue
and Financing Policy must state funding sources of operating and capital
expenditure, including but not limited to general and targeted rates, fees and
charges, borrowing, proceeds from asset sales and development contributions.
15 The policy
identifies the proportion of expected funding from rates and other sources for
each of the main activities of DCC, with an acceptable variance of +/- 5%.
16 DCC has
included a Rates Remission and Postponement Policy in previous Long Term Plans.
The current Policy, which is part of the 9 Year Plan 2025-34, is at Attachment
C.
17 A Rates
Remission and Postponement Policy is not strictly required under the
legislation; however, the Rating Act requires a policy covering remission and
postponement of rates on Māori freehold land at a minimum.
18 DCC’s
current Rates Remission and Postponement Policy covers instances where DCC may
remit or postpone rates, including situations relating to hardship, natural
disasters and Māori freehold land.
DISCUSSION
19 The Rating
and Financial Policy Review provides an opportunity to consider whether current
funding arrangements remain fair, transparent, and fit for purpose.
20 Affordability
of rates has been a topic of increased focus and discussion in recent years,
including from central government and the community. This has been driven at
least in part by cost of living pressures, recent rate increases around the
country and historical underinvestment in infrastructure, with efforts now
being made to correct this.
21 Related to
affordability, central government is proposing a rate cap for local government;
legislation relating to this proposal has not yet been introduced at the time
of writing this report. Regardless of the outcome of this proposal,
affordability to ratepayers remains a consideration.
22 Changes to
the way that DCC rates does not change the amount of rates revenue received;
instead, it changes the allocation of the rates burden across ratepayers.
23 Initial
review work has identified several topics that may warrant further
investigation. The Committee is asked to decide which matters should be
investigated further and reported back with options for consideration.
24 Any future
policy changes would be subject to Council decision-making processes and, where
required, consultation through the 10 Year Plan 2027-37 process.
25 Some
queries from the workshop have been addressed in other ways and consequently
are not included in the options for further work in this report:
a) University
Halls of Residence
The Local Government (Rating)
Act 2002 prescribes how properties used for educational purposes are to be
rated, this includes the Halls of Residence. As a result, councils have limited
discretion in determining how rates are assessed and charged for these
properties.
A breakdown of the current rates
on University of Otago properties is at Attachment D.
b) Rates
Rebates
Rates rebates are provided
through a central government scheme that is administered by local authorities.
The scheme provides partial payment for eligible ratepayers with low incomes
and/or with a Super Gold card. Attachment E shows the numbers of rates rebates
that were provided during the 2025/26 rating year by local authority. A
comparison has been made against the total number of dwellings per area from
the 2023 census data.
The DCC has increased the
advertising of the rates rebates scheme and provided an online application form
to encourage more applications.
c) Rates
Arrears for 2025/26
As at 30 June 2026, there was a
total of 2,588 residential properties that were in rates arrears to a total of
$5,425,995. Of that total, 1,492 properties have arrears exceeding $500. Properties
that have a mortgage will enter into a 90-day bank warning process. During this
process, staff offer support to enter affected ratepayers into a payment plan.
d) Water Services
Rates
A review of how the DCC rates
for water services is commencing soon. This is a significant piece of work and
is expected to be ready for the Council’s consideration at the time of
the Annual Plan 2028/29.
OPTIONS
26 Following
the workshop held in July, direction is sought on the following matters. For
areas where the Committee gives direction to continue work, options will be
presented for consideration at a later date as a part of the current 10 year
plan process.
Rating treatment of Forsyth Barr Stadium
27 Forsyth
Barr Stadium is rated under a specific differential for both general and
targeted rates. For the 2026/27 rating year, rates revenue from the Stadium
equates to approximately $219,648.
28 The
creation of the differential was a historical decision by Council to collect a
quantum of rates based on an estimate of the rates collected on the stadium
site prior to development.
29 It has been
suggested that the rating treatment of the Stadium is not easily understood and
that DCC could provide greater transparency on the cost to ratepayers. There
are different options that could be explored to achieve this.
30 The
Finance and Performance Committee is asked to provide direction on whether
options should be investigated to provide greater transparency with regard to
Forsyth Barr Stadium.
Funding and rating treatment of the Tertiary Area
31 The
properties in the ‘Tertiary Area’ (Attachment F) have access to an
enhanced kerbside service.
32 This
kerbside service is for a weekly collection of all bins (green, red, yellow,
and blue), as opposed to the standard residential collection of a weekly green
bin service and alternating fortnightly collections of the red, yellow, and
blue bin.
33 Currently
the cost for all residential kerbside collection services (both enhanced and
standard) is equally spread through the residential kerbside targeted rate. For
the 2026/27 rating year, this is $349.20 per rating unit.
34 There are
two options that could be taken on this matter:
a) Investigate
implementing two different targeted rates based on the level of service
provided, or
b) Keep the
status quo of one targeted rate.
35 The
Finance and Performance Committee is asked to provide direction on which
option(s) require further investigation, if any.
36 In addition
to kerbside collection, there are other costs incurred in the Tertiary Area,
which are paid for by ratepayers. Examples include repairing damage to roads
and street sweeping to manage higher levels of litter and debris. There are a
number of options that could be taken on this matter:
a) Investigate
implementing a special rating area for the Tertiary Area;
b) Investigate
fees and charges to recover the costs incurred; or
c) Keep
the status quo.
37 The
Finance and Performance Committee is asked to provide direction on which
option(s) require further investigation, if any.
Rating options for Heritage Buildings
38 The 2GP
District Plan identifies the following (collectively referred to as
‘protected heritage buildings’):
a) 915
Scheduled Heritage Buildings
b) 902
Character Contributing Buildings in heritage precincts
c) 50
Heritage Structures (mostly non-habitable)
39 The DCC
adopted the Heritage
Action Plan (HAP) in November 2023 and noted the associated HAP
Implementation Plan (HIP). The primary outcome of the HAP is to encourage
investment in heritage buildings.
40 The DCC
currently administers the Dunedin Heritage Fund which distributes an annual
grant from the Council of $680,700. This fund supports the redevelopment,
restoration, and strengthening of heritage buildings with a focus on supporting
positive conservation outcomes.
41 If further
support mechanisms are to be explored, there are a few rating-related options
that may be considered. However, further investigation would need to be carried
out to understand the viability of each option. High-level options identified
are:
a) Discouraging
vacant/derelict heritage buildings by implementing a higher general rate
differential on those buildings. This would be a similar approach to Wellington
City Council;
b) Encouraging
the redevelopment of heritage buildings by delaying/postponing the rates
increase that occurs after an increase in capital value from redevelopment;
and/or
c) Providing
rates relief for protected heritage places by implementing a new, lower general
rate differential.
42 The
Finance and Performance Committee is asked to provide direction on which
option(s) require further investigation, if any.
Rating options for vacant buildings and/or abandoned
land.
43 If the
Committee wished to explore a different rating treatment for vacant buildings,
this would require investigation as to possible mechanisms, including how other
councils rate. Any options are likely to apply to a specific geographic area,
or to a type of building, for simplicity of administration.
44 The
Finance and Performance Committee is asked to provide direction for
investigating a vacant building rating treatment, and if so, are there any
specific criteria to be explored.
Abandoned land remission policy
45 Following
the July workshop, it was identified that an Abandoned Land Remission Policy
could provide greater transparency with regards to uncollected rates revenue
from abandoned land.
46 Initial
investigations have identified 86 rateable assessments that are general
freehold land that are believed to be abandoned, equating to an outstanding
rates balance of $212,579.21.
47 Some of the
rateable assessments are of sufficient size to warrant exploring whether they
are declared legally abandoned. However, some are small parcels of land that
have had outstanding rates written off.
48 One option
is to consider adopting an ‘abandoned land’ remission as a part of
the Rates Remission and Postponement Policy and recognising the cumulative
written off rates in a budget line. This is a mechanism used by some other
councils.
49 The
Finance and Performance Committee is asked to provide direction on implementing
an abandoned land remission policy, if any.
Affordability measures for inclusion in the Financial
Strategy
50 The
statutory context is that the Financial Strategy is intended to make
transparent the effects of Council proposals on services, rates, debt, and
investments, and to provide a guide for prudent financial management.
51 The
Financial Strategy in the 9 year plan includes a number of financial management
tools. There is an opportunity to include an additional metric relating to
affordability for ratepayers.
52 Major
takeaways from the environmental scan of rates affordability across a number of
councils include:
a) Affordability is
not defined through a single formula. Most councils treated it as a
balancing judgement across rates increases, debt, capital investment, levels of
services, and intergenerational equity.
b) Rates affordability
is the most common lens. Council’s financial strategy considers
affordability for ratepayers and the DCC as a whole.
c) Debt and
balanced-budget settings are used as affordability controls. Debt limits
[net debt to revenue] are not the definition of affordability itself but are
used as an affordability guardrail.
d) Infrastructure
pressures are the main driver of Council affordability concerns.
e) Affordability
involves trade-offs between core infrastructure and levels of service.
Council decides on funding now, deferring, removing low priority projects,
impact on services, and what to defer to future ratepayers.
f) Using direct
affordability relief mechanisms as part of Council’s affordability
response. Rates Rebate Scheme is the most common household affordability
tool. Council’s rates remissions, postponements, rebates, hardship
policies are part of the affordability response.
53 The
Finance and Performance Committee is asked to provide direction on whether an
affordability metric for ratepayers is developed for inclusion in the Financial
Strategy.
Rates Remission and Postponement Policy
54 The Rates
Remission and Postponement Policy will be reviewed and updated as a part of the
10 year plan process. This report seeks direction on the following matters:
a) Rates
Remission for Hardship: whether to review the current criteria and suggest
how the policy could be made more accessible to those experiencing hardship.
b) Natural
Disaster: whether to remove the criteria of ‘Government funds that
rates relief’ to allow the decision to be made by DCC.
c) Unexpected
Events: whether to replace with ‘Other remissions deemed fair and
equitable’ to recognise that not all possible scenarios can be covered,
but allowing some flexibility to apply remissions where it is fair and
equitable to do so.
d) Other
remission areas: as stated earlier in this report, there are options to
consider other areas in the remission policy (e.g., heritage, abandoned land
etc.)
55 The
Finance and Performance Committee is asked to provide direction on which
option(s) require further investigation.
Review of Revenue and Financing Policy
56 The LGA
requires that the Revenue and Financing Policy is reviewed and included as part
of any Long Term Plan.
57 Specific
revenue and funding policies relating to the main activities of Council will
all be reviewed as part of the development of the 10 Year Plan 2027-37. This
review will address changes in context and settings over time.
58 For
example, during the Annual Plan 2026/27 process, Community Housing was
identified as an activity that was non-compliant with the current Revenue and
Financing Policy. As part of the Policy review, staff will do work in this area
before coming back to the Council with options to ensure future compliance.
59 Another
example of where context has changed is in city tourism and visitor numbers,
which were impacted by the Covid-19 pandemic and have since experienced a
period of recovery. This lens will be applied during the review of the policies
for DCC’s cultural attractions and isite Visitor’s Centre.
NEXT STEPS
60 Staff will
incorporate the Committee’s direction into the Rating and Financial
Policy Review work programme.
61 Staff will
review the Revenue and Financing Policy as part of the development of the 10
Year Plan 2027-37, with particular regard to where context and settings have
changed.
62 Detailed
analysis and options papers will be prepared on any matters selected by the
Committee for further investigation.
63 Any
proposed policy changes will be reported back to Council for consideration and,
where required, will form part of future consultation processes associated with
the 10 Year Plan 2027-37.
Signatories
|
Author:
|
Janet Fraser - Corporate Planner
Hayley Knight - Assurance Manager
Rula Abu-Safieh Talahma - Senior Policy Analyst
|
|
Authoriser:
|
Carolyn Allan - Chief Financial Officer
|
Attachments
|
|
Title
|
Page
|
|
⇩a
|
Rating Information -
extract from Annual Plan 2026/27
|
245
|
|
⇩b
|
Revenue and Financing
Policy - extract from 9 Year Plan 2025-34
|
268
|
|
⇩c
|
Rates Remission and
Postponement Policy - extract from 9 Year Plan 2025-34
|
282
|
|
⇩d
|
University of Otago
rates breakdown - July 2026
|
289
|
|
⇩e
|
Rates Rebates by Area
2025/26
|
293
|
|
⇩f
|
Kerbside Tertiary Area
Map
|
295
|
|
SUMMARY OF CONSIDERATIONS
|
|
Fit with purpose of Local Government
This decision enables democratic local
decision making and action by, and on behalf of communities,
and promotes the social, economic,
environmental and cultural wellbeing of communities in the
present and for the future.
|
|
Fit with strategic framework
|
|
Contributes
|
Detracts
|
Not applicable
|
|
Social Wellbeing Strategy
|
✔
|
☐
|
☐
|
|
Economic Development Strategy
|
✔
|
☐
|
☐
|
|
Environment Strategy
|
✔
|
☐
|
☐
|
|
Arts and Culture Strategy
|
✔
|
☐
|
☐
|
|
3 Waters Strategy
|
✔
|
☐
|
☐
|
|
Future Development Strategy
|
✔
|
☐
|
☐
|
|
Integrated Transport Strategy
|
✔
|
☐
|
☐
|
|
Parks and Recreation Strategy
|
✔
|
☐
|
☐
|
|
Other strategic projects/policies/plans
|
✔
|
☐
|
☐
|
Rating and financial policies of the 10 Year Plan 2027-37
contribute to objectives across the strategic framework, as they relate to
all of the Council’s activities, which are aligned to community
outcomes.
|
|
Māori Impact Statement
Council budgets impact broadly across all Dunedin
communities including Māori. The adoption of Te Taki Haruru –
Māori Strategic Framework signals Council’s commitment to mana
whenua and to its obligations under the Treaty of Waitangi. Mana whenua and
mātāwaka will have an opportunity to engage in the 10 Year Plan
2027-37 consultation process.
|
|
Sustainability
Sustainability is an underlying principle of the
DCC’s strategic framework. The Rating and financial policies of the 10
Year Plan 2027-37 support financial sustainability for activities of Council
and for its ratepayers.
|
|
LTP/Annual Plan / Financial Strategy /Infrastructure
Strategy
The rating method, Financial Strategy, Revenue and
Financing Policy, and Rates Remission and Postponement Policy will be
included in the 10 Year Plan 2027-37.
|
|
Financial considerations
The Council may direct staff to do further investigation /
analysis on areas of interest. This analysis, including financial
considerations, will be brought back to Council for consideration and
decision making as part of the 10 Year Plan 2027-37 process.
|
|
Significance
This report is considered to be low significance under
Council’s Significance and Engagement Policy.
|
|
Engagement – external
Any proposed changes to rating or financial policies would
be consulted on using the Special Consultative Procedure as part of the 10
Year Plan 2027-37 process.
|
|
Engagement - internal
Relevant staff from across the organisation would be
involved in any investigation / analysis as directed by the Council.
|
|
Risks: Legal / Health and Safety etc.
There are no identified risks.
|
|
Conflict of Interest
There are no identified conflicts of interest.
|
|
Community Boards
There are no implications for Community Boards.
|
|
|
Finance and Performance Committee
27 August 2026
|
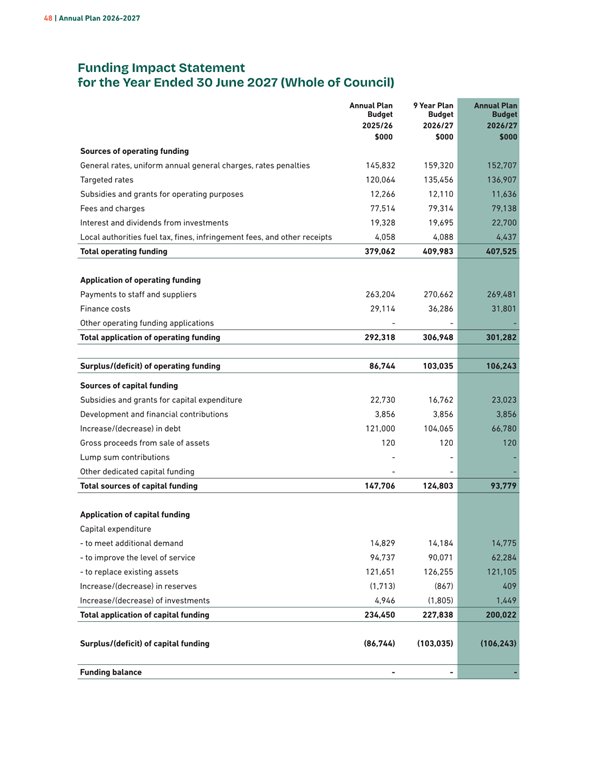
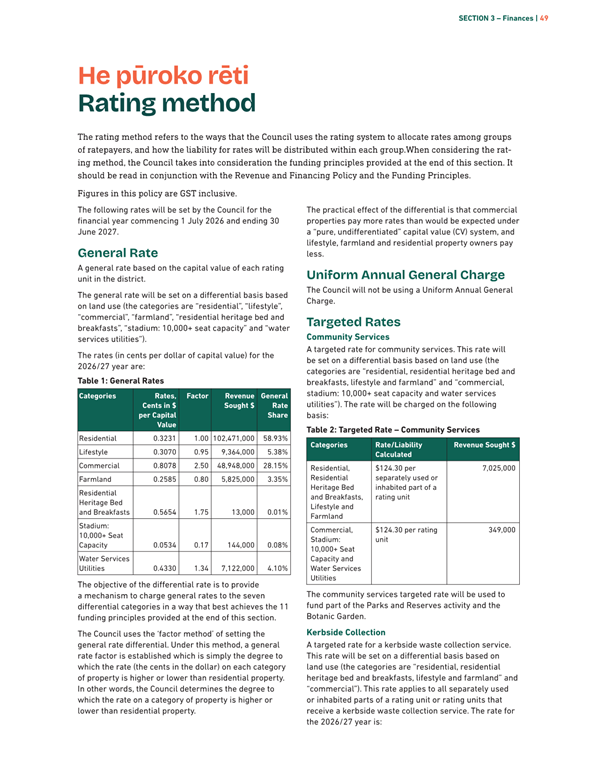
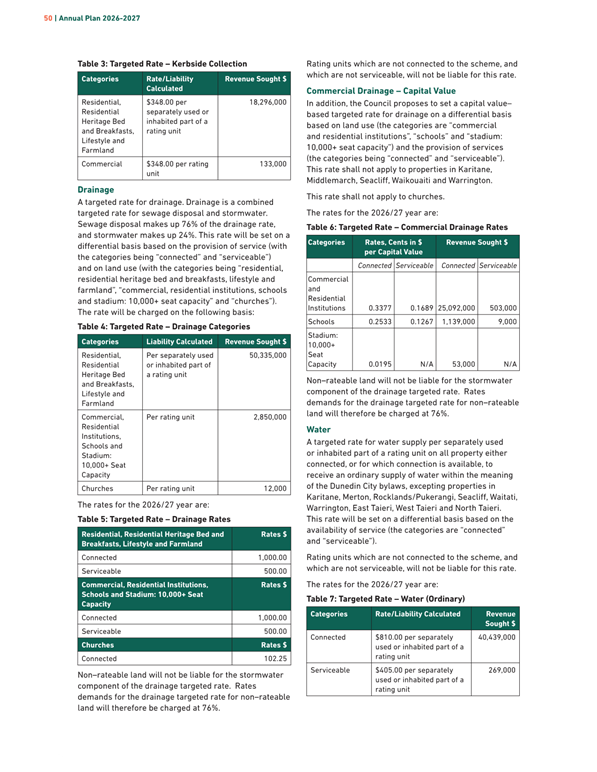
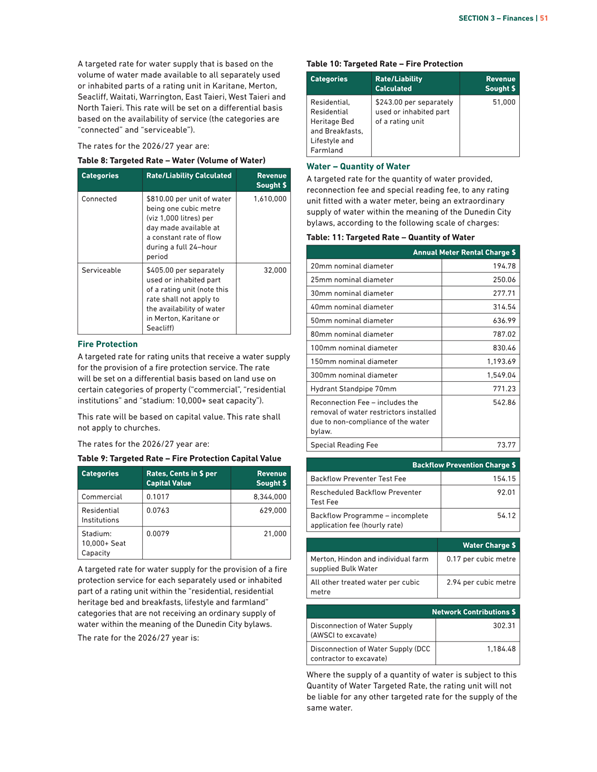
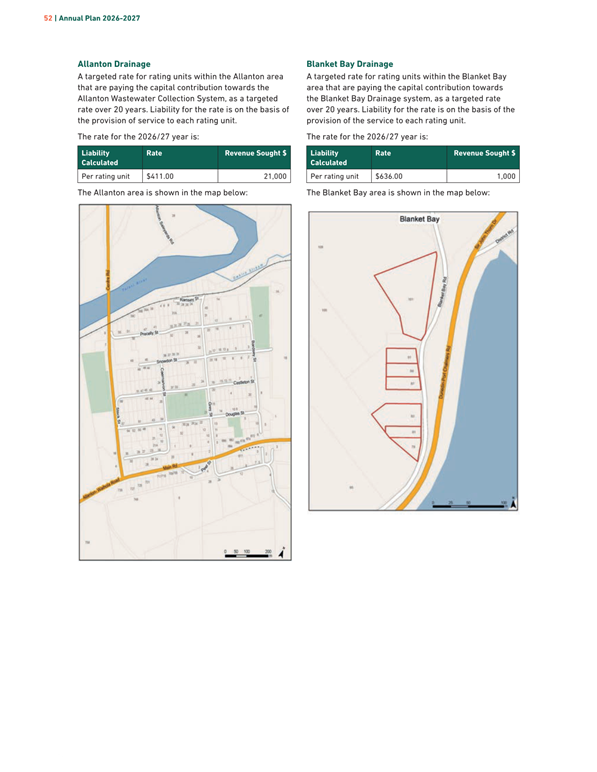
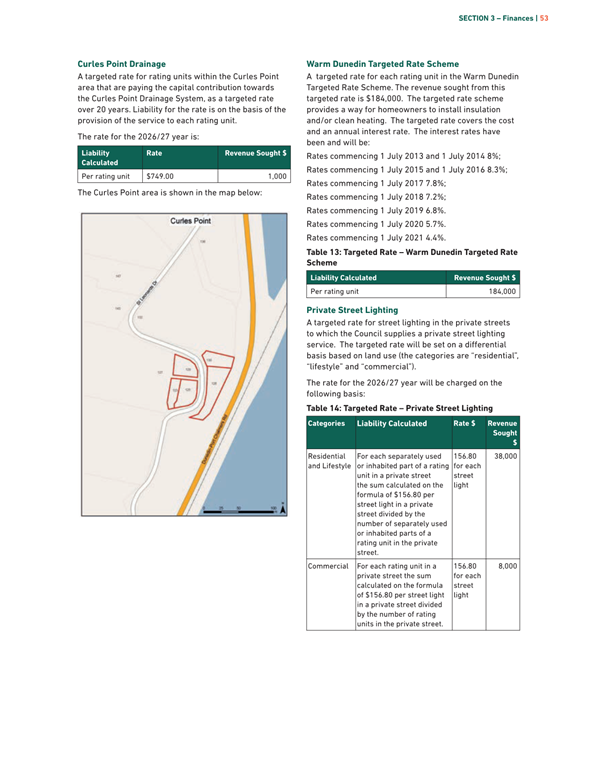
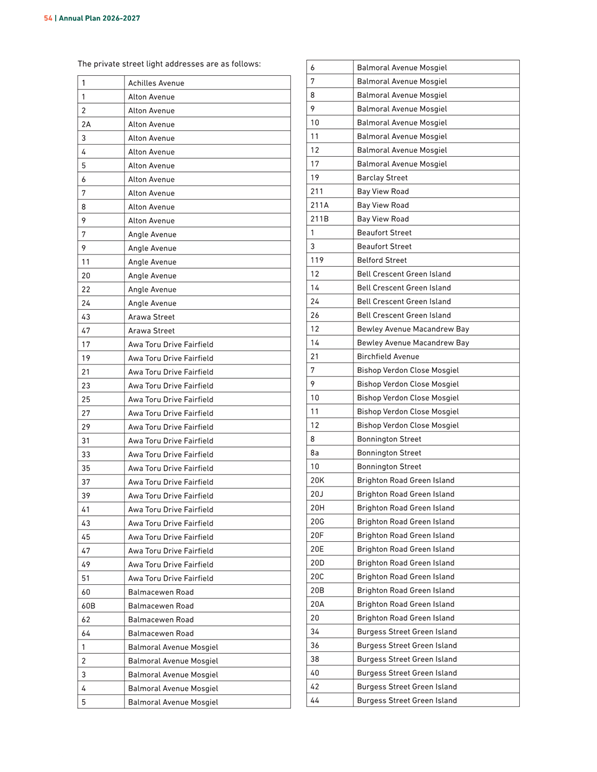
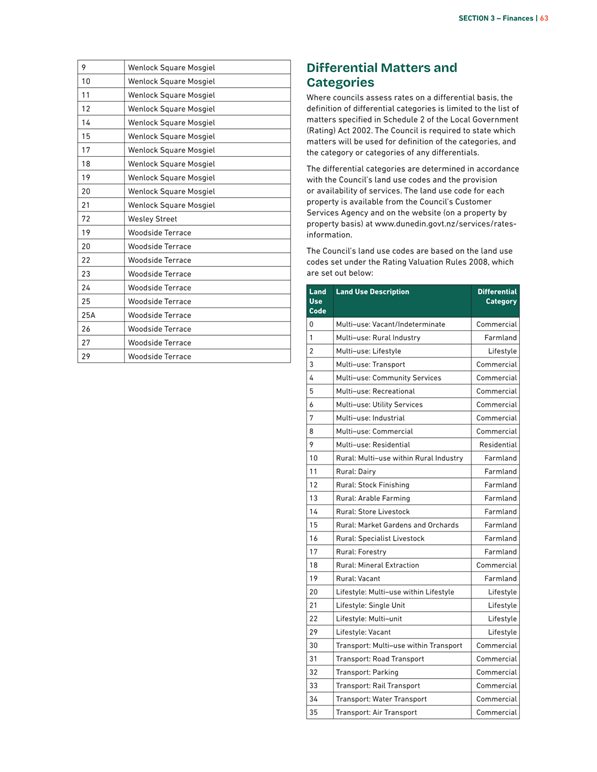
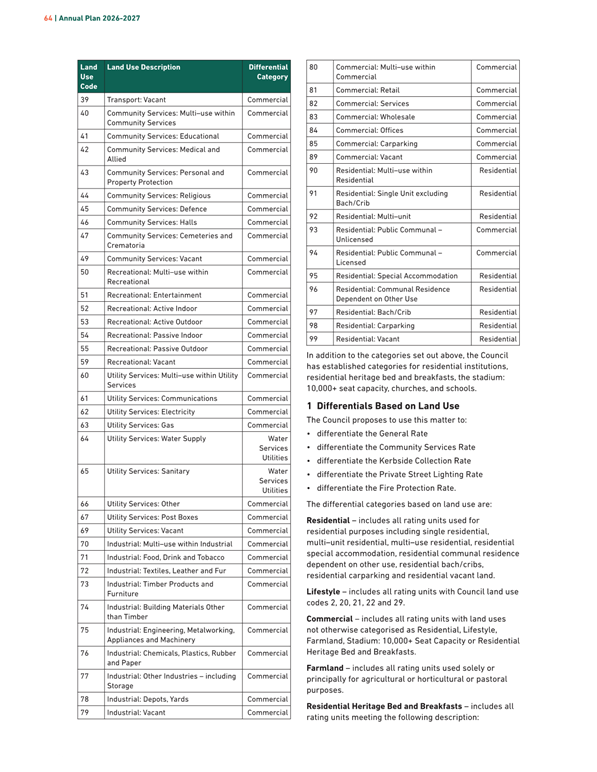
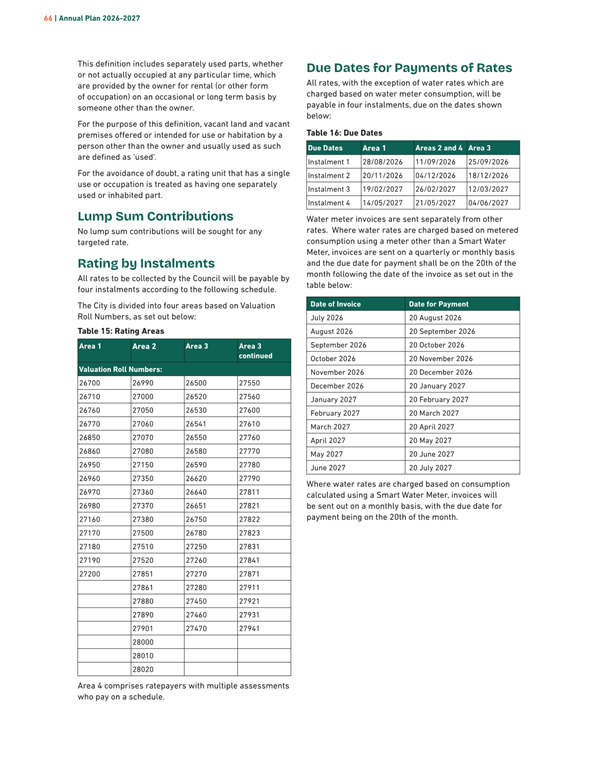
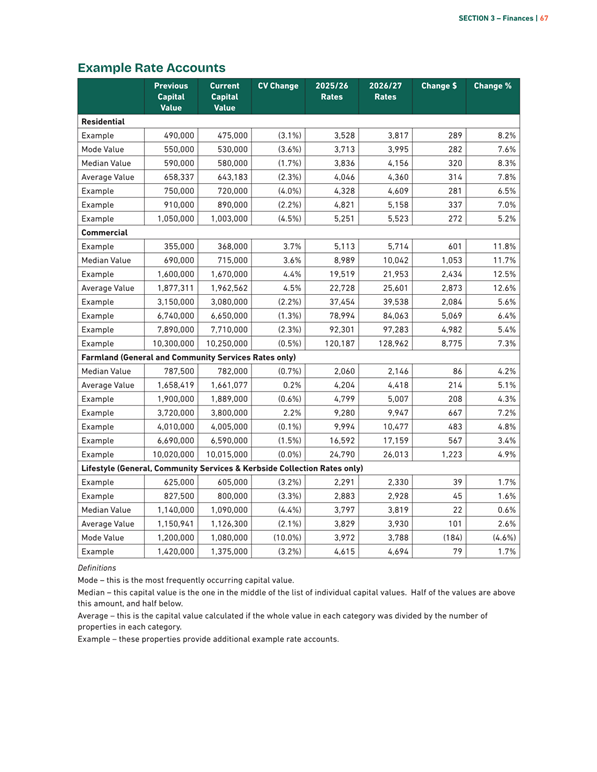
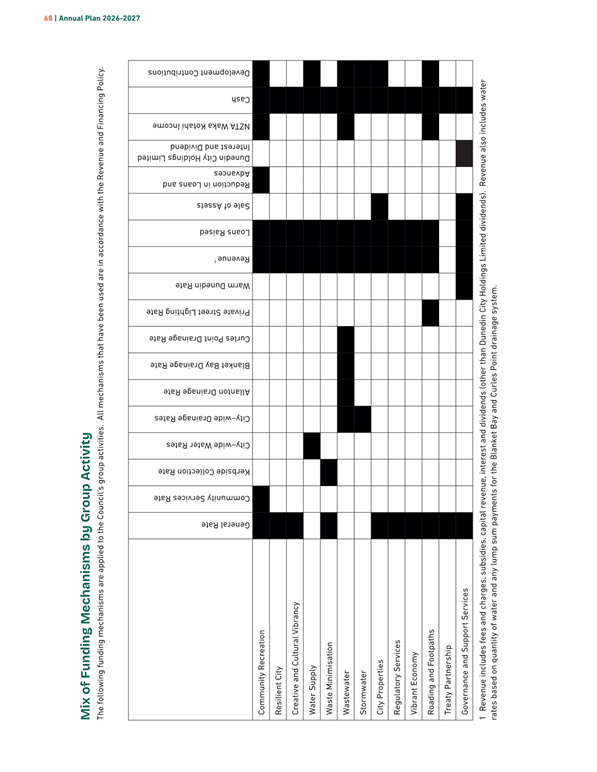
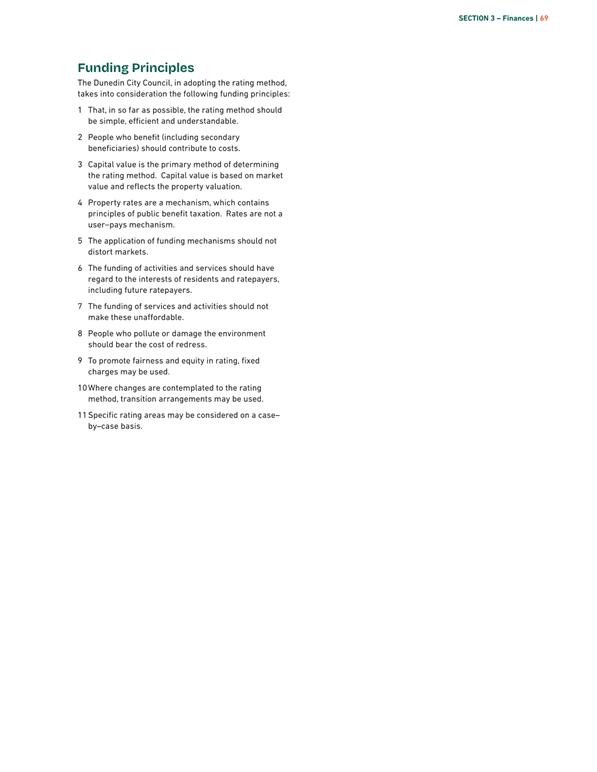
|
|
Finance and Performance Committee
27 August 2026
|
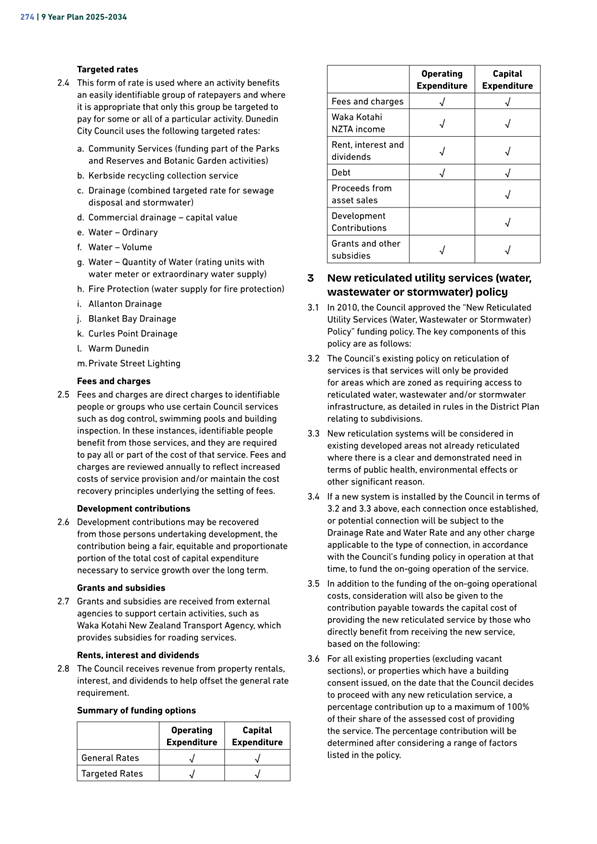
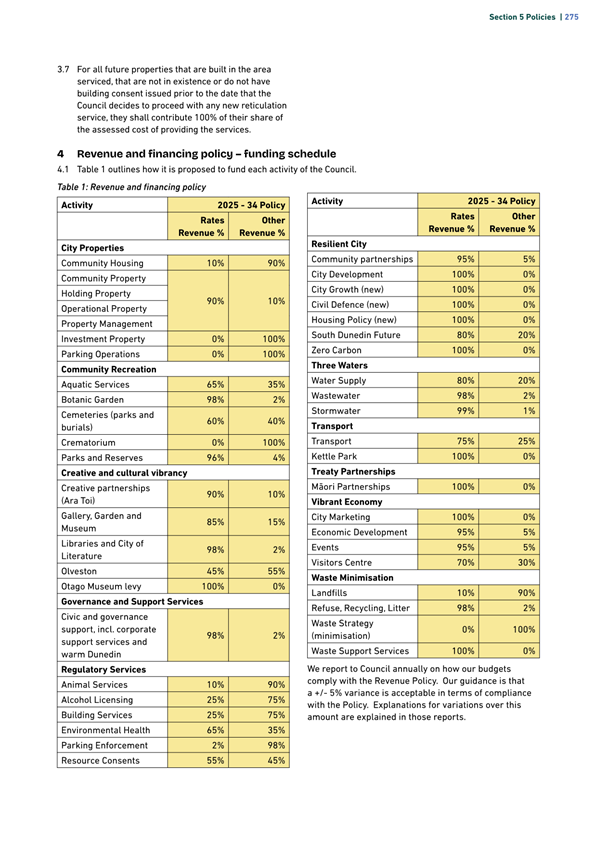
|
|
Finance and Performance Committee
27 August 2026
|
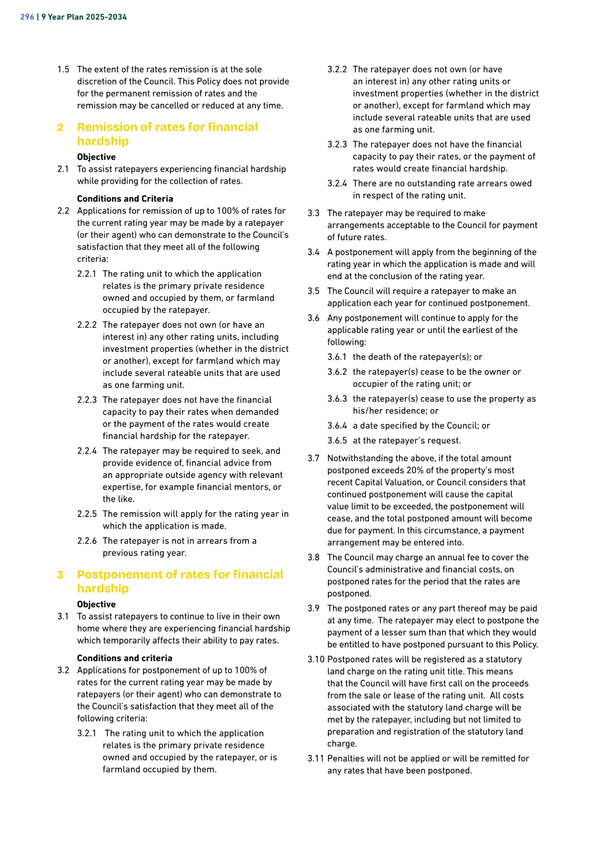
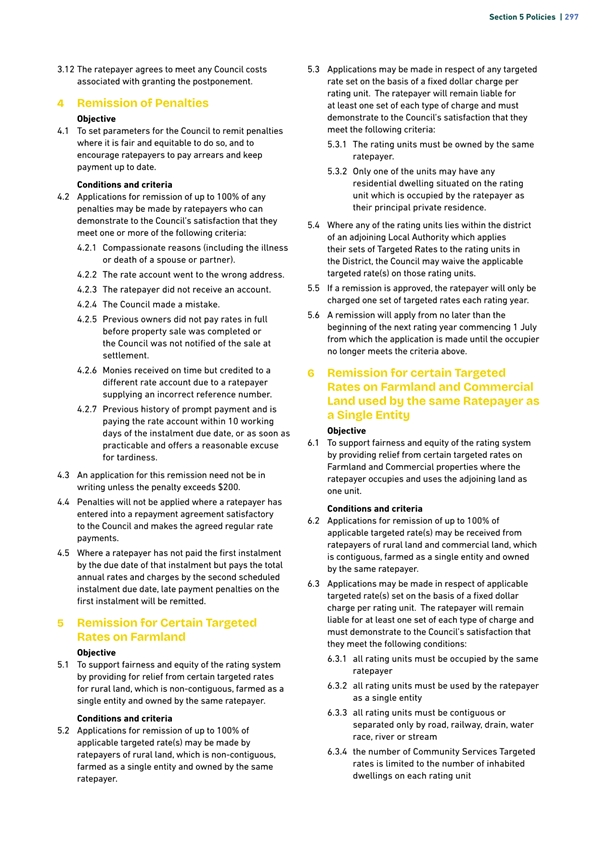
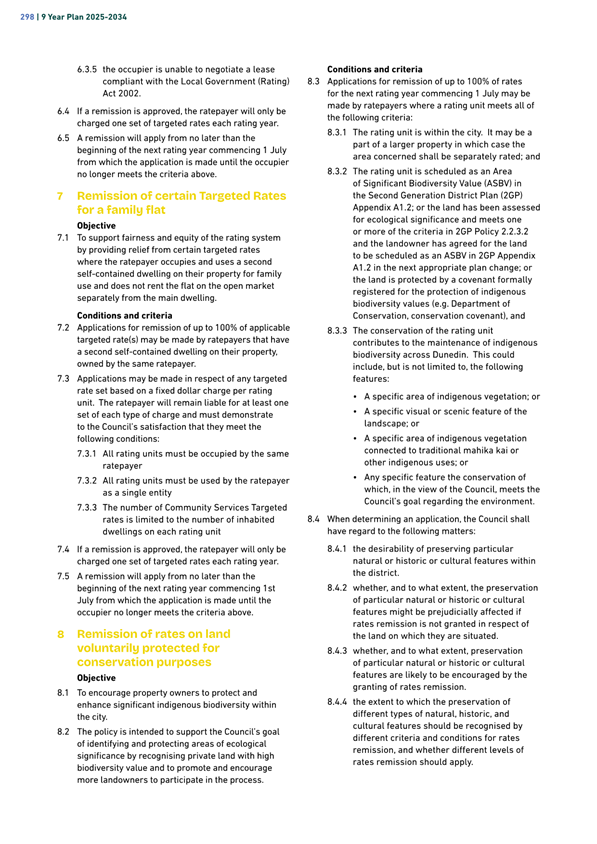
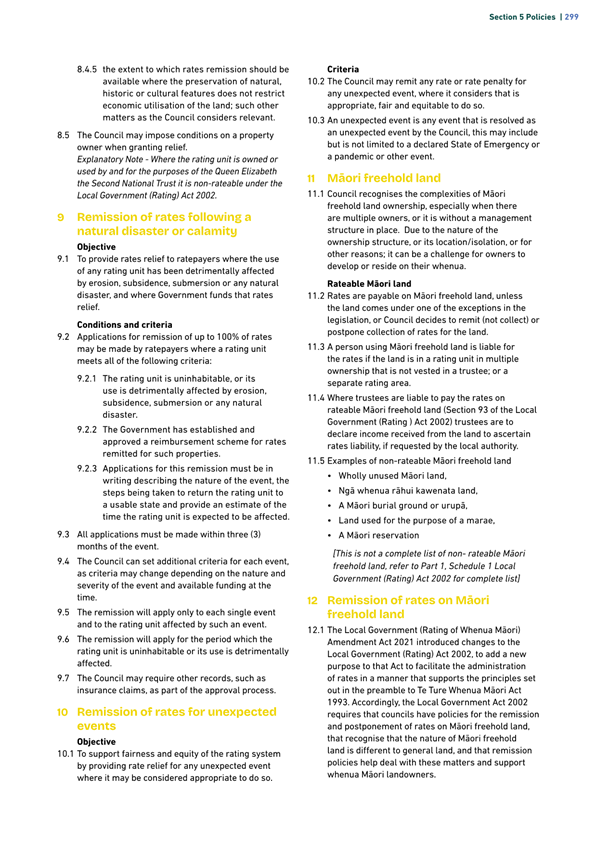
|
|
Finance and Performance Committee
27 August 2026
|
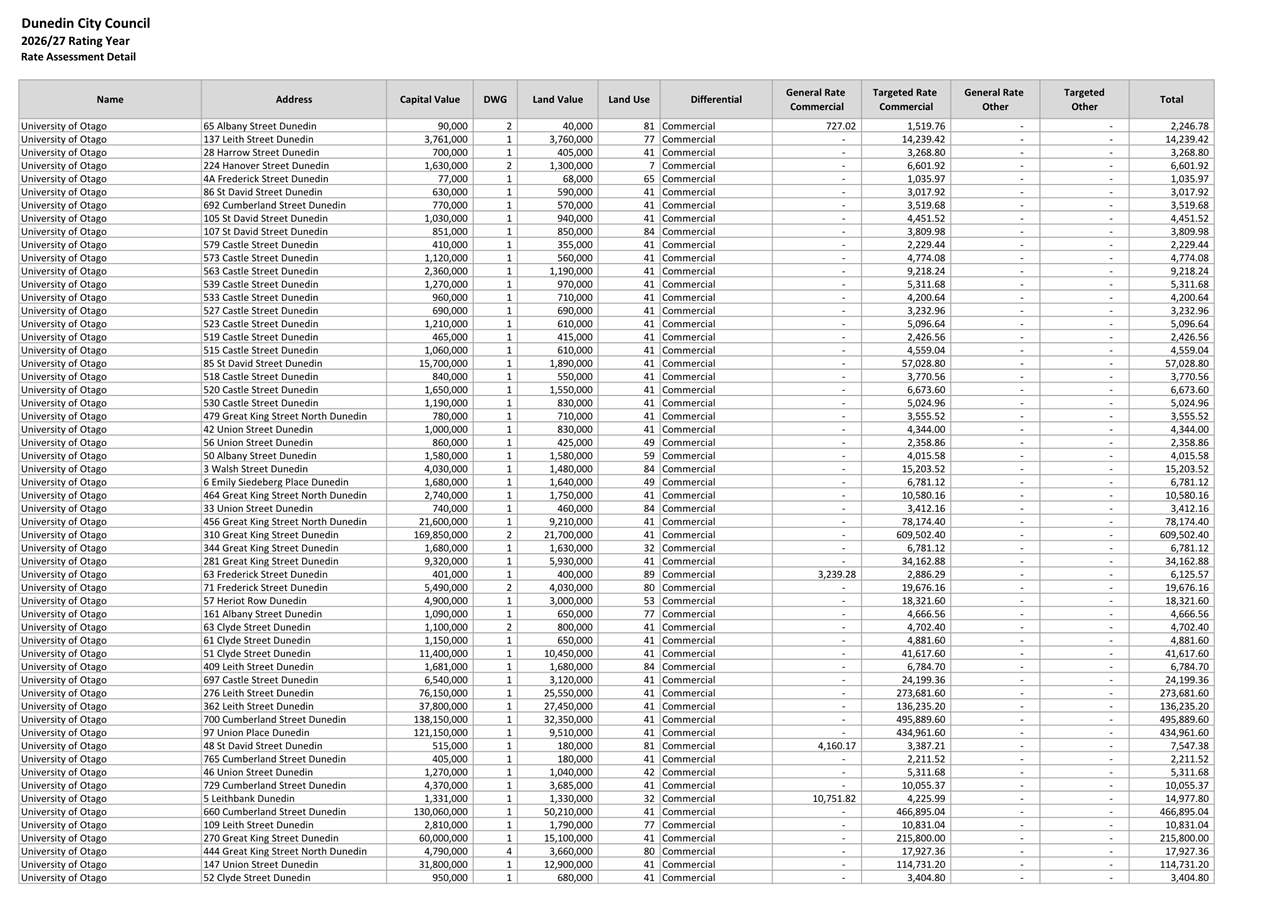
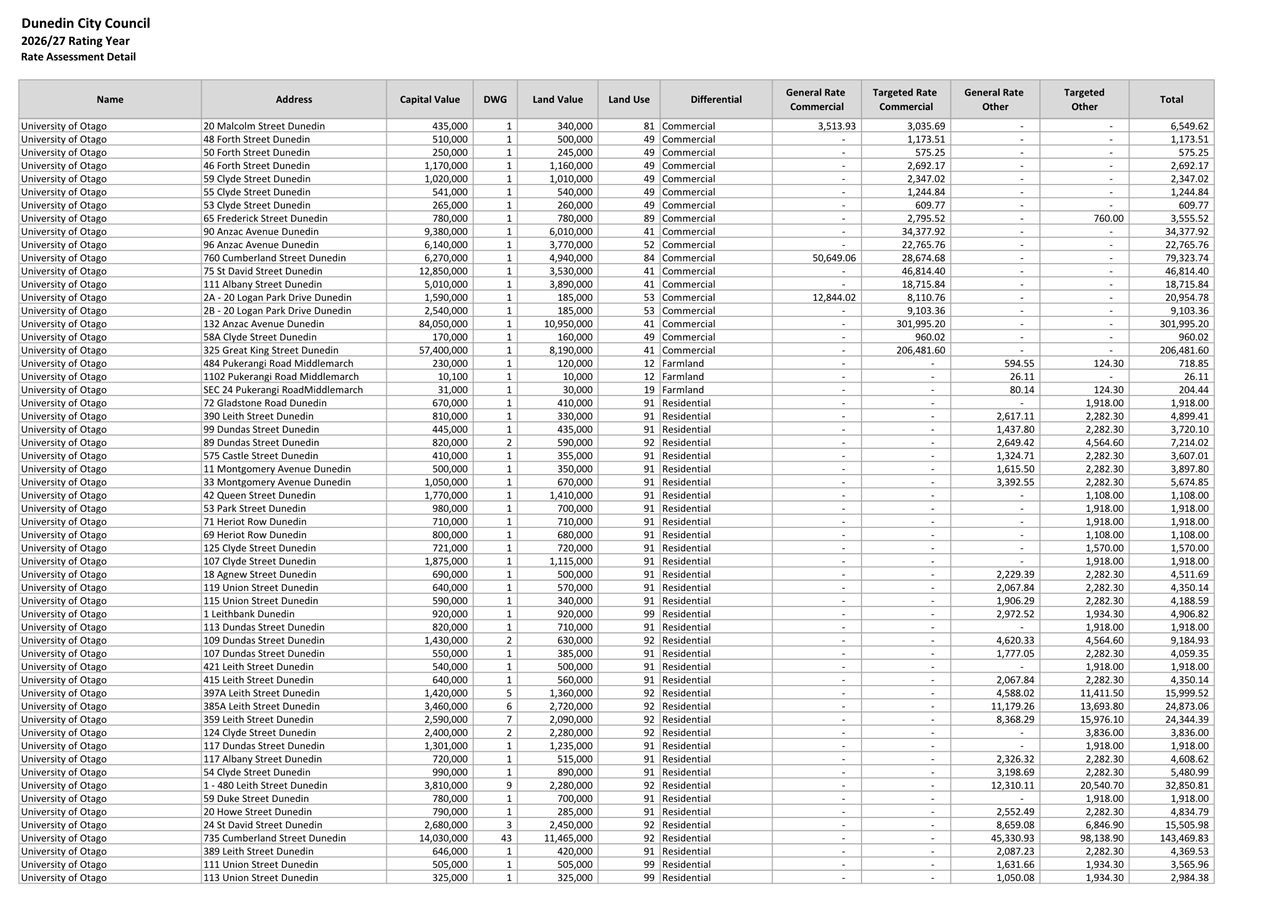
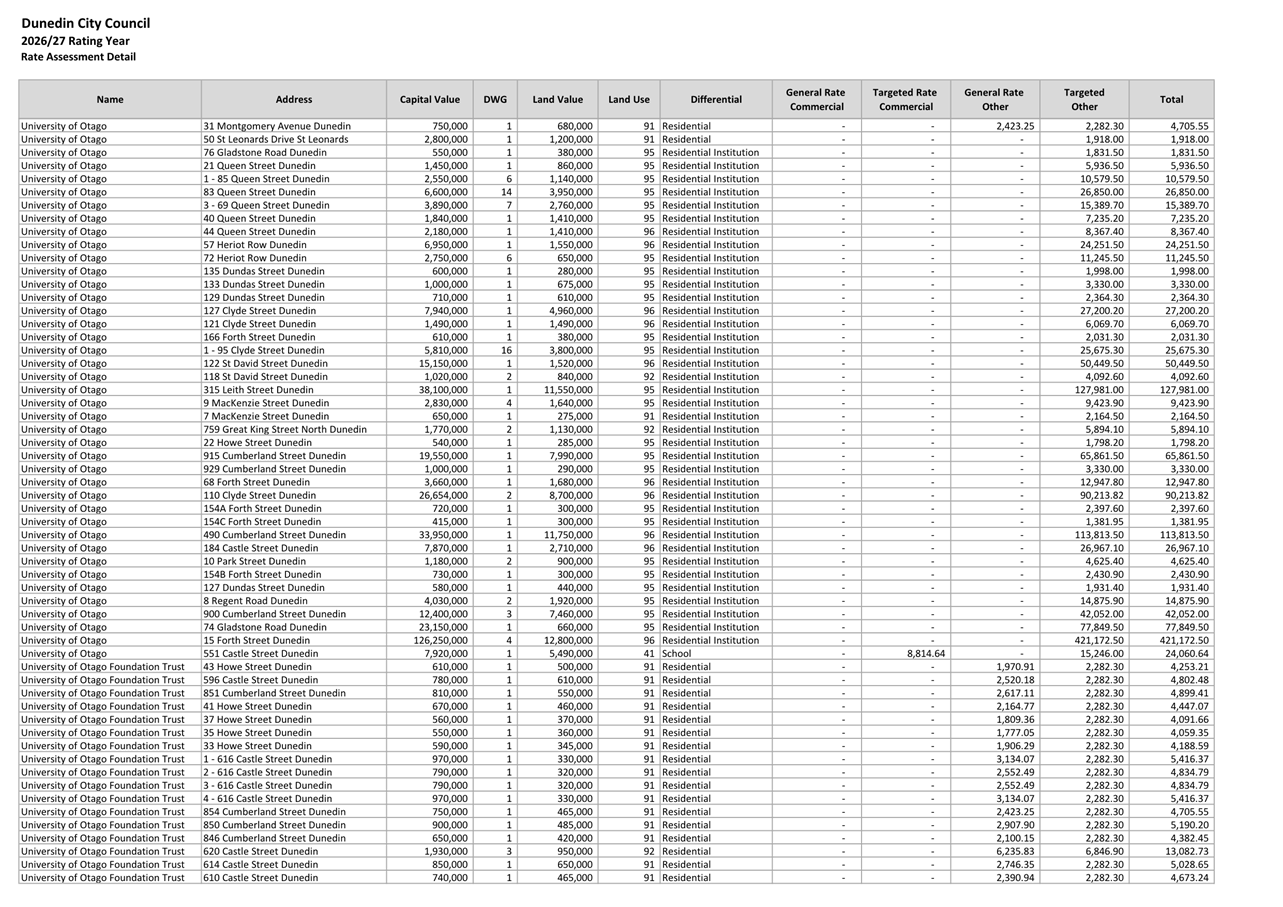
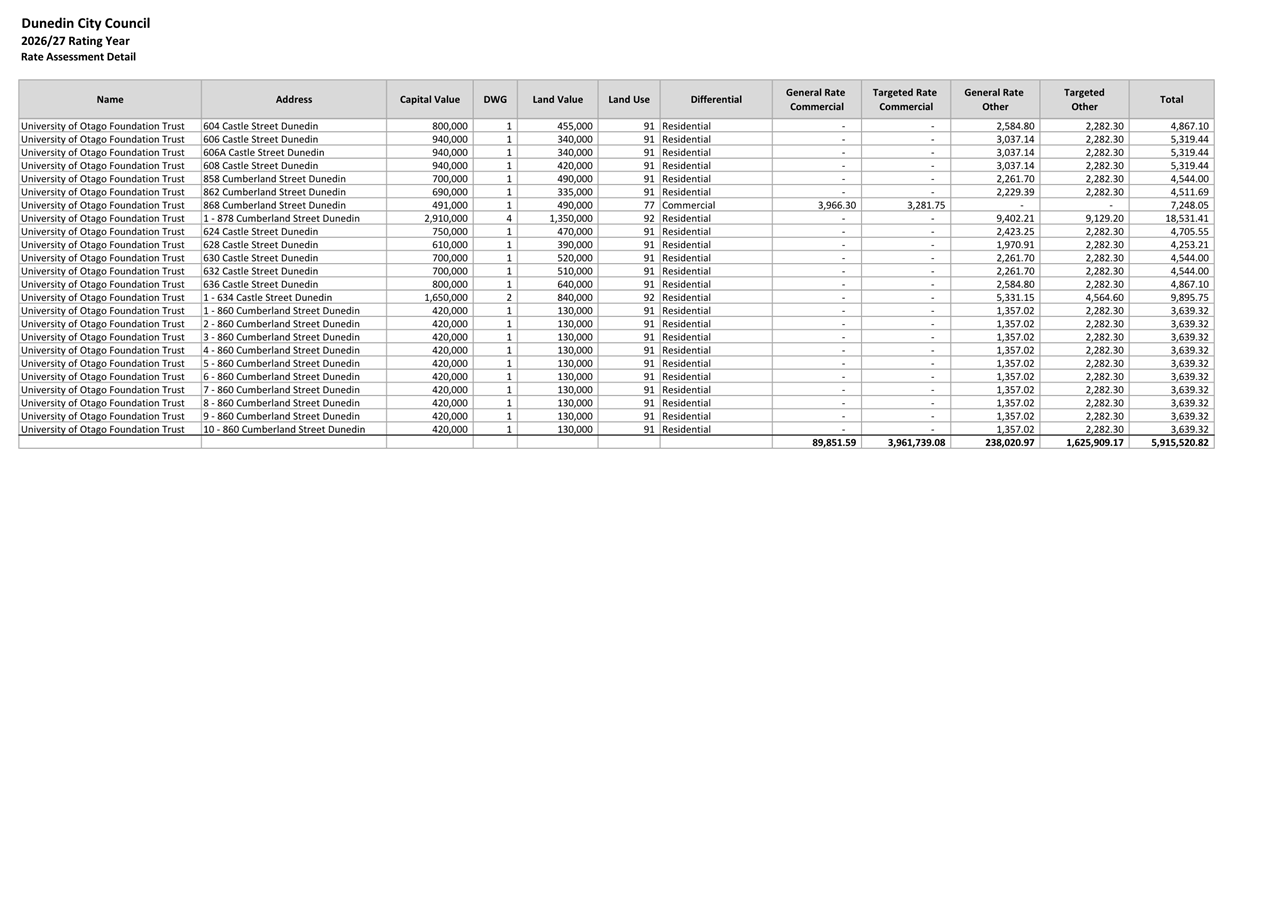
|
|
Finance and Performance Committee
27 August 2026
|
Ccv45rr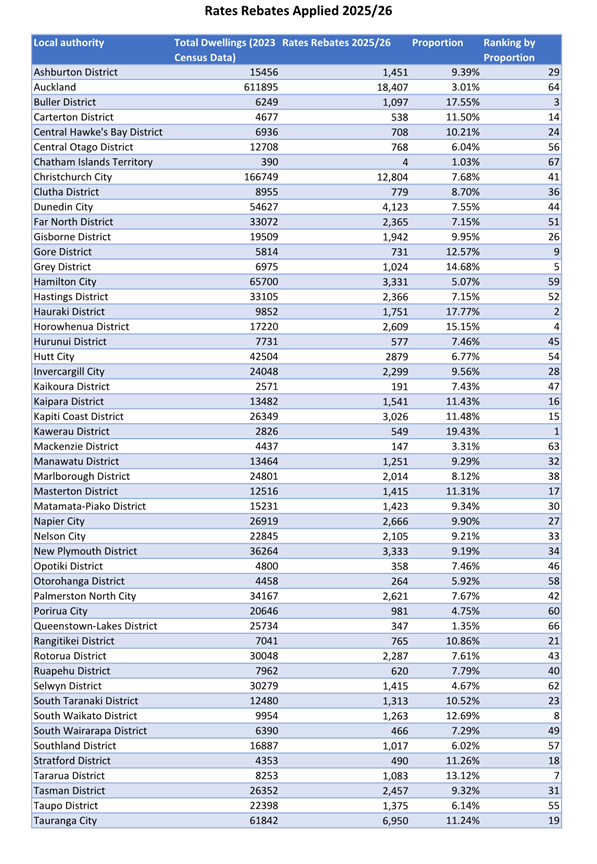
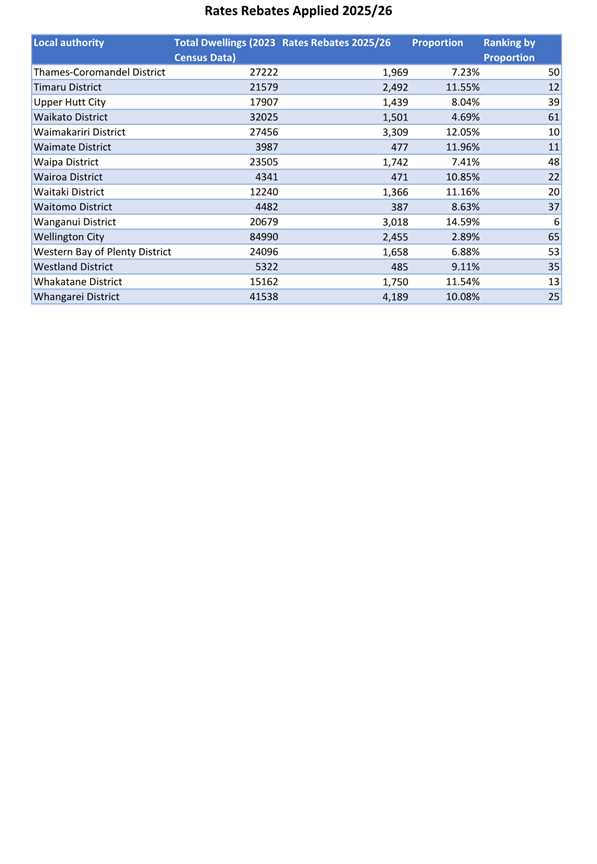
|
|
Finance and Performance Committee
27 August 2026
|
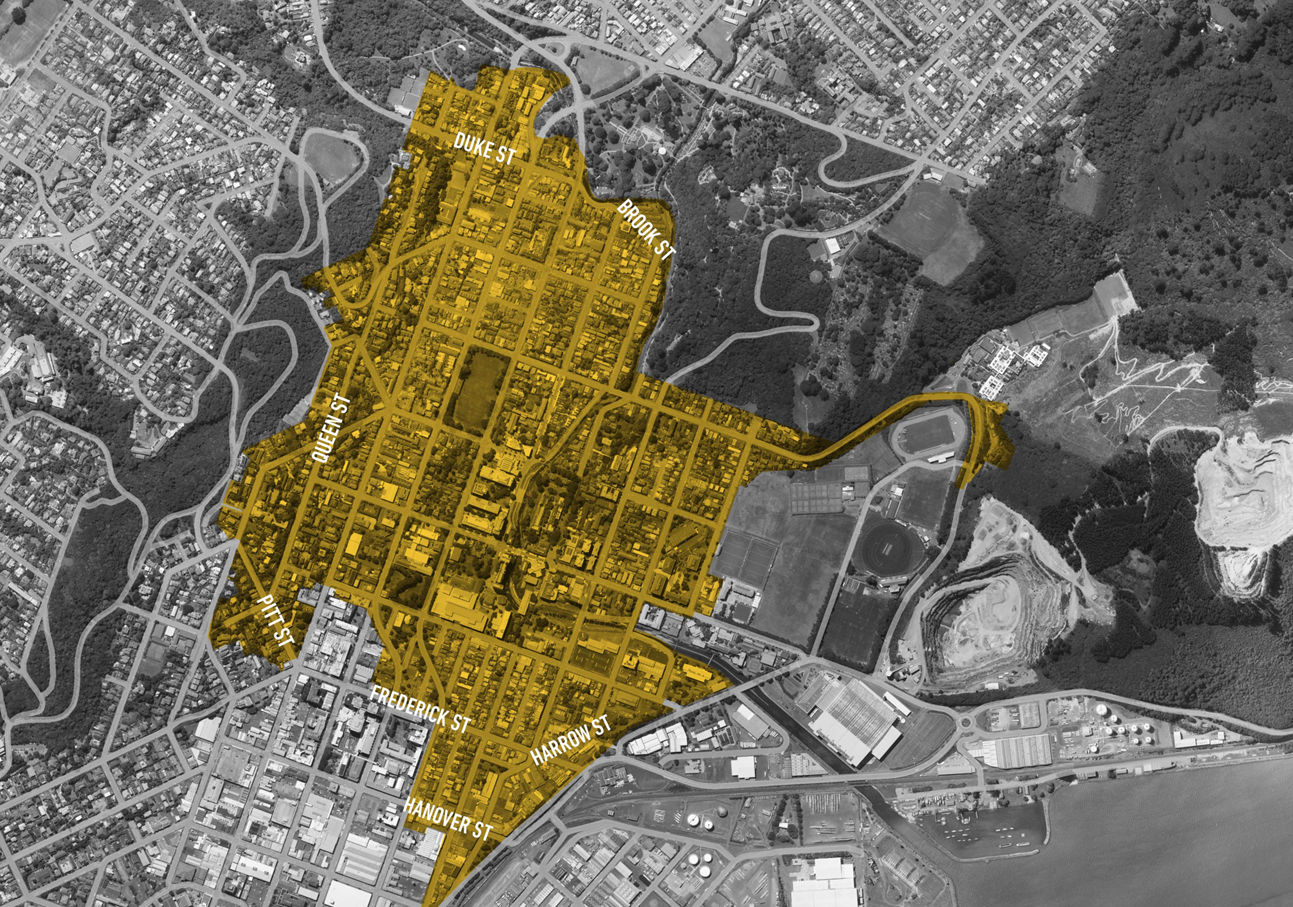
|
|
Finance and Performance Committee
27 August 2026
|
Financial Report - Period ended 30 June 2026
Department: Finance
EXECUTIVE SUMMARY
1 This
report provides the provisional financial results for the period ended 30 June
2026 and the financial position as at that date, noting the results presented
are subject to final adjustments and external audit.
2 As
this is an administrative report only, there are no options or Summary of
Considerations.
RECOMMENDATIONS
That the Committee:
a) Notes the Financial
Performance for the period ended 30 June 2026 and the Financial Position as at
that date.
b) Notes the 30 June 2026
result is subject to final adjustments and external audit, by the Audit Office.
BACKGROUND
3 This
report attaches a financial update and financial statements for the period
ended 30 June 2026.
DISCUSSION
4 The
net surplus (including Waipori) for the period ended 30 June 2026 was $596k, a
$596k favourable variance to budget. A detailed commentary is provided
in Attachment A (Financial Update). In summary, the following variances were
recorded:
a) Revenue
was $447.276 million for the period, or $9.027 million unfavourable to budget.
b) Expenditure
was $455.388 million for the period, or $5.946 million favourable to budget.
c) The
Waipori Fund has reported a net operating surplus for the period of $8.708
million, $3.677 million favourable to budget.
5 Capital
expenditure was $174.848 million for the period ended 30 June 2026 or 75.6% of
the full year budget.
6 The
total loan balance at 30 June 2026 was $711.500 million which was $71.673 million
less than budget.
Final Adjustments and External Audit
7 Final
adjustments still to be reflected, in addition to this report include:
· Completion of vested assets
· Revaluation of assets (Three Waters, Transport, Investment Property)
· Landfill aftercare provisions
· Depreciation
8 The
Audit Office is scheduled to start their audit mid-September 2026, with an
expected signoff date of 30 October 2026.
NEXT STEPS
9 Month
end financial reports will continue to be presented to future Council or
Finance and Performance Committee meetings.
Signatories
|
Author:
|
Lawrie Warwood - Management Accountant
|
|
Authoriser:
|
Stephanie Freeman - Management Accountant Lead
Carolyn Allan - Chief Financial Officer
|
Attachments
|
|
Title
|
Page
|
|
⇩a
|
Financial Update
|
299
|
|
⇩b
|
Statement of Financial
Performance
|
314
|
|
⇩c
|
Statement of Financial
Position
|
315
|
|
⇩d
|
Statement of Cashflows
|
316
|
|
⇩e
|
Capital Expenditure
Summary
|
317
|
|
⇩f
|
Capital Expenditure
Detailed
|
319
|
|
⇩g
|
Statement of Operating
Variances
|
326
|
|
⇩h
|
Debt Graph
|
327
|
|
|
Finance and Performance Committee
27 August 2026
|
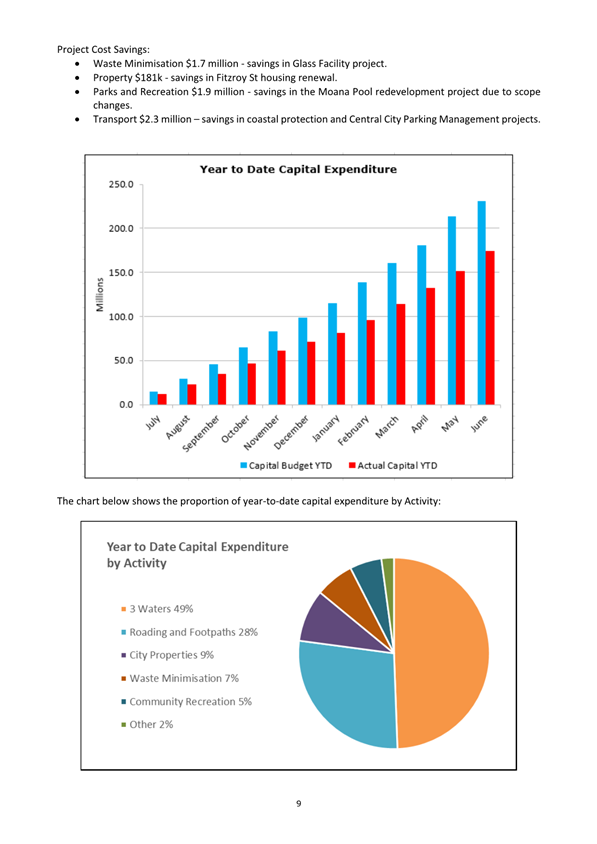
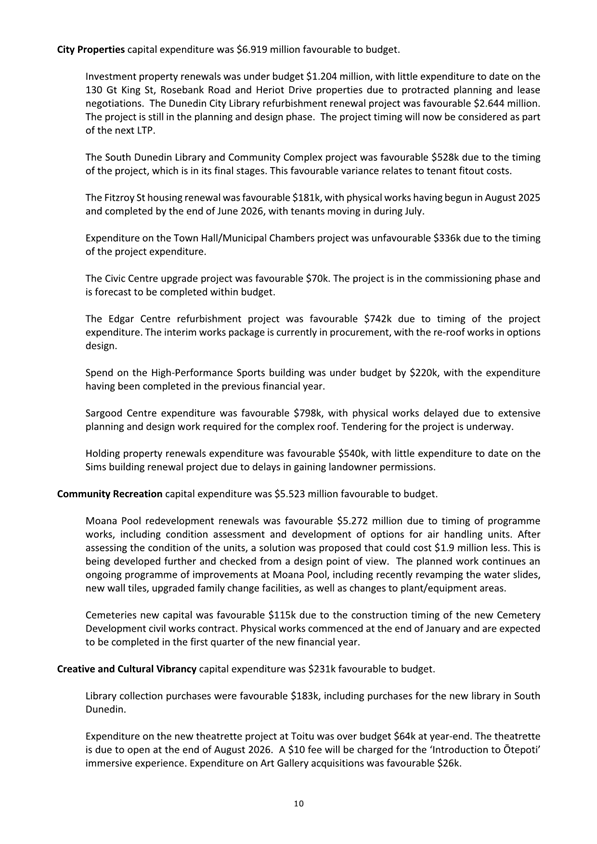
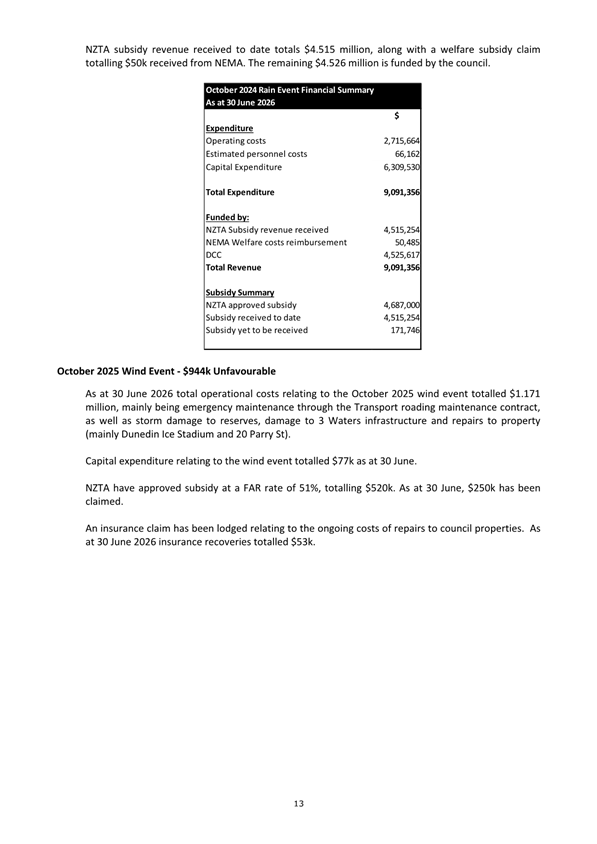
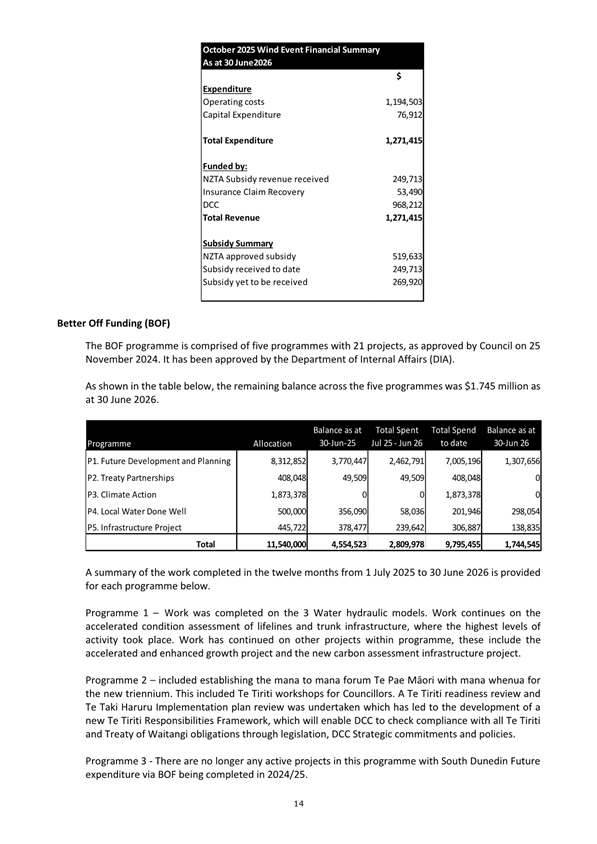
|
|
Finance and Performance Committee
27 August 2026
|
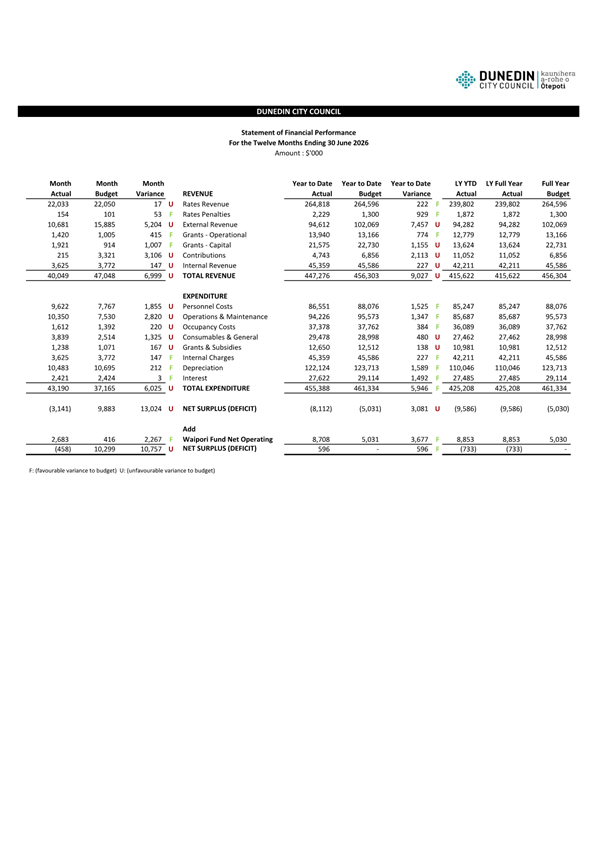
|
|
Finance and Performance Committee
27 August 2026
|
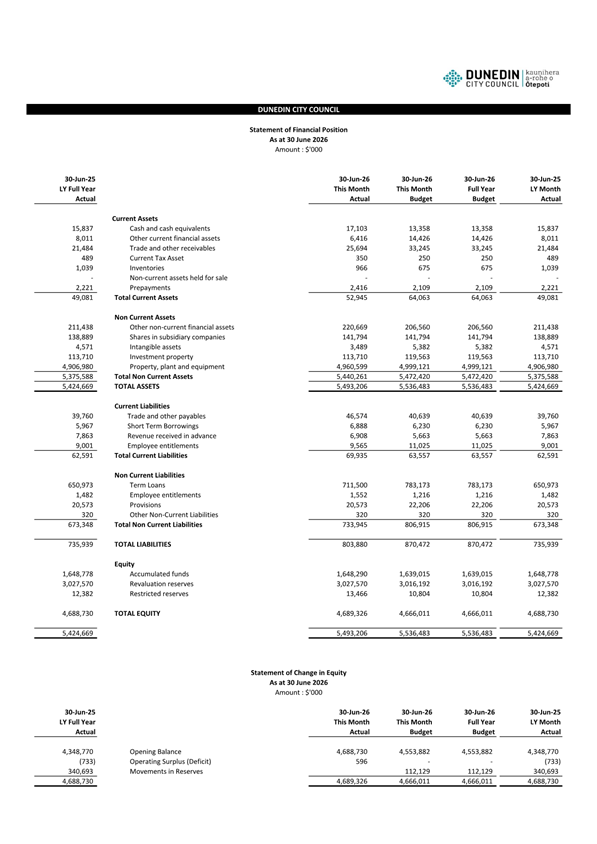
|
|
Finance and Performance Committee
27 August 2026
|
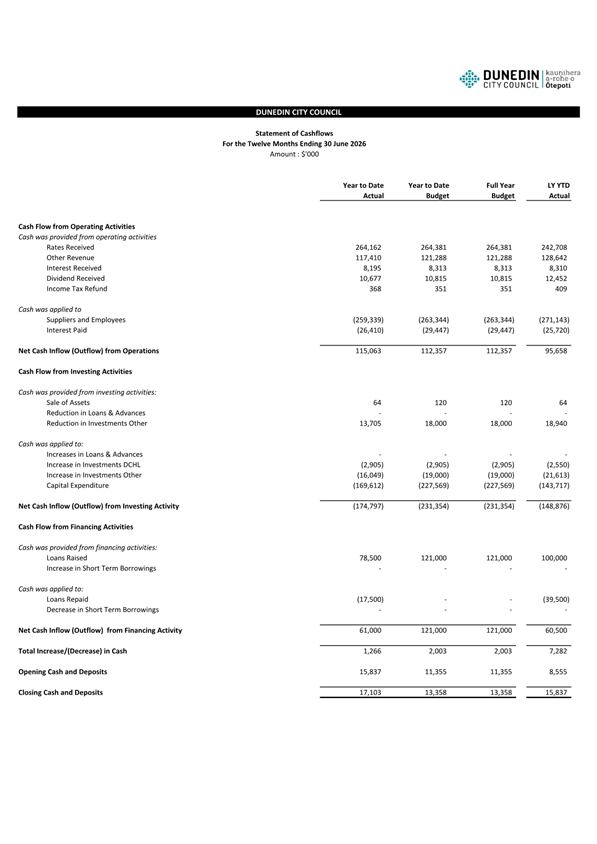
|
|
Finance and Performance Committee
27 August 2026
|
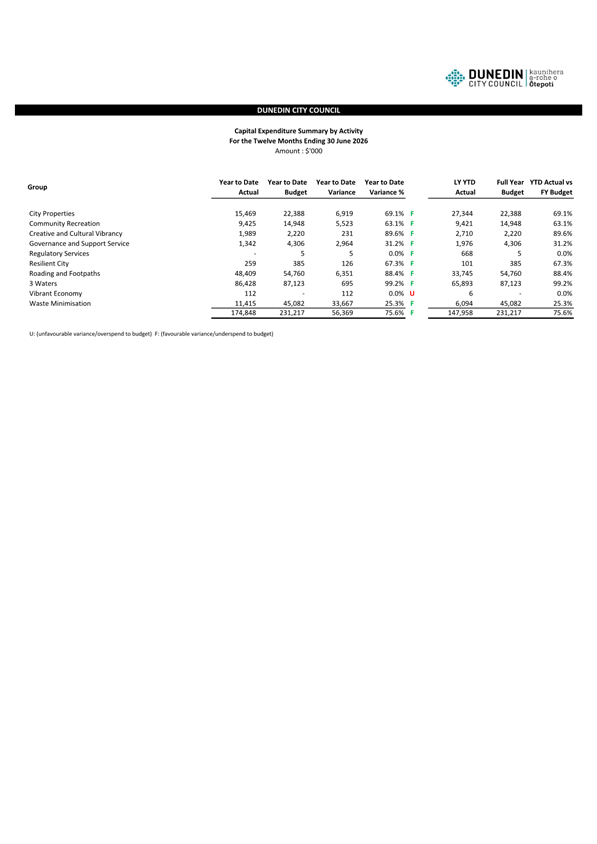
|
|
Finance and Performance Committee
27 August 2026
|
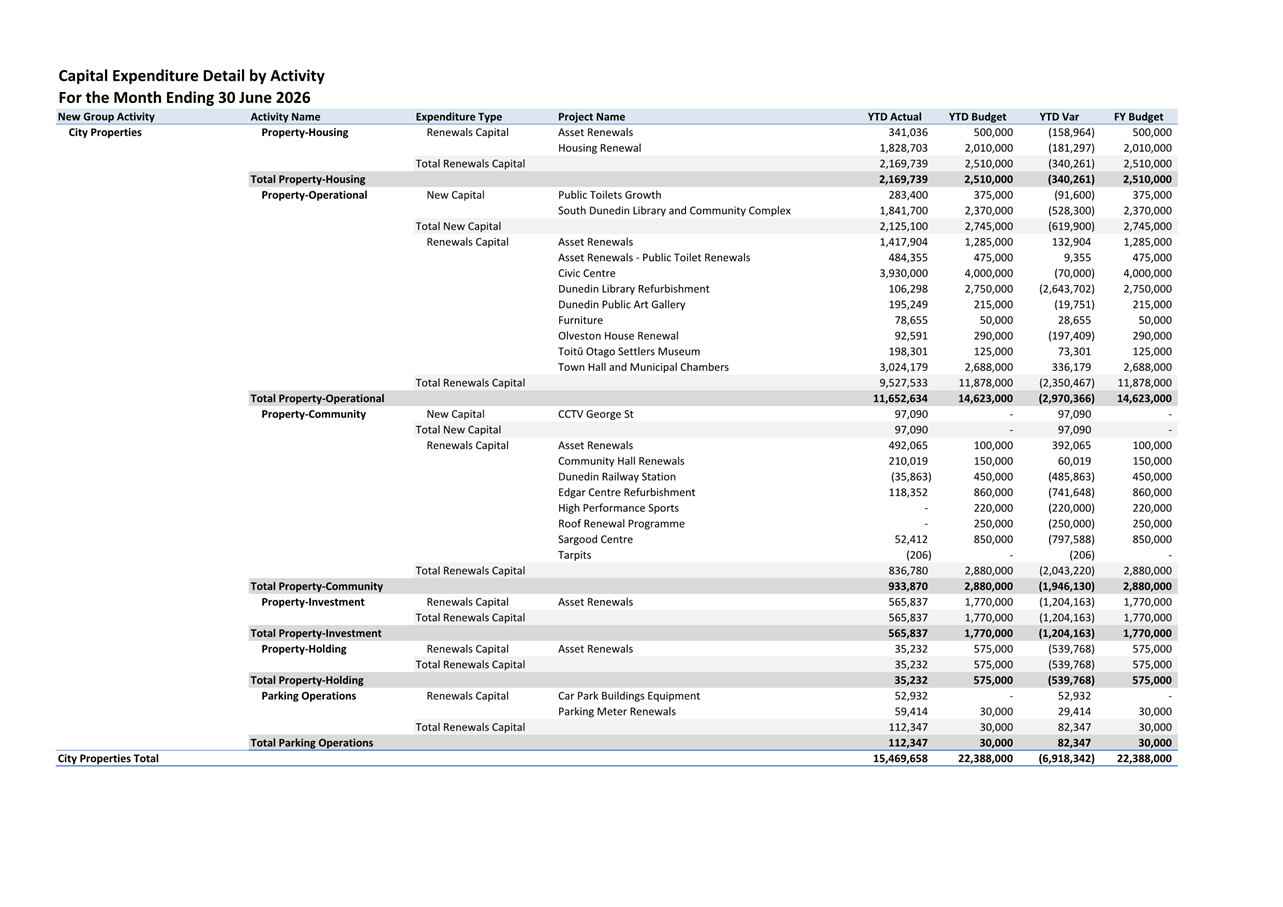
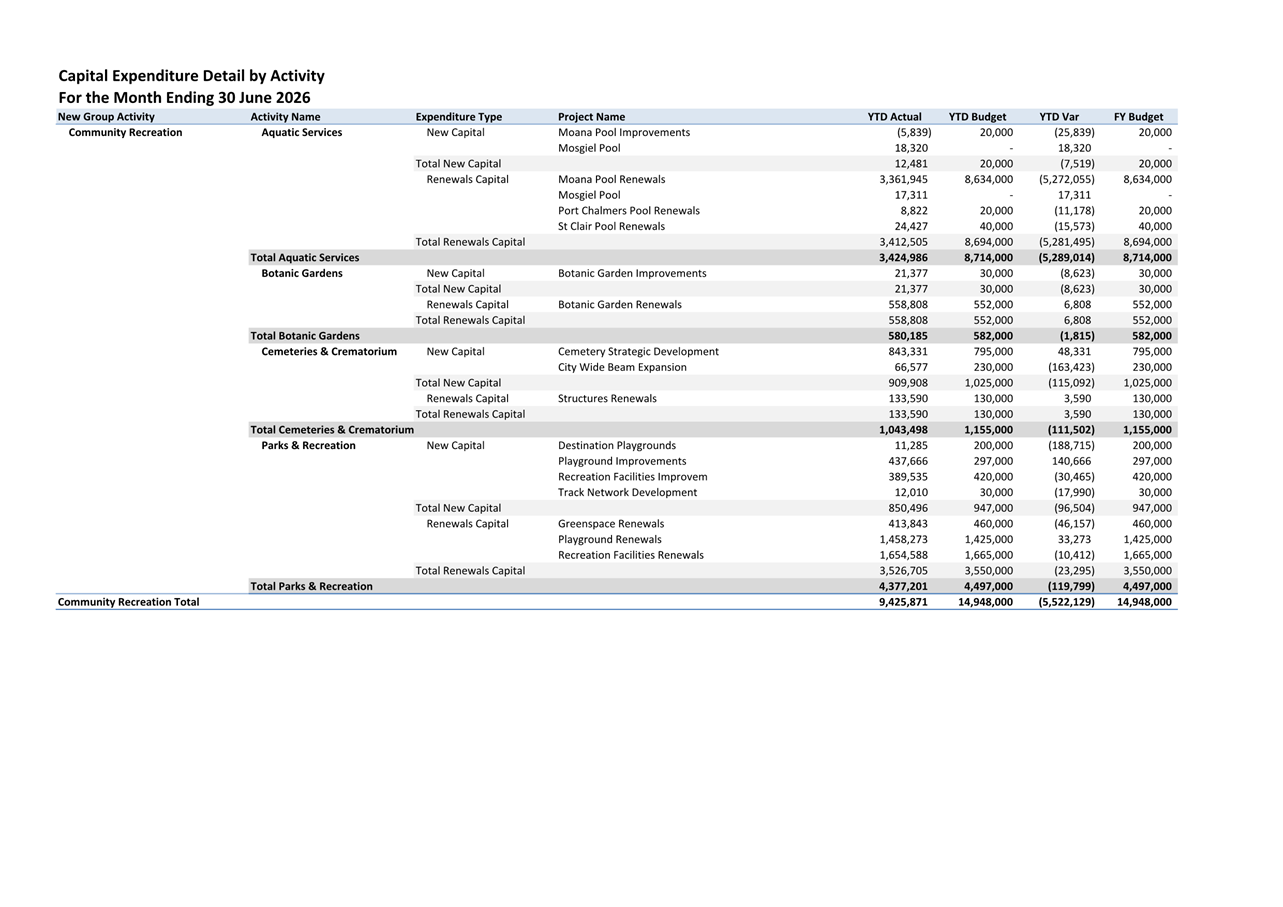
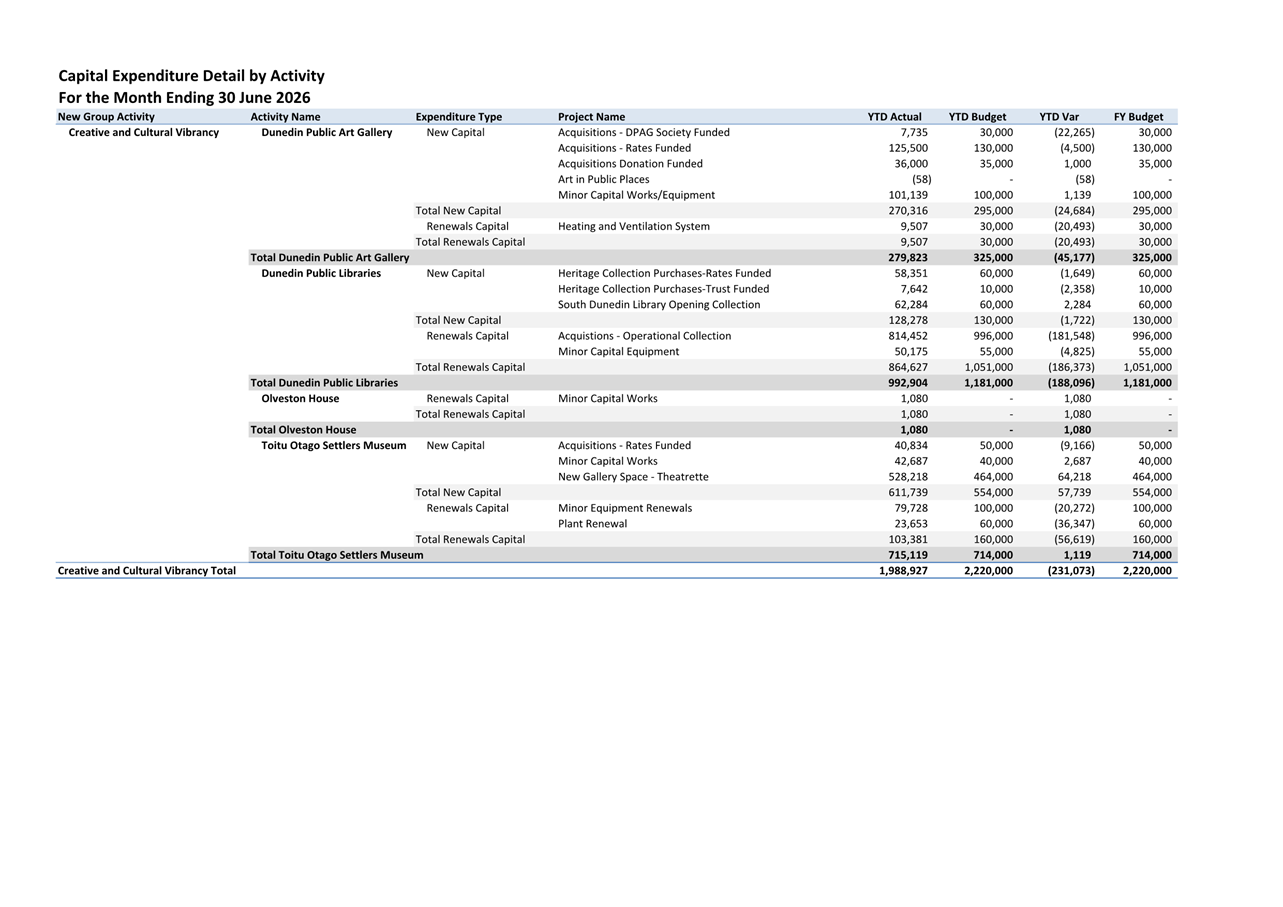
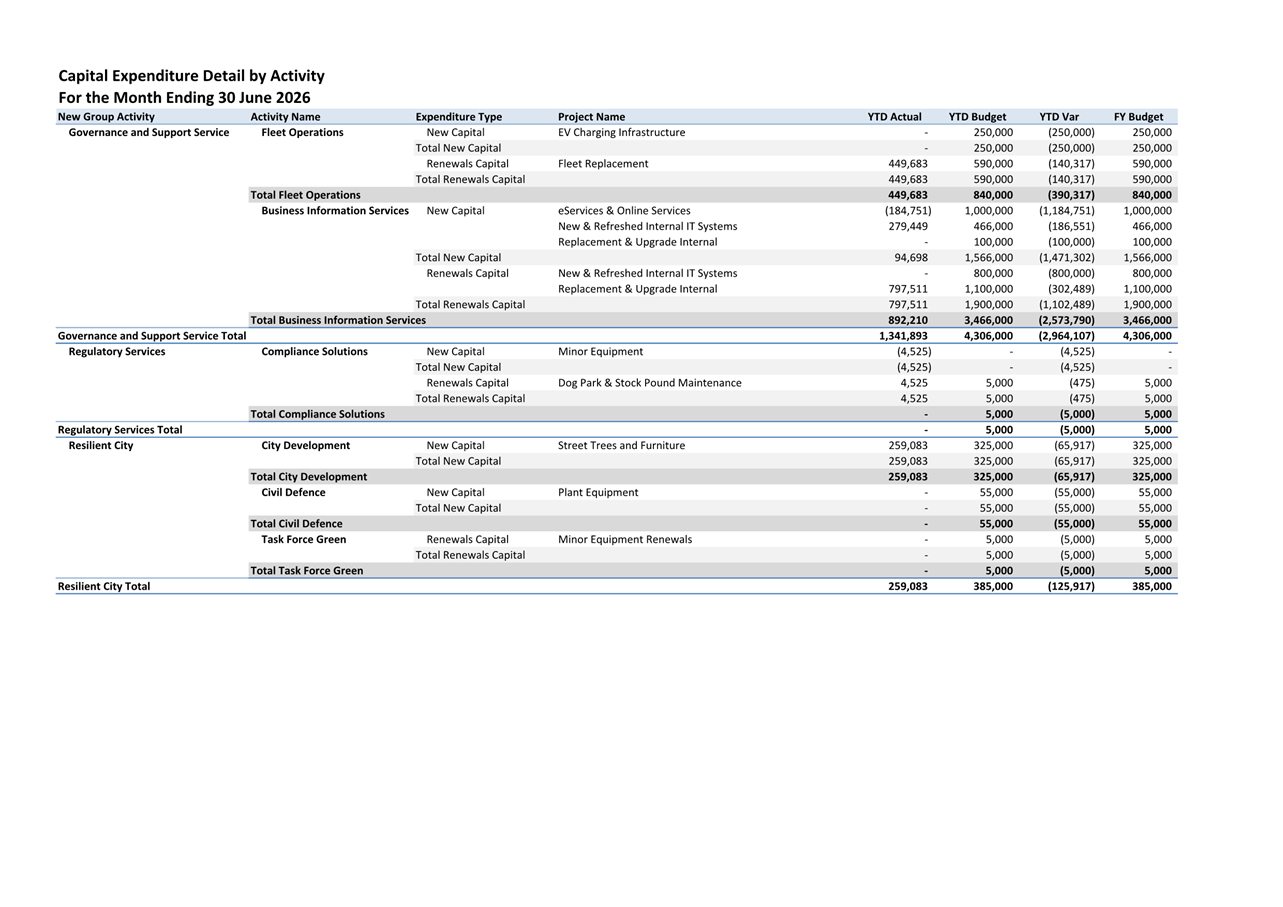
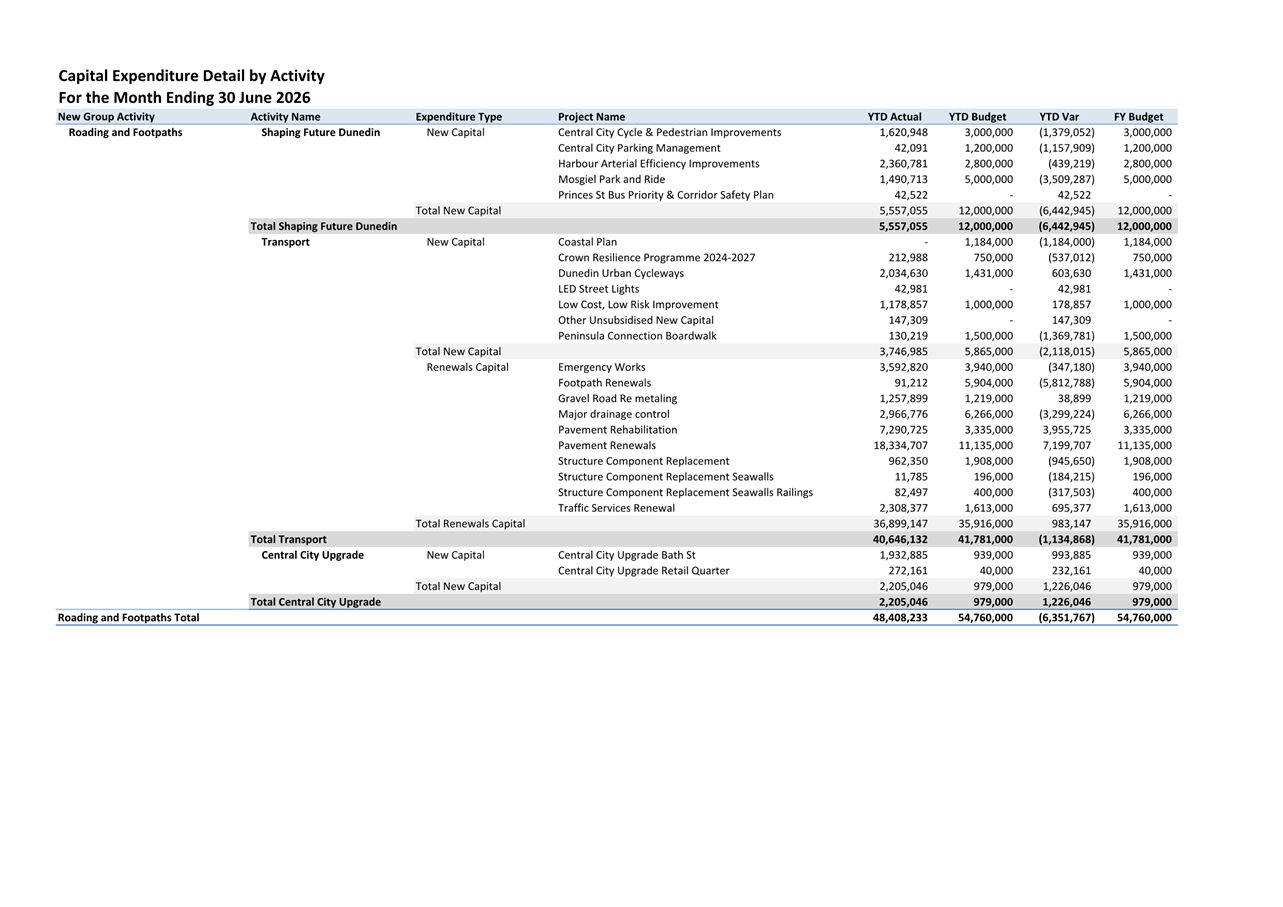
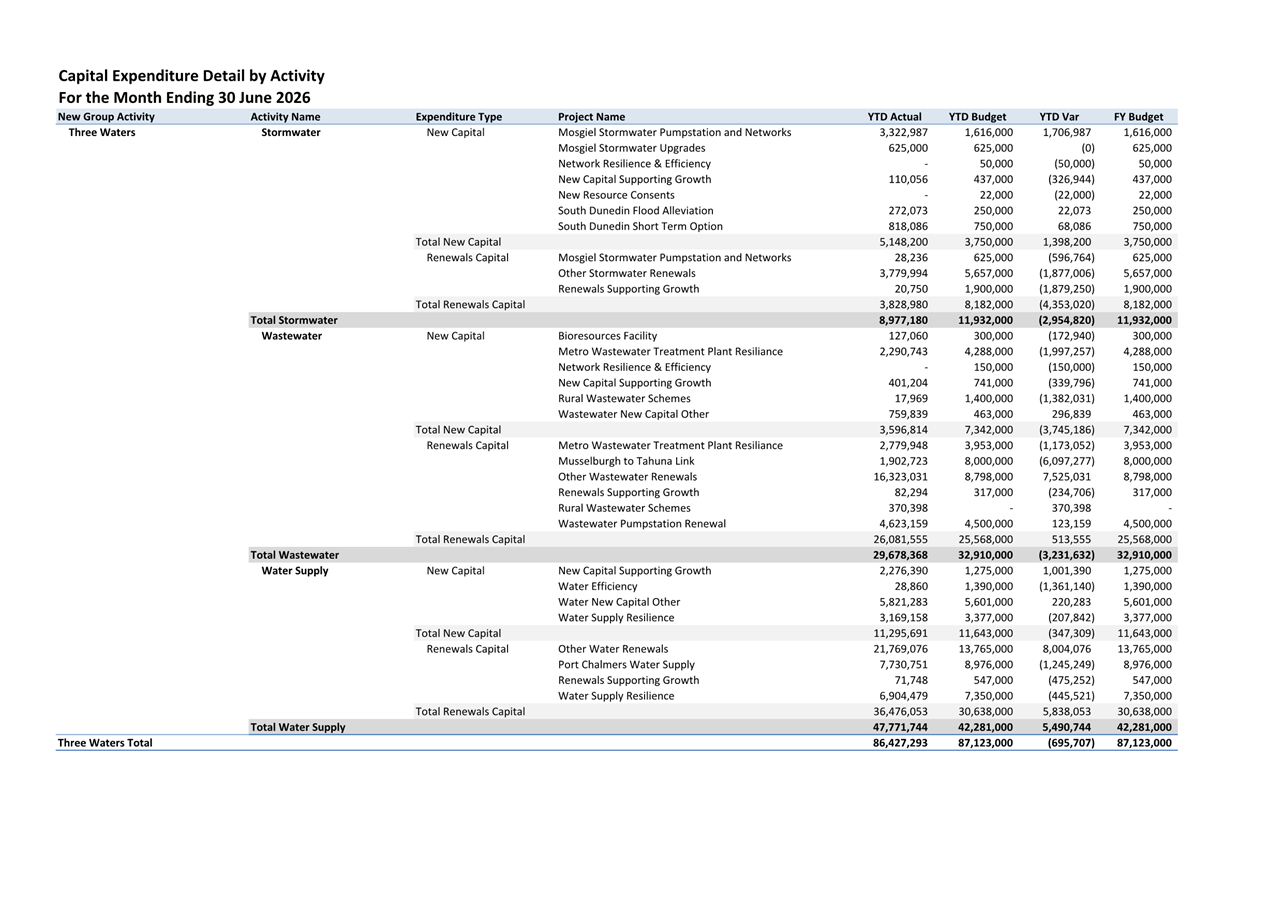
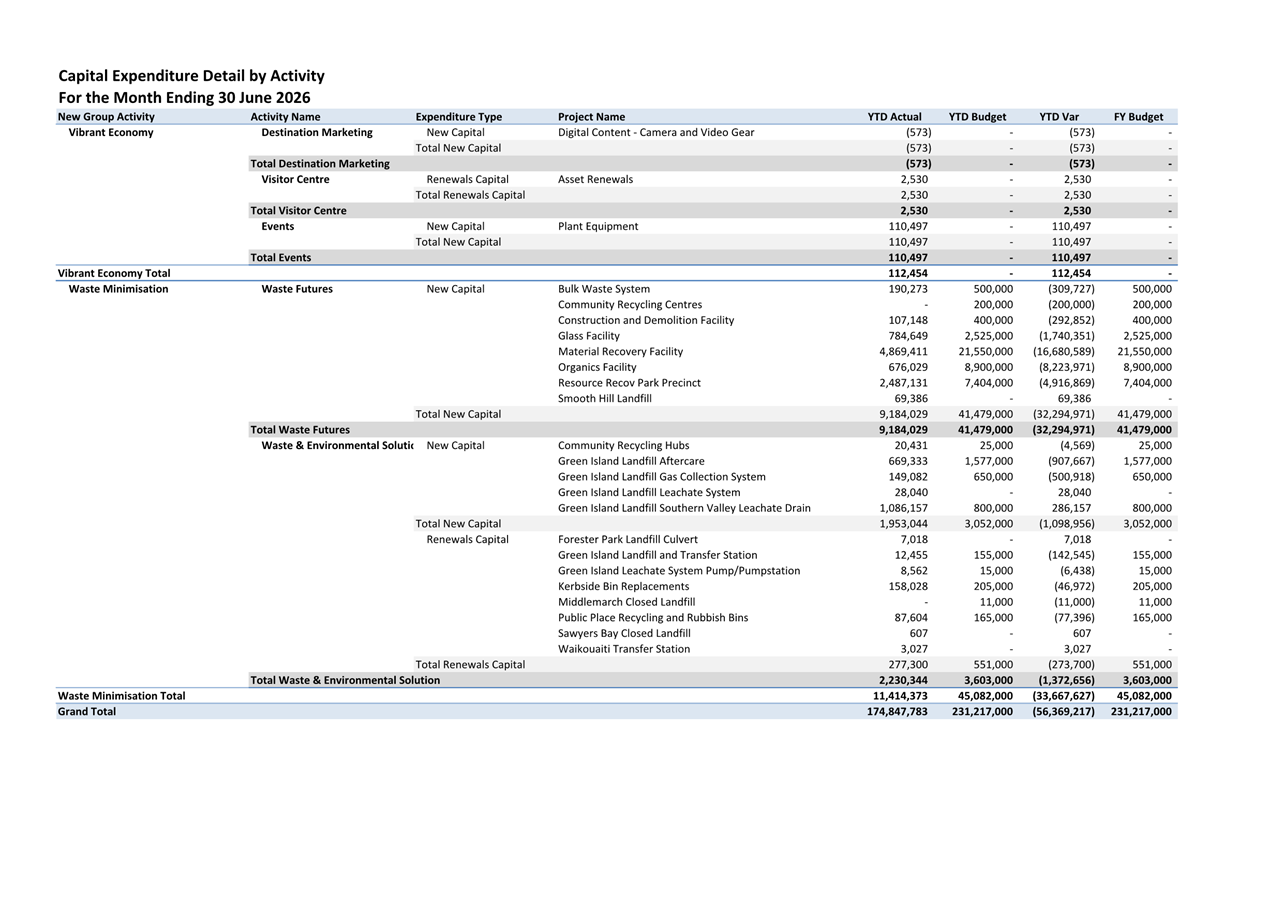
|
|
Finance and Performance Committee
27 August 2026
|
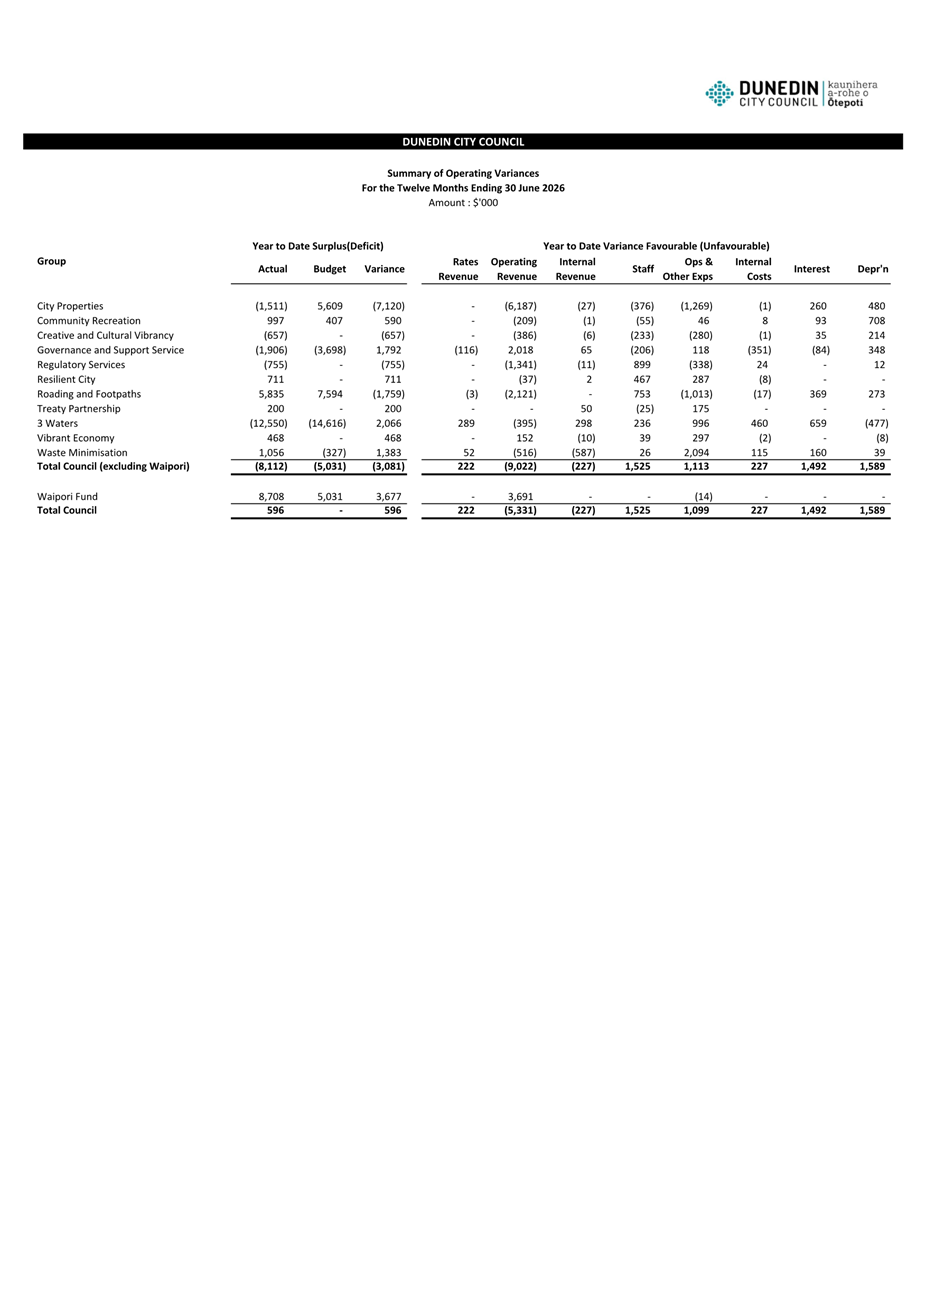
|
|
Finance and Performance Committee
27 August 2026
|
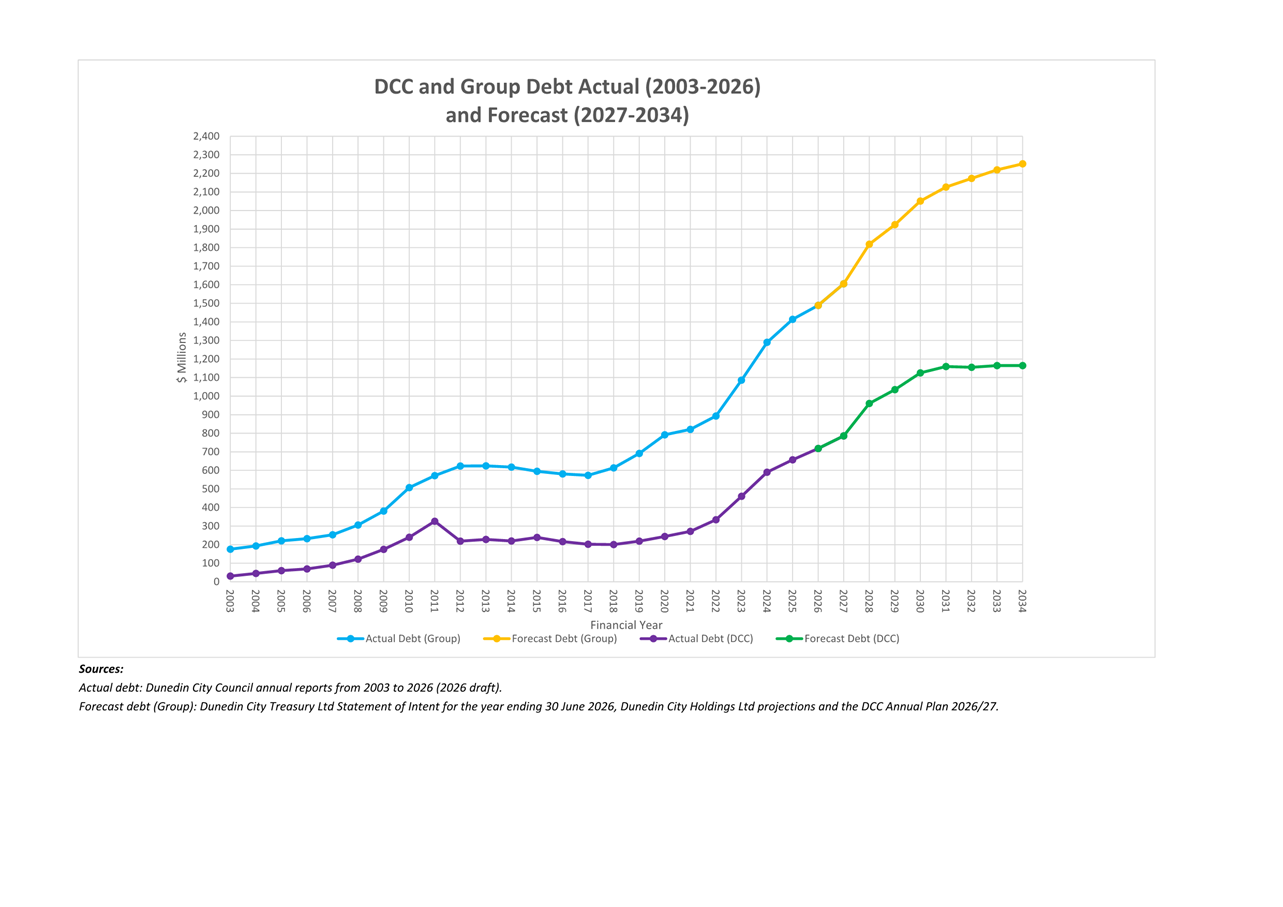
|
|
Finance and Performance Committee
27 August 2026
|
Items for Consideration by the Chair
Any items for consideration
by the Chair.
|
|
Finance and Performance
Committee
27 August 2026
|
Resolution to Exclude the
Public
That the Finance and
Performance Committee:
Pursuant to the provisions of the
Local Government Official Information and Meetings Act 1987, exclude the public
from the following part of the proceedings of this meeting namely:
|
General subject of the matter to be considered
|
Reasons
for passing this resolution in relation to each matter
|
Ground(s) under
section 48(1) for the passing of this resolution
|
Reason for
Confidentiality
|
|
C1 Confirmation
of the Confidential Minutes of Finance and Performance Committee meeting - 21
May 2026 - Public Excluded
|
S7(2)(b)(ii)
The
withholding of the information is necessary to protect information where the
making available of the information would be likely unreasonably to prejudice
the commercial position of the person who supplied or who is the subject of
the information.
|
.
|
|
|
C2 Directors
Remuneration - Dunedin City Holdings Limited
|
S7(2)(a)
The
withholding of the information is necessary to protect the privacy of natural
persons, including that of a deceased person.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
The information in this
report remains confidential until Council has determined the level of fees
and advised Dunedin City Holdings Limited of the outcome, at which time the
information can be made public..
|
|
C3 Director
Vacancy in Dunedin City Holdings Limited
|
S7(2)(a)
The
withholding of the information is necessary to protect the privacy of natural
persons, including that of a deceased person.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
|
|
C4 Investment
Property Portfolio - Quarter ending 30 June 2026
|
S7(2)(b)(ii)
The
withholding of the information is necessary to protect information where the
making available of the information would be likely unreasonably to prejudice
the commercial position of the person who supplied or who is the subject of
the information.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
|
This resolution is made in
reliance on Section 48(1)(a) of the Local Government Official Information and
Meetings Act 1987, and the particular interest or interests protected by Section
6 or Section 7 of that Act, or Section 6 or Section 7 or Section 9 of the
Official Information Act 1982, as the case may require, which would be
prejudiced by the holding of the whole or the relevant part of the proceedings
of the meeting in public are as shown above after each item.