Notice of Meeting:
I hereby give notice that an ordinary meeting of the Audit,
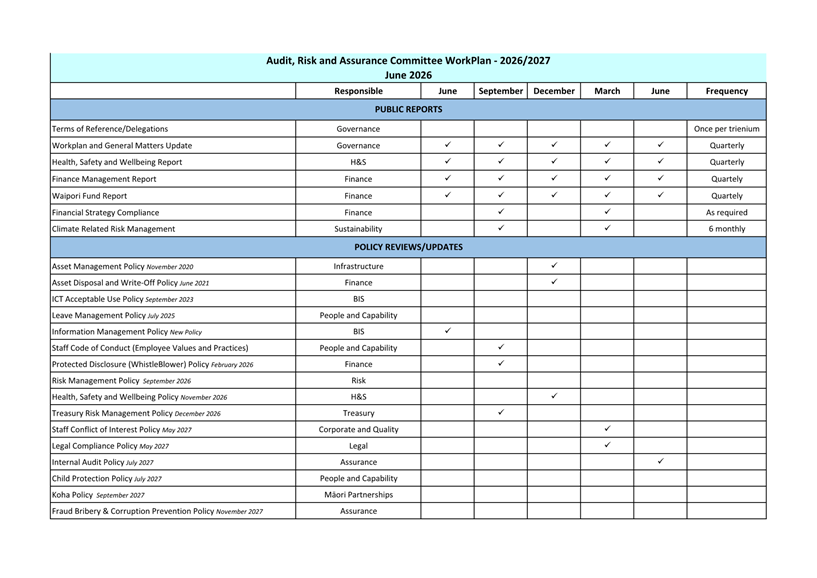
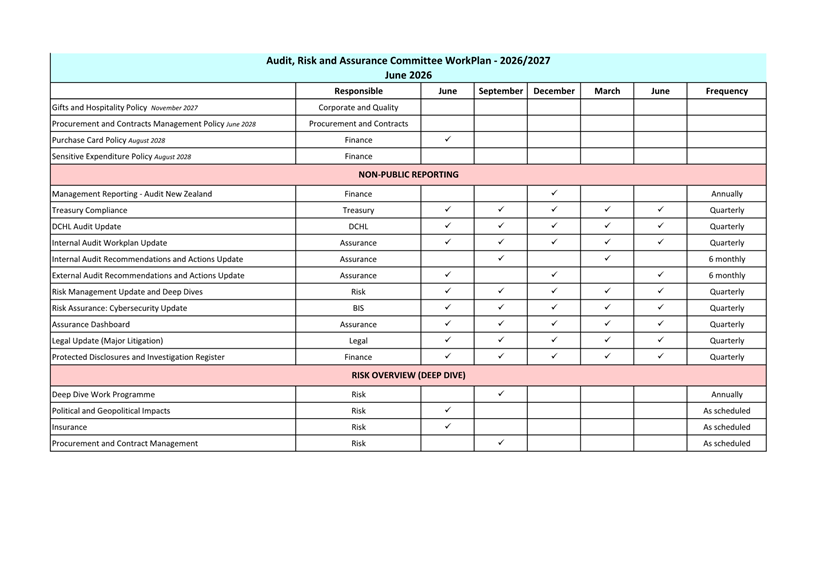
Risk and Assurance Committee will be held on:
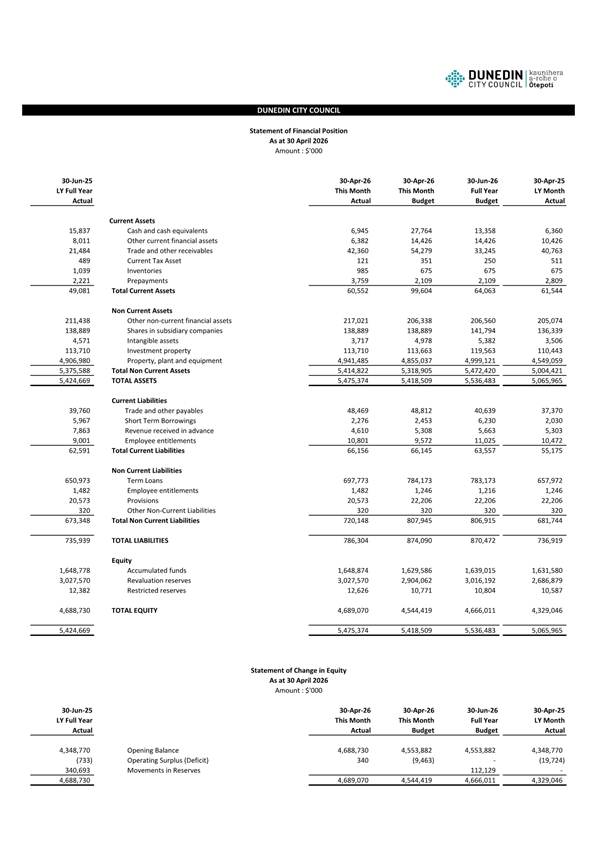
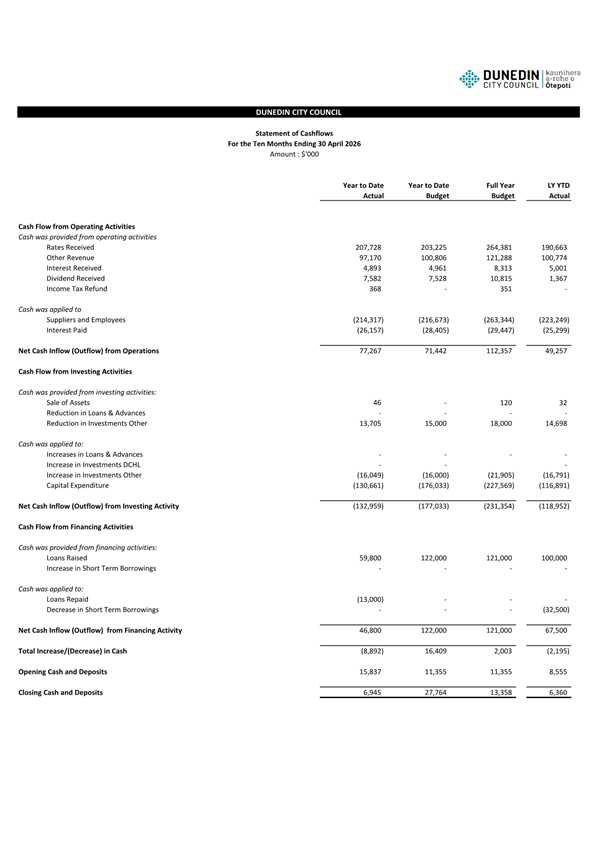
Date: Tuesday
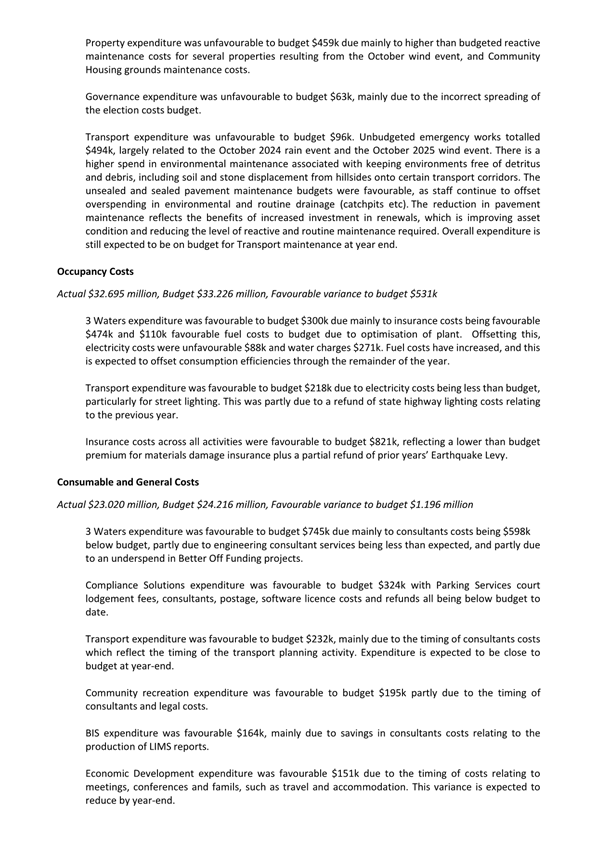
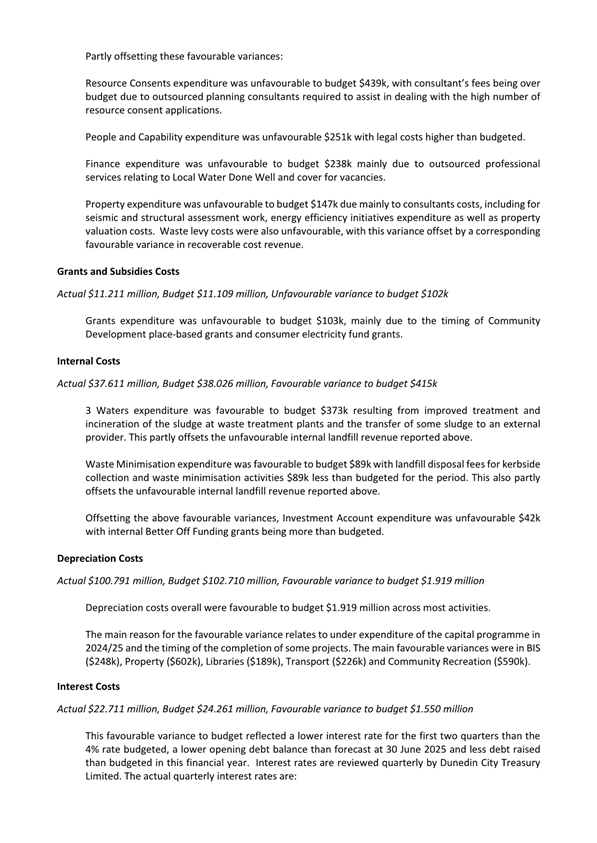
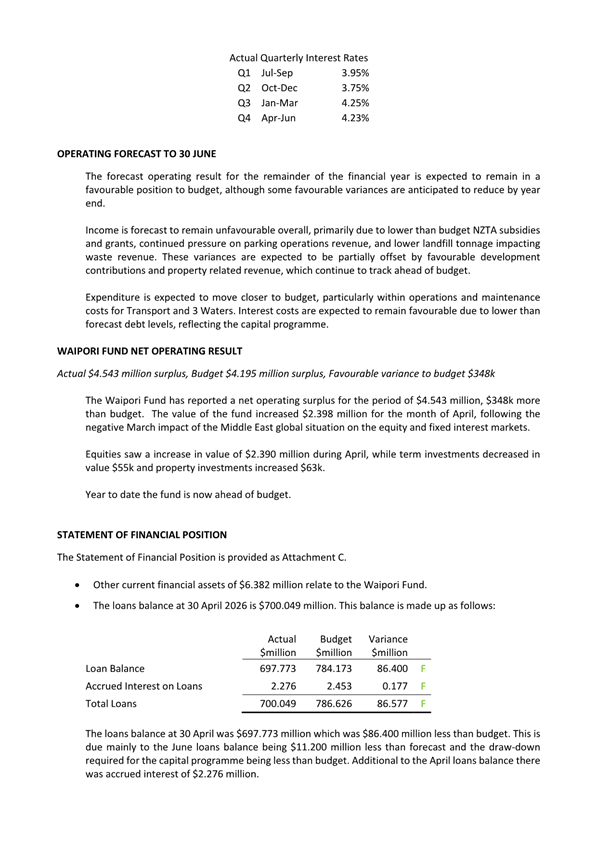
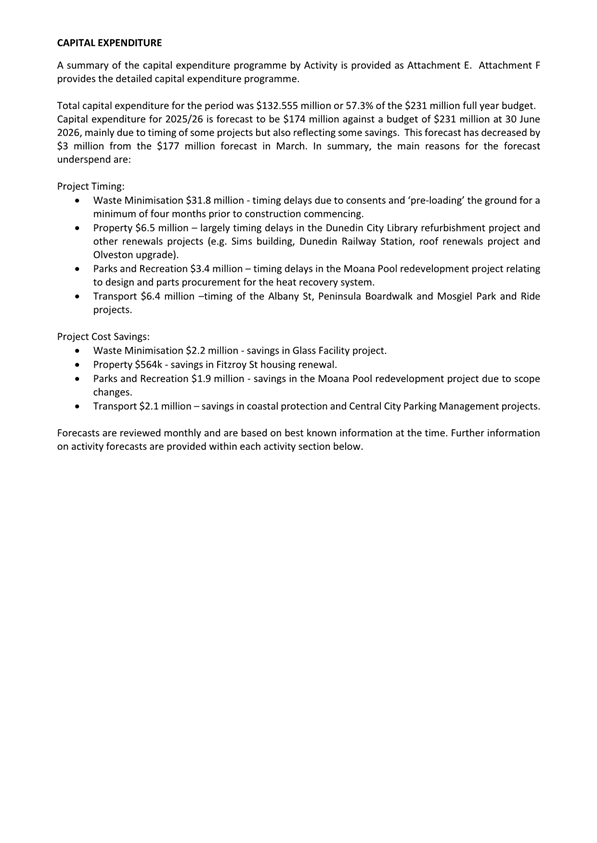
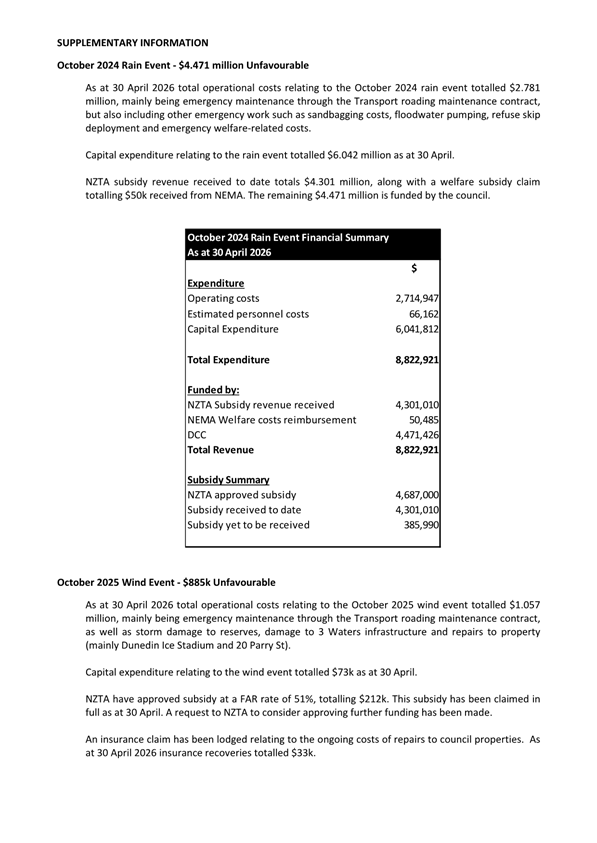
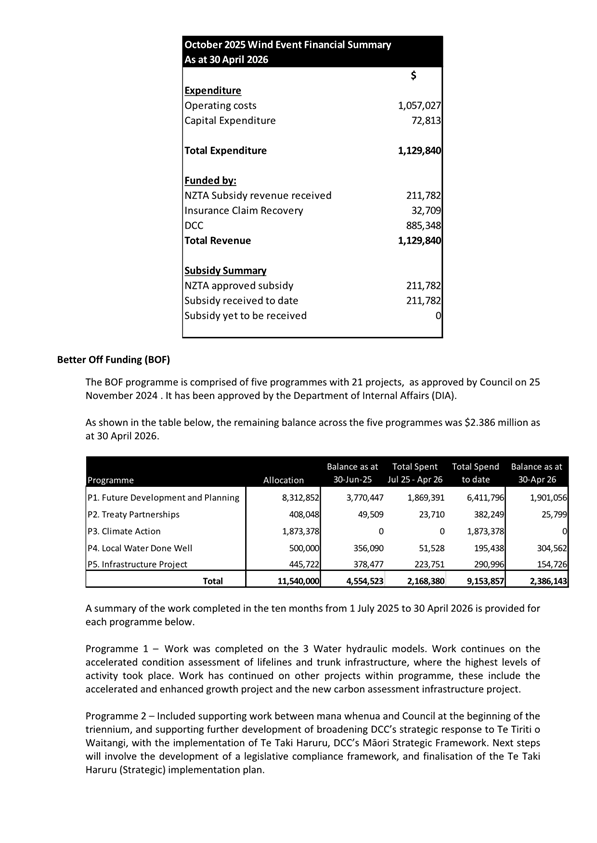
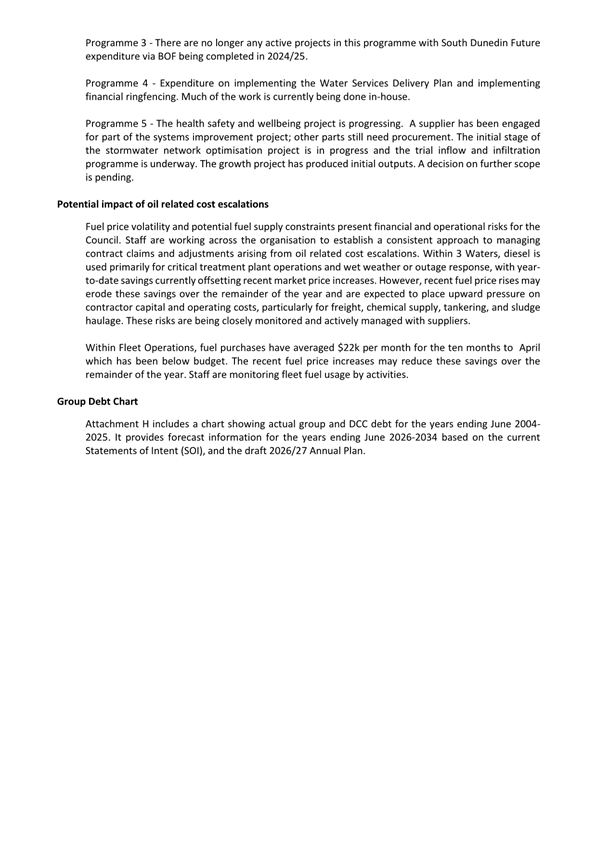
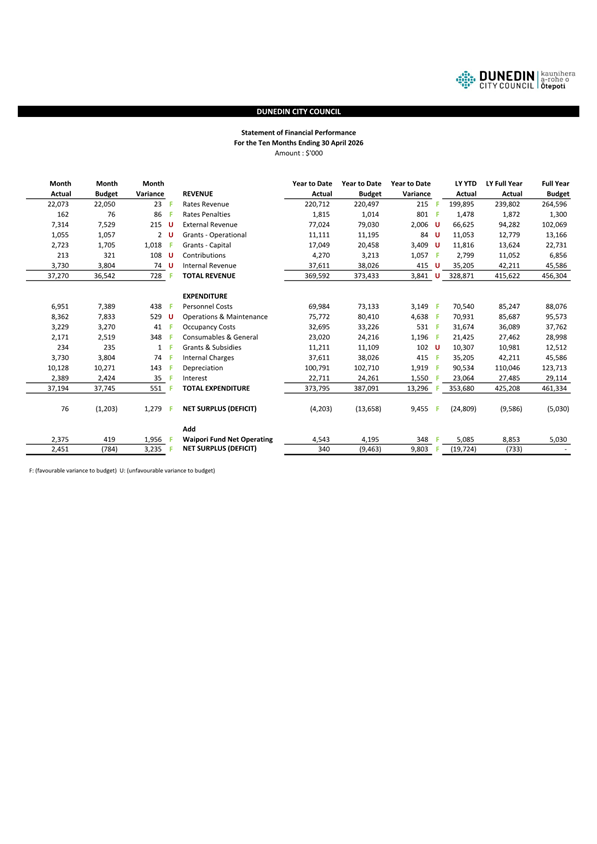
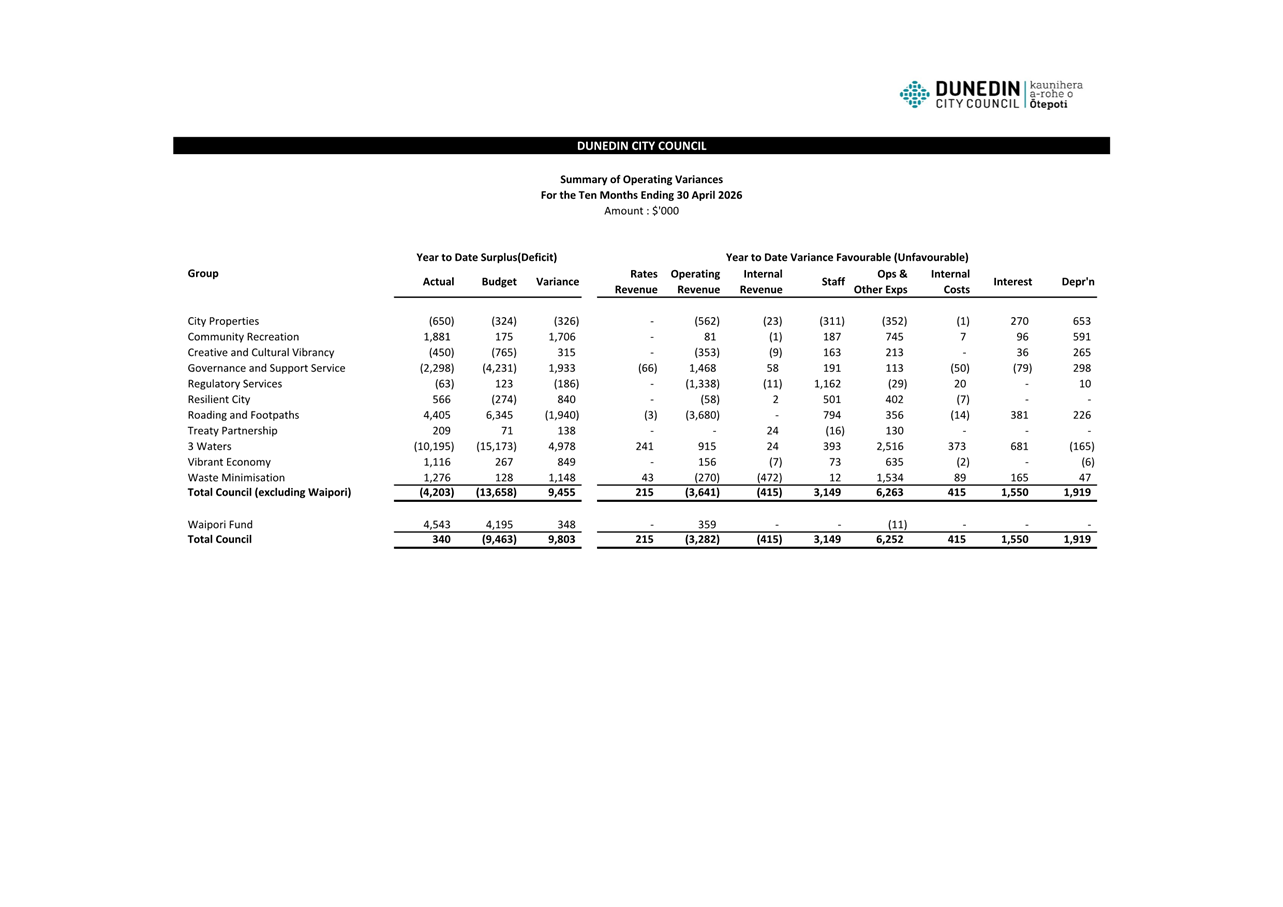
30 June 2026
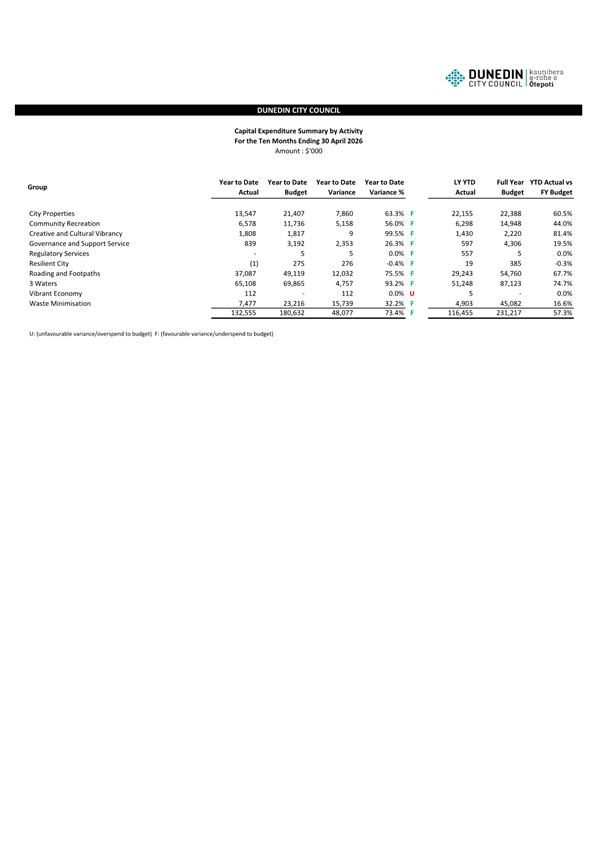
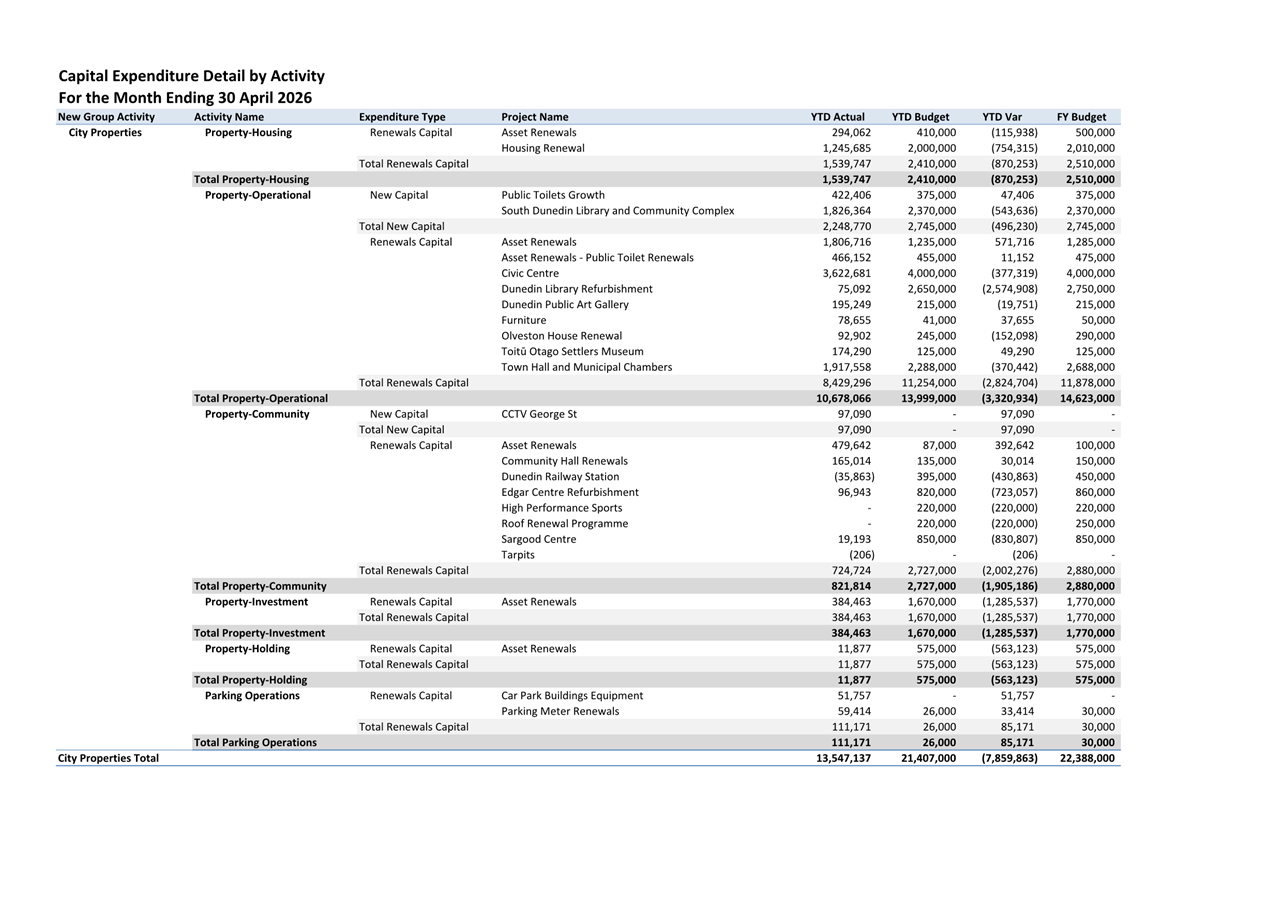
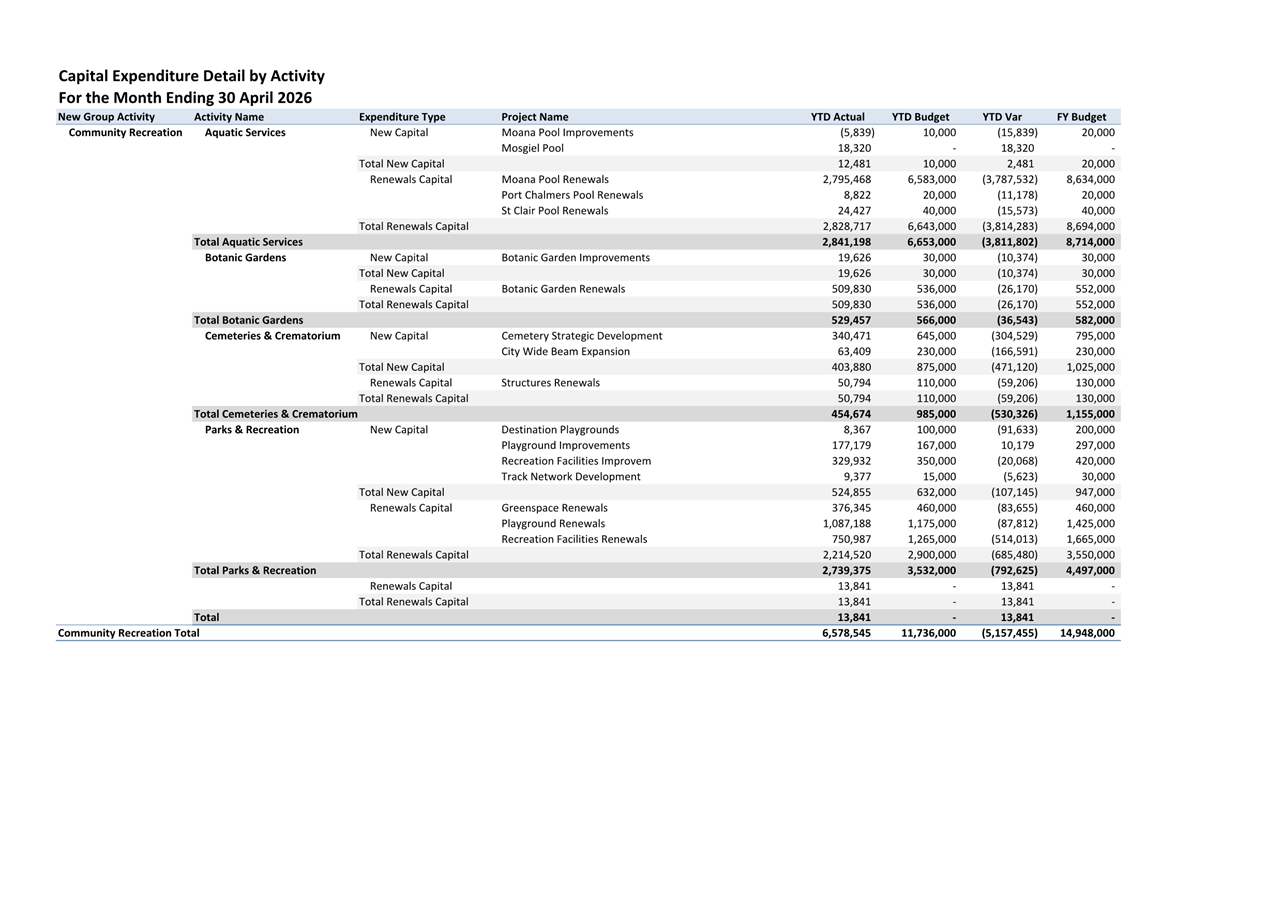
Time: 10:00
a.m.
Venue: Council
Chamber, Dunedin Public Art Gallery, The Octagon, Dunedin
Sandy Graham
Audit, Risk and Assurance Committee
PUBLIC AGENDA
|
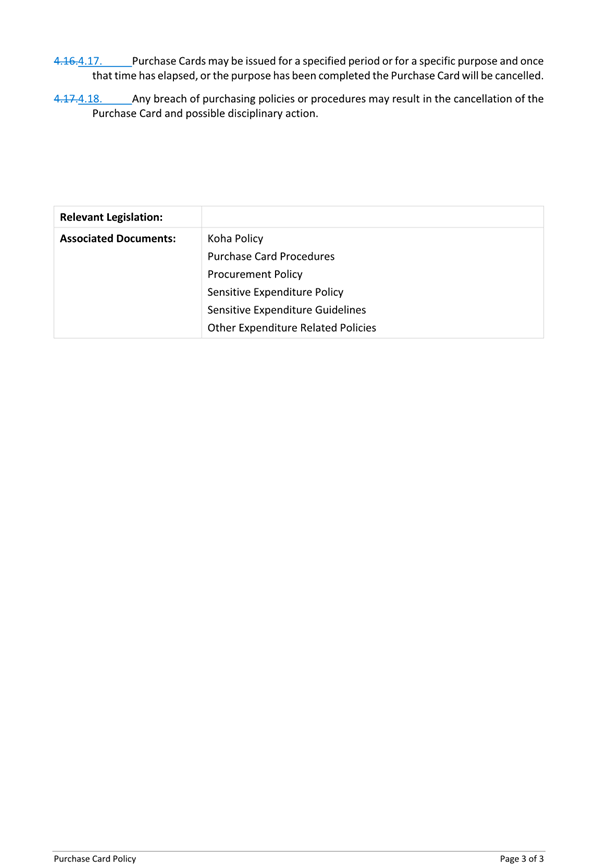
Chairperson
|
Mr Bruce Robertson
|
|
|
Deputy Chairperson
|
Ms Rachael Dean
|
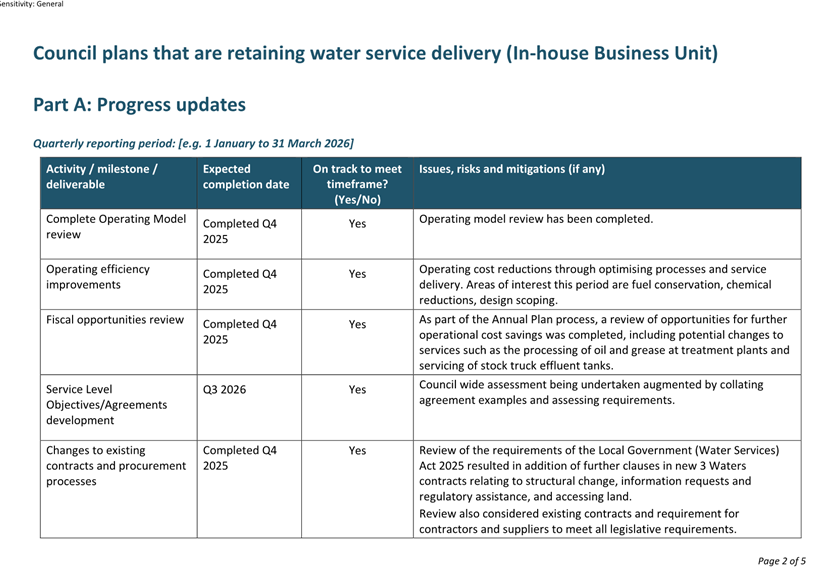
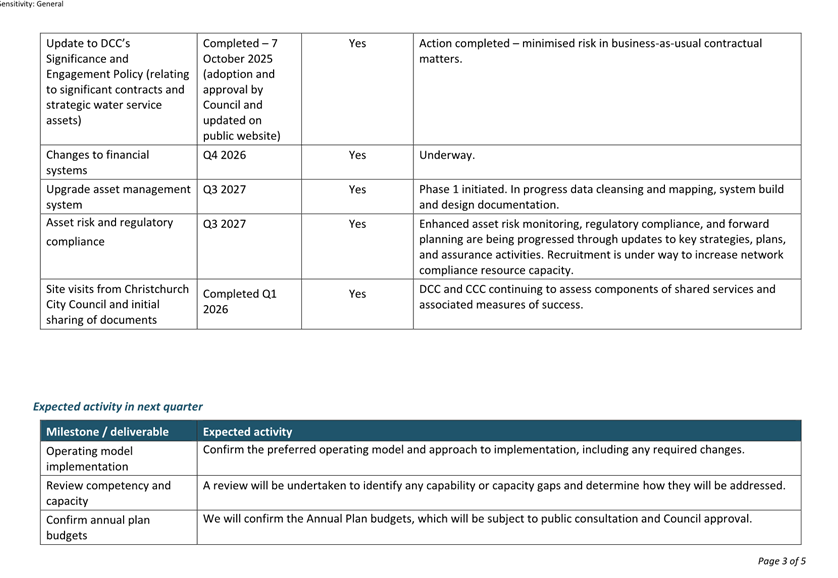
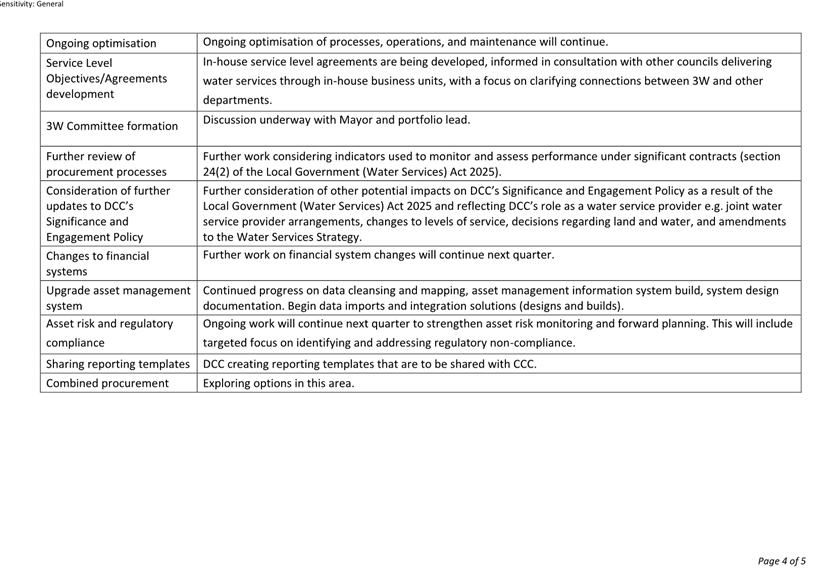
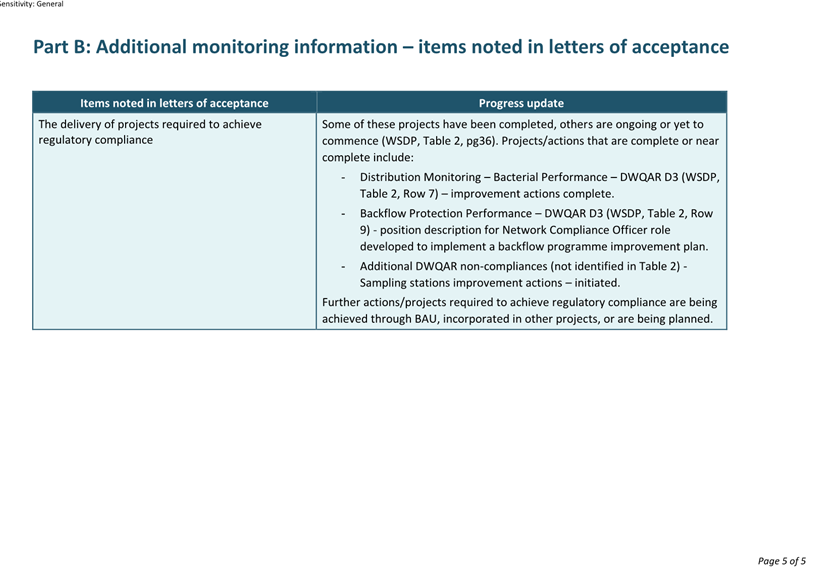
|
|
Members
|
Mayor Sophie Barker
|
Cr John Chambers
|
|
|
Cr Cherry Lucas
|
Cr Andrew Simms
|
|
|
Cr Lee Vandervis
|
|
Senior Officer Carolyn
Allan, Chief Financial Officer
Governance Support Officer Jean
Cockram
Jean Cockram
Governance Support Officer
Telephone: 03 477 4000
jean.cockram@dcc.govt.nz
www.dunedin.govt.nz
Note: Reports
and recommendations contained in this agenda are not to be considered as
Council policy until adopted.
|
|
Audit, Risk and Assurance
Committee
30 June 2026
|
ITEM TABLE OF CONTENTS PAGE
1 Apologies 4
2 Confirmation
of Agenda 4
3 Declaration
of Interest 5
4 Confirmation
of Minutes 11
4.1 Audit, Risk and
Assurance Committee meeting - 27 March 2026 11
Part
A Reports (Committee has power to decide these matters)
5 Workplan
and General Matters Update Report - June 2026 23
6 Health,
Safety and Wellbeing Monthly report for April 2026 36
7 Financial
Report - Period ended 30 April 2026 57
8 Waipori
Fund - Quarter Ending 31 March 2026 87
9 DCC
Policy Update Report 95
Resolution to Exclude the Public 108
|
|
Audit, Risk and Assurance
Committee
30 June 2026
|
1 Apologies
At the close of the agenda no
apologies had been received.
2 Confirmation
of agenda
Note:
Any additions must be approved by resolution with an explanation as to why they
cannot be delayed until a future meeting.
|
|
Audit, Risk and Assurance Committee
30 June 2026
|
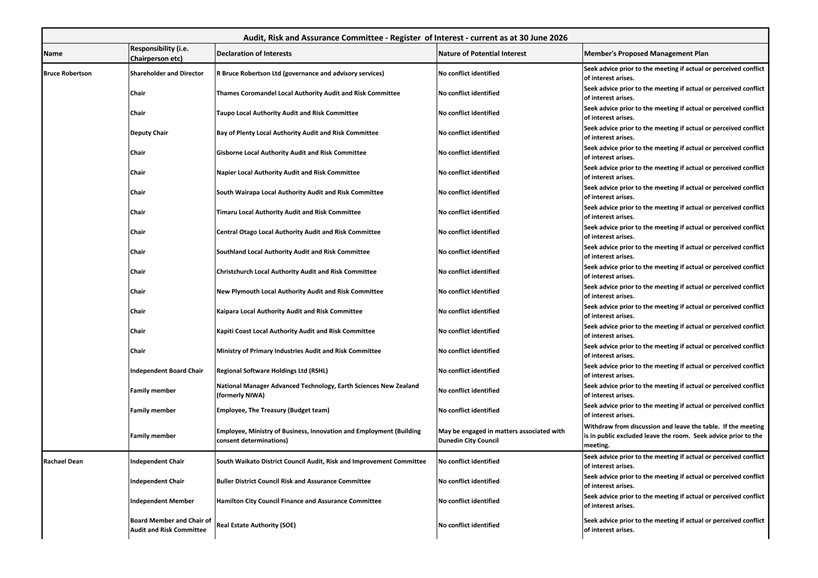
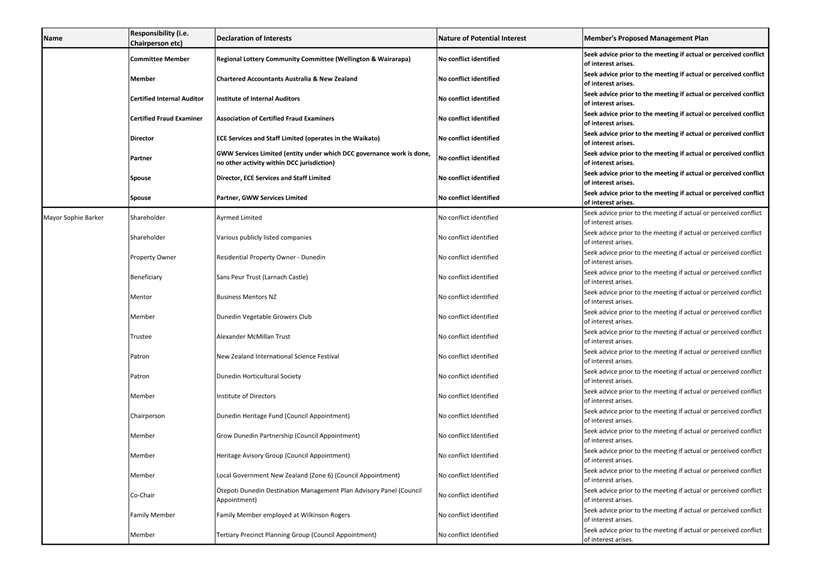
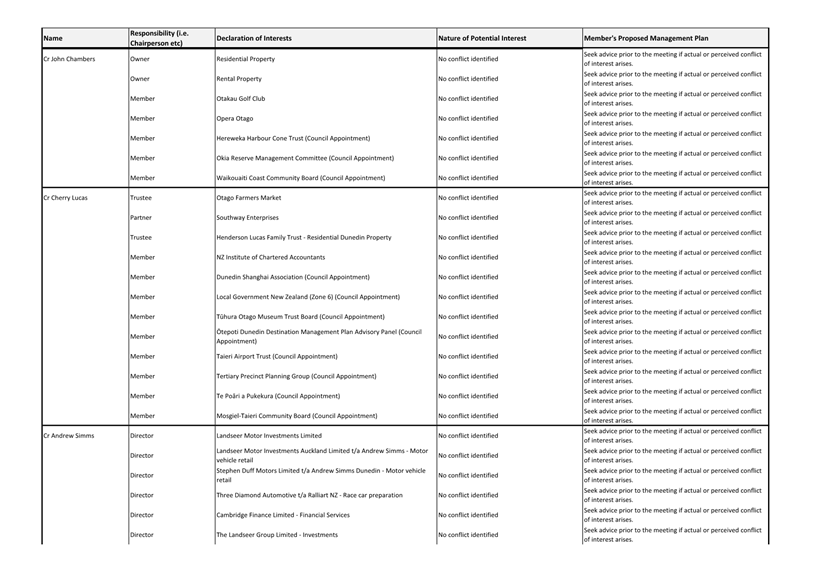
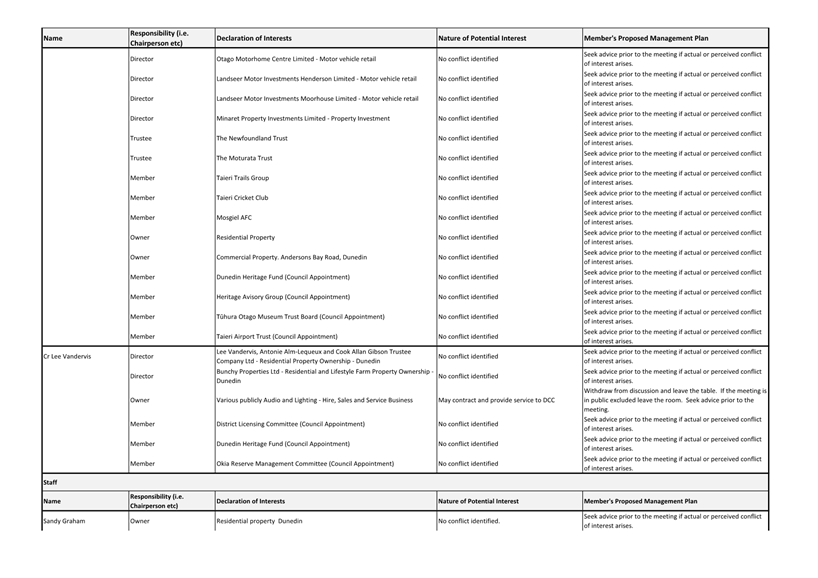
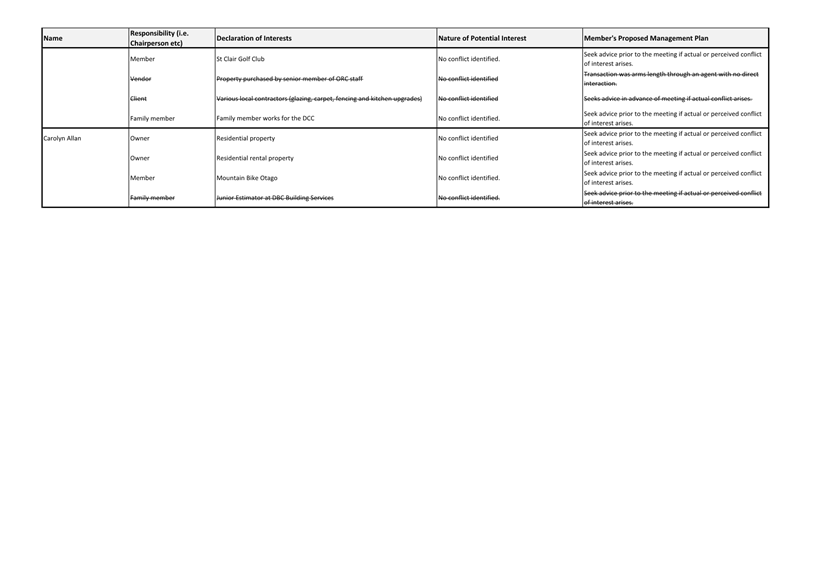
Declaration of Interest
EXECUTIVE SUMMARY
1. Members
are reminded of the need to stand aside from decision-making when a conflict
arises between their role as an independent or elected representative and any
private or other external interest they might have.
2. Elected
and Independent members are reminded to update their register
of interests as soon as practicable, including amending the register at this
meeting if necessary.
RECOMMENDATIONS
That the Committee:
a) Notes/Amends if
necessary the Elected or Independent Members' Interest Register attached as
Attachment A; and
b) Confirms/Amends the
proposed management plan for Elected or Independent Members' Interests.
Attachments
|
|
Title
|
Page
|
|
⇩a
|
ARAC Register of
Interests - June 2026
|
6
|
|
|
Audit, Risk and Assurance Committee
30 June 2026
|
|
|
Audit, Risk and Assurance Committee
30 June 2026
|
Confirmation
of Minutes
Audit,
Risk and Assurance Committee meeting - 27 March 2026
RECOMMENDATIONS
That the Committee:
a) Confirms the public
part of the minutes of the Audit, Risk and Assurance Committee meeting held on 27
March 2026 as a correct record.
Attachments
|
|
Title
|
Page
|
|
A⇩
|
Minutes of Audit, Risk
and Assurance Committee meeting held on 27 March 2026
|
12
|
|
|
Audit, Risk and
Assurance Committee
30 June 2026
|
Audit, Risk and Assurance Committee
MINUTES
Minutes of an ordinary
meeting of the Audit, Risk and Assurance Committee held in the Council Chamber,
Dunedin Public Art Gallery, The Octagon, Dunedin on Friday 27 March 2026,
commencing at 9:30 a.m.
PRESENT
|
Chairperson
|
Mr Bruce Robertson
|
|
|
Deputy Chairperson
|
Ms Rachael Dean
|
|
|
Members
|
Mayor Sophie Barker
|
Cr John Chambers
|
|
|
Cr Cherry Lucas
|
Cr Andrew Simms
|
|
|
Cr Lee Vandervis
|
|
|
IN ATTENDANCE
|
Sandy Graham (Chief Executive),
Carolyn Allan (Chief Financial Officer), Hayley Knight (Assurance Manager),
David Ward (General Manager 3 Waters, Property and Urban Development), Paul
Henderson (General Manager Corporate and Regulatory Services), Mike Costelloe
(General Manager, Arts, Culture and Economic Development), Richard Davey (Treasurer, Dunedin City Holdings Limited), Jane Pearce
(Health and Safety Manager), Tania Cribb (Risk Manager), Tony Nelmes (Project
Accountant), Councillor Doug Hall.
|
|
|
|
|
Governance Support Officer
|
Jean Cockram
|
|
1 Apologies
|
|
|
Mayor Sophie Barker gave apologies
for absence to attend another appointment at 1pm.
|
|
|
Moved (Mr Bruce Robertson/Cr Cherry Lucas):
That the Committee:
Accepts the apology
from Mayor Barker for absence.
Motion
carried (ARAAC/2026/001)
|
|
2 Confirmation
of agenda
|
|
|
Moved (Mr Bruce Robertson/Cr Cherry Lucas):
That the Committee:
Confirms the agenda with
the following alterations: a) Item C2 be taken at 1pm after the lunch break
to accommodate the availability of external representatives to speak to the
report; and b) the addition of a new item (C16 – Finance Workshop) to
be taken at the start of the confidential section of the agenda.
Motion
carried (ARAAC/2026/002)
|
3 Declarations
of interest
Members were
reminded of the need to stand aside from decision-making when a conflict arose
between their role as an elected representative and any private or other
external interest they might have.
It was noted that the Interests
Register would be updated with the interests of new independent members before
the next meeting. In the interim, Bruce Robertson declared an interest in the Central
Otago District Council Audit and Risk Committee and the MBIE Determinations
section. Rachael Dean declared an interest in the Buller and South Waikato
District Councils’ Risk Committees.
|
|
Moved (Cr Cherry Lucas/Mayor Sophie Barker):
That the Committee:
a) Amends the Elected or Independent Members' Interest
Register; and
b) Confirms the proposed management plan for
Elected or Independent Members' Interests.
Motion carried (ARAAC/2026/003)
|
4 Confirmation
of Minutes
|
4.1 Audit,
Risk and Assurance Committee meeting - 4 December 2025
|
|
|
Moved (Cr Cherry Lucas/Mayor Sophie Barker):
That the Committee:
Confirms the public part of the minutes of the
Audit, Risk and Assurance Committee meeting held on 4 December 2025 as a
correct record.
Motion
carried (ARAAC/2026/004)
|
Part
A Reports
|
5 ARAC
Workplan Update 2026-27
|
|
|
A report
from Civic provided an update on the Audit, Risk and Assurance Committee Work
Plan 2026-27, which had been continued from the last Committee and would be
further developed.
The Chief Financial Officer (Carolyn
Allan) and the Assurance Manager (Hayley Knight) spoke to the report and
responded to questions.
|
|
|
Moved (Cr Lee Vandervis/Cr Cherry Lucas):
That the Committee:
Notes
the Audit, Risk and Assurance Committee Workplan for 2026-27.
Motion
carried (ARAAC/2026/005)
|
|
6 General
Matters Update Report - March 2026
|
|
|
A report
from Finance provided updates on the progress of various matters that have
been noted by the Committee.
The Chief Financial Officer (Carolyn
Allan) and the Assurance Manager (Hayley Knight) spoke to the report and
responded to questions.
|
|
|
Moved (Cr Cherry Lucas/Mr Bruce Robertson):
That the Committee:
Notes the
Audit, Risk and Assurance Committee Updates Report – March 2026
Motion
carried (ARAAC/2026/006)
|
|
7 Health,
Safety and Wellbeing Monthly report for January 2026
|
|
|
A report
from Health and Safety provided the monthly Health, Safety and Wellbeing
update for January 2026 for the Committee’s information.
The Chief
Executive (Sandy Graham), General Manager 3 Waters, Property and Urban Design
(David Ward), and the Health and Safety Manager (Jane Pearce) spoke to the
report and responded to questions.
|
|
|
Moved (Cr Cherry Lucas/Mayor Sophie Barker):
That the Committee:
Notes
the monthly Health, Safety and Wellbeing report for January 2026.
Motion
carried (ARAAC/2026/007)
|
|
8 Financial
Report - Period ended 31 January 2026
|
|
|
A report
from Finance provided the financial results for the period ended 31 January
2026 and the financial position as at that date. It noted that the
report was presented to the Finance and Performance Committee meeting held on
Thursday 19 March 2026.
The Chief Financial Officer (Carolyn
Allan) spoke to the report and responded to questions.
|
|
|
Moved (Mr Bruce Robertson/Cr Lee Vandervis):
That the Committee:
Notes
the Financial
Performance for the period ended 31 January 2026 and the Financial Position
as at that date.
Motion
carried (ARAAC/2026/008)
|
|
9 Waipori
Fund - Quarter ending 31 December 2025
|
|
|
A report
from Dunedin City Treasury provided information on the results of the Waipori
Fund for the quarter ended 31 December 2025.
The Treasury Manager (Richard Davey)
spoke to the report and responded to questions.
|
|
|
Moved (Cr Cherry Lucas/Cr Lee Vandervis):
That the Committee:
Notes
the report from Dunedin
City Treasury Limited on the Waipori Fund for the quarter ended 31 December
2025.
Motion
carried (ARAAC/2026/009)
|
|
10 Financial
Strategy Compliance
|
|
|
A report
from Finance provided a summary of financial limits for rate increases and
debt. It noted that the purpose of the report was to monitor current forecast
measures against the limits.
The Chief Financial Officer (Carolyn
Allan) spoke to the report and responded to questions.
|
|
|
Moved (Mr Bruce Robertson/Cr Lee Vandervis):
That the Committee:
Notes the
Financial Strategy Compliance report.
Motion
carried (ARAAC/2026/010)
|
|
Resolution to Exclude the Public
|
|
Moved (Mr Bruce Robertson/Cr Cherry Lucas):
That the Committee:
Pursuant
to the provisions of the Local Government Official Information and Meetings
Act 1987, exclude the public from the following part of the proceedings of
this meeting namely:
|
General
subject of the matter to be considered
|
Reasons for
passing this resolution in relation to each matter
|
Ground(s) under
section 48(1) for the passing of this resolution
|
Reason for
Confidentiality
|
|
C1
Audit, Risk and Assurance Committee meeting – 4 December 2025 –
Public Excluded
|
S7(2)(h)
The withholding of
the information is necessary to enable the local authority to carry out,
without prejudice or disadvantage, commercial activities.
S7(2)(b)(ii)
The withholding of
the information is necessary to protect information where the making
available of the information would be likely unreasonably to prejudice the
commercial position of the person who supplied or who is the subject of the
information.
S7(2)(c)(i)
The withholding of
the information is necessary to protect information which is subject to an
obligation of confidence or which any person has been or could be compelled
to provide under the authority of any enactment, where the making available
of the information would be likely to prejudice the supply of similar
information or information from the same source and it is in the public
interest that such information should continue to be supplied.
S7(2)(b)(i)
The withholding of
the information is necessary to protect information where the making
available of the information would disclose a trade secret.
S7(2)(a)
The withholding of
the information is necessary to protect the privacy of natural persons,
including that of a deceased person.
|
.
|
|
|
C2
Audit Arrangements for the year ending 30 June 2026
|
S7(2)(i)
The withholding of
the information is necessary to enable the local authority to carry on,
without prejudice or disadvantage, negotiations (including commercial and
industrial negotiations).
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
|
|
C3
Treasury Risk Management Compliance Report
|
S7(2)(h)
The withholding of
the information is necessary to enable the local authority to carry out,
without prejudice or disadvantage, commercial activities.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
|
|
C4
Dunedin City Holdings Ltd - Update on Audit and Risk Activity
|
S7(2)(b)(ii)
The withholding of
the information is necessary to protect information where the making
available of the information would be likely unreasonably to prejudice the
commercial position of the person who supplied or who is the subject of the
information.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
|
|
C5
Internal Audit: Workplan Update
|
S7(2)(b)(i)
The withholding of
the information is necessary to protect information where the making
available of the information would disclose a trade secret.
S7(2)(c)(i)
The withholding of
the information is necessary to protect information which is subject to an
obligation of confidence or which any person has been or could be compelled
to provide under the authority of any enactment, where the making available
of the information would be likely to prejudice the supply of similar
information or information from the same source and it is in the public
interest that such information should continue to be supplied.
S7(2)(h)
The withholding of
the information is necessary to enable the local authority to carry out,
without prejudice or disadvantage, commercial activities.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
|
|
C6
Internal Audit Services Contract - Recommendation Report
|
S7(2)(b)(ii)
The withholding of
the information is necessary to protect information where the making
available of the information would be likely unreasonably to prejudice the
commercial position of the person who supplied or who is the subject of the
information.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
|
|
C7
Internal Audit: Recommendations and Actions Update
|
S7(2)(c)(i)
The withholding of
the information is necessary to protect information which is subject to an
obligation of confidence or which any person has been or could be compelled
to provide under the authority of any enactment, where the making available
of the information would be likely to prejudice the supply of similar
information or information from the same source and it is in the public
interest that such information should continue to be supplied.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
|
|
C8
Risk Assurance: Financial Management
|
S7(2)(h)
The withholding of
the information is necessary to enable the local authority to carry out,
without prejudice or disadvantage, commercial activities.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
The information in
this report is commercially sensitive..
|
|
C9
Risk Assurance: Integrity
|
S7(2)(a)
The withholding of
the information is necessary to protect the privacy of natural persons,
including that of a deceased person.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
The information in
this report is commercially sensitive.
|
|
C10
Risk Assurance: Cybersecurity
|
S7(2)(h)
The withholding of
the information is necessary to enable the local authority to carry out,
without prejudice or disadvantage, commercial activities.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
|
|
C11
Risk Management Update
|
S7(2)(h)
The withholding of
the information is necessary to enable the local authority to carry out,
without prejudice or disadvantage, commercial activities.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
|
|
C12
Government Reforms Update - March 2026
|
S7(2)(h)
The withholding of
the information is necessary to enable the local authority to carry out,
without prejudice or disadvantage, commercial activities.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
|
|
C13
Legal Compliance Survey 2024/25 - Corrective Actions Progress
|
S7(2)(c)(i)
The withholding of
the information is necessary to protect information which is subject to an
obligation of confidence or which any person has been or could be compelled
to provide under the authority of any enactment, where the making available
of the information would be likely to prejudice the supply of similar
information or information from the same source and it is in the public
interest that such information should continue to be supplied.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
|
|
C14
Legal Matters
|
S7(2)(g)
The withholding of
the information is necessary to maintain legal professional privilege.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
|
|
C15
Investigation Register - March 2026
|
S7(2)(a)
The withholding of
the information is necessary to protect the privacy of natural persons,
including that of a deceased person.
S7(2)(c)(i)
The withholding of
the information is necessary to protect information which is subject to an
obligation of confidence or which any person has been or could be compelled
to provide under the authority of any enactment, where the making available
of the information would be likely to prejudice the supply of similar
information or information from the same source and it is in the public
interest that such information should continue to be supplied.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
|
This resolution is made in
reliance on Section 48(1)(a) of the Local Government Official Information and
Meetings Act 1987, and the particular interest or interests protected by
Section 6 or Section 7 of that Act, or Section 6 or Section 7 or Section 9 of
the Official Information Act 1982, as the case may require, which would be
prejudiced by the holding of the whole or the relevant part of the
proceedings of the meeting in public are as shown above after each item.
Motion carried
(ARAAC/2026/011)
|
The meeting adjourned at 10.54 am and
reconvened in non-public at 11.09 am.
The meeting concluded at 3.04 pm.
..............................................
CHAIRPERSON
|
|
Audit, Risk and Assurance Committee
30 June 2026
|
Part
A Reports
Workplan and General Matters Update Report - June 2026
Department: Finance and Civic
EXECUTIVE SUMMARY
1 This
report provides the workplan and updates on the progress of various matters for
the Audit, Risk and Assurance Committee.
RECOMMENDATIONS
That the Committee:
a) Notes the Workplan and General Matters Update Report – June
2026
b) Notes the Audit, Risk
and Assurance Committee Workplan (Attachment A)
DISCUSSION
Audit, Risk and Assurance
Committee Workplan
2 This
report provides a copy of the Audit, Risk and Assurance Committee (ARAC)
Workplan June 2026 which has been aligned to work programme scheduling and
decision making (Attachment A).
3 Please
note that the items without ticks shown have not been scheduled for action.
2026/27 Annual Plan
4 Work
on the development of the Annual Plan 2026/27 is coming to an end.
5 Community
consultation ran from 30 March to 29 April 2026. Those who submitted as part of
the consultation had an opportunity to speak directly to elected members at the
Council meeting on 13 May 2026. Councillors heard directly from submitters on
30 submissions.
6 Council
considered community feedback and deliberated on the draft Annual Plan at
Council budget update meetings on 27 and 29 May, and 4 June 2026.
7 At
the time of writing this report, staff are finalising the Annual Plan document,
which is scheduled to be formally adopted by Council at its 25 June 2026
meeting. This is within the legislative deadline of 30 June 2026, as required
by the Local Government Act 2002.
8 The
Annual Plan 2026/27 will be made publicly available on the DCC website within
one month of adoption.
30 June 2026 Annual Report
9 Planning
and preparation is well-advanced for the year ending 30 June 2026 Annual
Report. As previously noted, recommended improvements to the development of
future Annual Reports are as follows:
a) 3
Waters valuations are completed as at 31 March. Over the past four years, there
have been recurring issues with valuations, and completing them three months
earlier than usual provides a buffer to address any potential challenges.
b) More
detail is included on the performance of each Council-Controlled Organisation
(CCO). While the primary focus of the Annual Report is the performance of the
DCC, more supporting information on CCOs would provide helpful context to a
reader.
c) The
timeline for the development of the Annual Report is incrementally brought
forward each year, in consultation with Dunedin City Holdings Limited and Audit
NZ. This will ensure that the 2027/28 Annual Report can be adopted ahead of the
next local government elections.
10 Council’s
3 Waters assets are in the process of being valued as at 31 March 2026. A
competitive tender process for the valuation work was completed, and Pattle
Delamore Partners (PDP) were appointed as the new valuers. Work commenced early
April and has been progressing in line with staff expectations. The DCC waters
valuation team is in the final stages of reviewing the final draft report and
providing feedback to PDP before the final report is issued. Currently, the
valuation is on track to be completed ahead of Audit NZ commencing their review
on the 21 July 2026.
11 This year
DCC has 3 valuations occurring which are 3 Waters, Roading and Investment
Property. As commented on above, the 3 Water valuation has already commenced
with a date of 31 March. The two other valuations will commence on 30 June
2026. It is also our understanding that Audit NZ plan to engage a peer reviewer
for the Investment Property valuation this year.
12 Staff met
with Audit New Zealand in mid-March to discuss an audit plan for the 2025/26
Annual Report. In line with recommended improvements above, the adoption of the
Annual Report has been moved a week earlier than in 2025, and will be adopted
at an additional Council meeting on 23 October 2026.
13 Staff will
provide an update on valuations and key audit focus areas to the 10 September
2026 ARAC meeting. An ARAC meeting is scheduled on 21 October 2026 to review
the Annual Report prior to adoption by Council on 23 October 2026.
10 Year Plan 2027-37
14 Work on the
development of the 10 year plan 2027-37 (the 10 year plan) continues.
15 A Finance
and Performance Committee workshop was held on 15 June 2026, and started a
discussion with Councillors on the development of the Financial Strategy and
Infrastructure Strategy for the 10 year plan. Some of the planned work that was
discussed included:
a) A
review of fees and charges alongside the review of the Revenue and Financial
Policy.
b) Categorising
operational expenditure as either controllable or uncontrollable, and then
identifying ‘controllable’ operational savings, with a current aim
of $10 million.
c) Assessing
the impact on Levels of Service from potential operational savings.
d) Developing
options on ways to reduce new and historical debt.
e) Categorising
non 3 waters capital expenditure as either discretionary or non-discretionary,
and then presenting all discretionary capital expenditure to Council in options
reports, with only agreed projects being included in the draft budget.
f) Developing
prioritisation criteria for ‘discretionary’ capital expenditure.
16 Another
workshop with Councillors is being considered for July 2026, though is not
confirmed, in order to get further direction and to discuss more specific
Councillor suggestions relating to the draft 10 year plan budgets. Further
workshops will be scheduled with Councillors to discuss a range of topics that
pertain to the 10 year plan.
17 A project
plan has been developed, with a high level summary expected to be presented to
Council in July 2026.
18 Budget
options reports will be incrementally presented to Councillors, with decisions
built into the draft 10 year plan budgets, and then presented as a whole at the
Council meeting on 7-10 December 2026.
19 Implementation
of a budgeting system is underway, with implementation estimated within ten
weeks. Having this system in place will improve the budgeting process for the
upcoming 10 year plan as it will allow the finance team to move away from
spreadsheet based budgeting.
Water Services Strategy
20 The Water
Services Strategy is being developed in parallel with Council’s 10 Year
Plan 2027-37. It is legislatively required to be adopted by Council by 30 June
2027.
21 Under the
Local Government (Water Services) Act 2025 (LGWSA), the Council is required to adopt
a water services strategy every three years.
22 Previously,
water services information was included as part of a council’s Long Term
Plan (i.e., a 10 year plan or 9 year plan), where relevant. However, from 1
July 2027, detailed water services information must not be included in the 10
year plan but must instead be covered in a Water Services Strategy document.
Waters
Services Delivery Plan (Local Water Done Well)
23 The Water
Services Delivery Plan - Implementation Plan has progressed with several tasks
completed or underway.
24 The project
control group is meeting monthly and includes two members from ELT (CFO, GM 3
Waters, Property and Urban Development), the PCG will be responsible for
ensuring the programme of work is on track. The largest impacts from this work
will be on the 3 Waters and Finance departments.
25 First
reporting to DIA on implementation plan progress was sent at the end of April
and covered the period from January to March 2025 (Attachment C). The next
quarterly report is due at the end of July covering the period 1 April to 30
June.
26 Key dates:
April 2026-June 2027 establishment phase; by 1 July 2027 in-house business unit
to be fully operational; 30 June 2028 demonstrate long-term financial
sustainability.
OPTIONS
27 This is a
noting report so there are no options.
Signatories
|
Author:
|
Hayley Knight - Assurance Manager
Janet Fraser - Corporate Planner
Lauren Mead - Senior Financial Accountant
|
|
Authoriser:
|
Carolyn Allan - Chief Financial Officer
|
Attachments
|
|
Title
|
Page
|
|
⇩a
|
ARAC Workplan - June
2026
|
29
|
|
⇩b
|
Water Services Delivery
Plan Implementation - DIA Quarterly Monitoring
Report 1 Jan - 31
March 2026
|
31
|
|
SUMMARY OF CONSIDERATIONS
|
|
Fit with purpose of Local Government
This report provides an update on various
audit, risk and assurance related matters.
|
|
Fit with strategic framework
|
|
Contributes
|
Detracts
|
Not applicable
|
|
Social Wellbeing Strategy
|
✔
|
☐
|
☐
|
|
Economic Development Strategy
|
✔
|
☐
|
☐
|
|
Environment Strategy
|
✔
|
☐
|
☐
|
|
Arts and Culture Strategy
|
✔
|
☐
|
☐
|
|
3 Waters Strategy
|
✔
|
☐
|
☐
|
|
Future Development Strategy
|
✔
|
☐
|
☐
|
|
Integrated Transport Strategy
|
✔
|
☐
|
☐
|
|
Parks and Recreation Strategy
|
✔
|
☐
|
☐
|
|
Other strategic projects/policies/plans
|
☐
|
☐
|
✔
|
This report provides an update on the progress made by
Council to deliver upon the activities identified by the Audit, Risk and
Assurance Committee, which is a regulatory function and considered good
quality and cost effective.
|
|
Māori Impact Statement
There are no known impacts for mana whenua.
|
|
Sustainability
There are no implications for sustainability.
|
|
Zero carbon
There
are no implications for zero carbon.
|
|
LTP/Annual Plan / Financial Strategy /Infrastructure
Strategy
There are no implications.
|
|
Financial considerations
No financial implications have been identified.
|
|
Significance
This report is rated low under the Council’s
Significance and Engagement Policy.
|
|
Engagement – external
No external engagement has been undertaken.
|
|
Engagement - internal
Activities noted herein include cross Council engagement
and collaboration.
|
|
Risks: Legal / Health and Safety etc.
No risks have been identified.
|
|
Conflict of Interest
There are no conflicts of interest identified.
|
|
Community Boards
There have been no implications for Community Boards
identified.
|
|
|
Audit, Risk and Assurance Committee
30 June 2026
|
|
|
Audit, Risk and Assurance Committee
30 June 2026
|
|
|
Audit, Risk and Assurance Committee
30 June 2026
|
Health, Safety and Wellbeing Monthly report for April 2026
Department: Health and Safety
EXECUTIVE SUMMARY
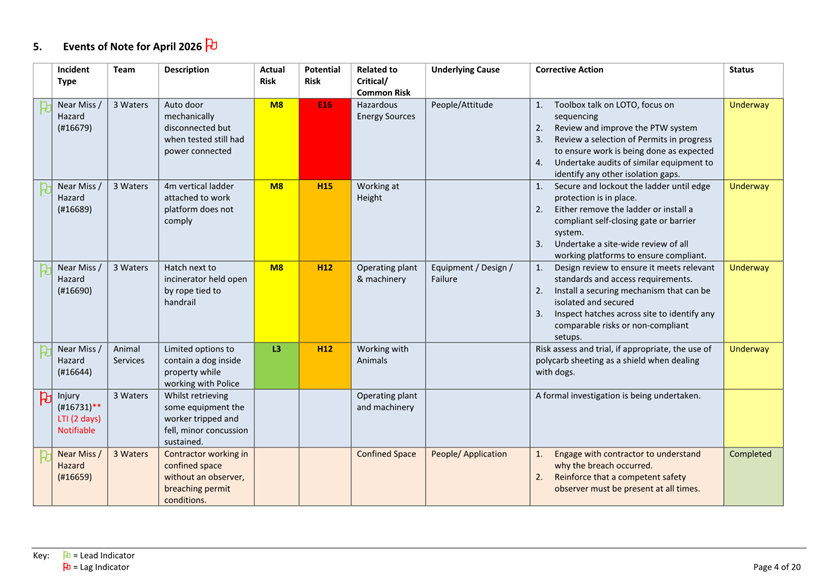
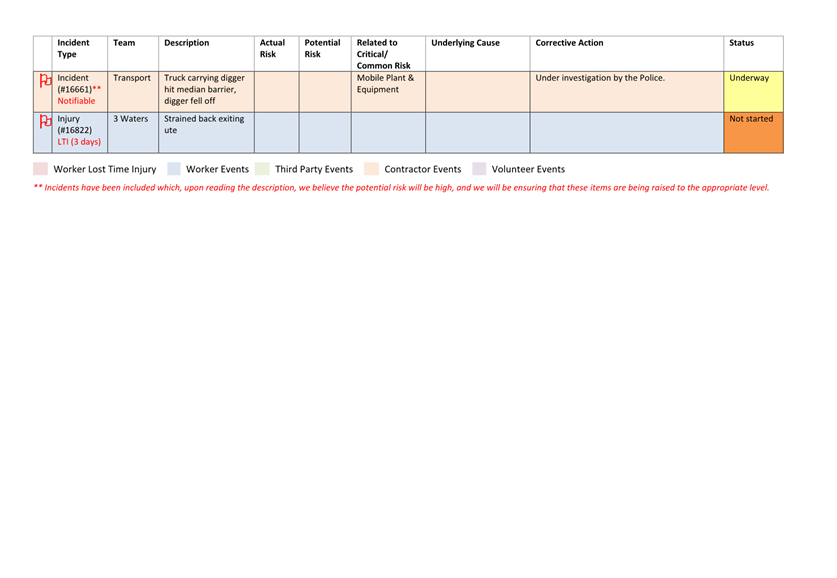
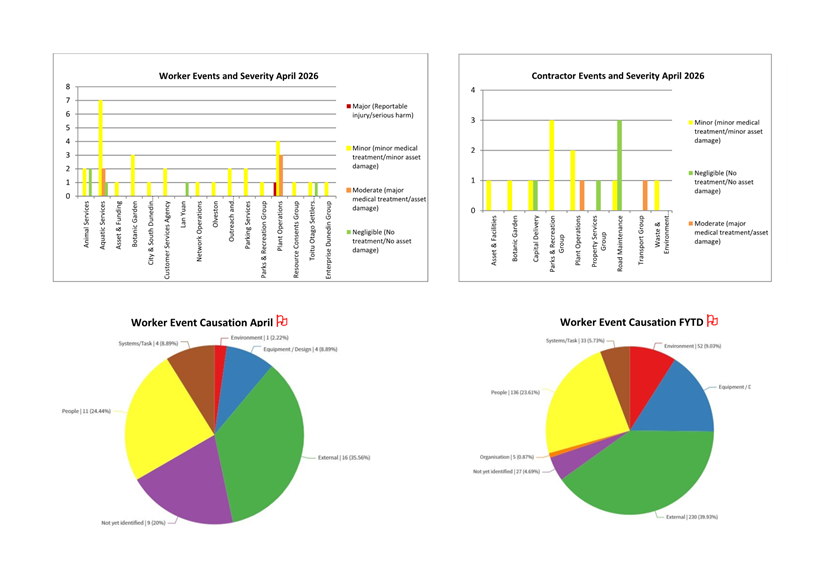
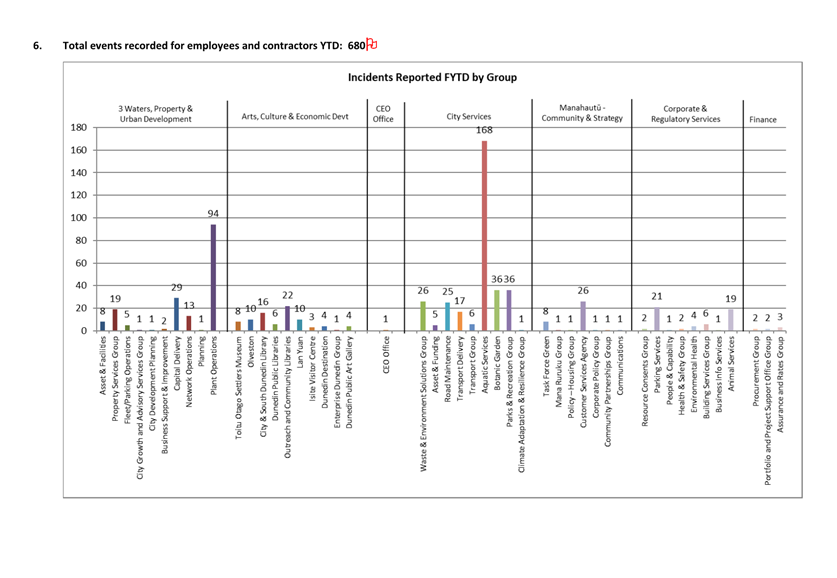
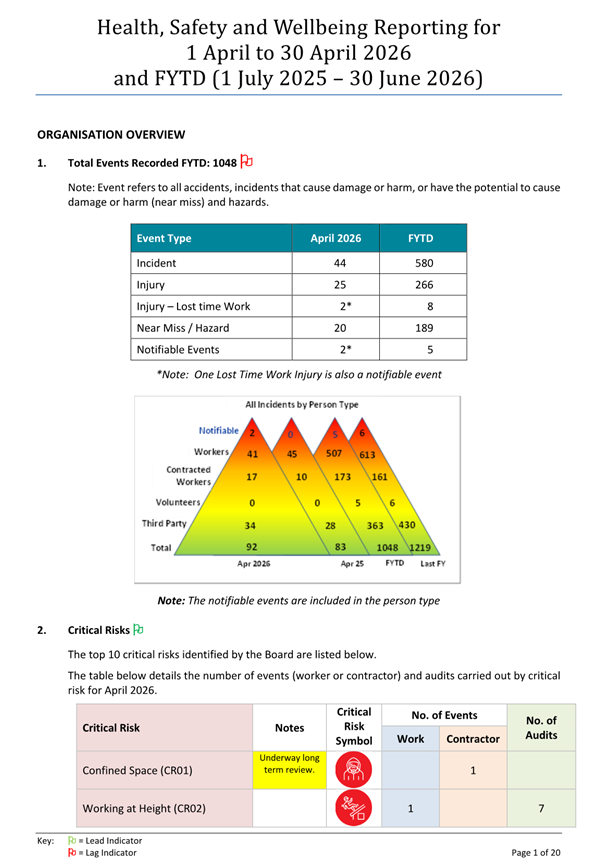
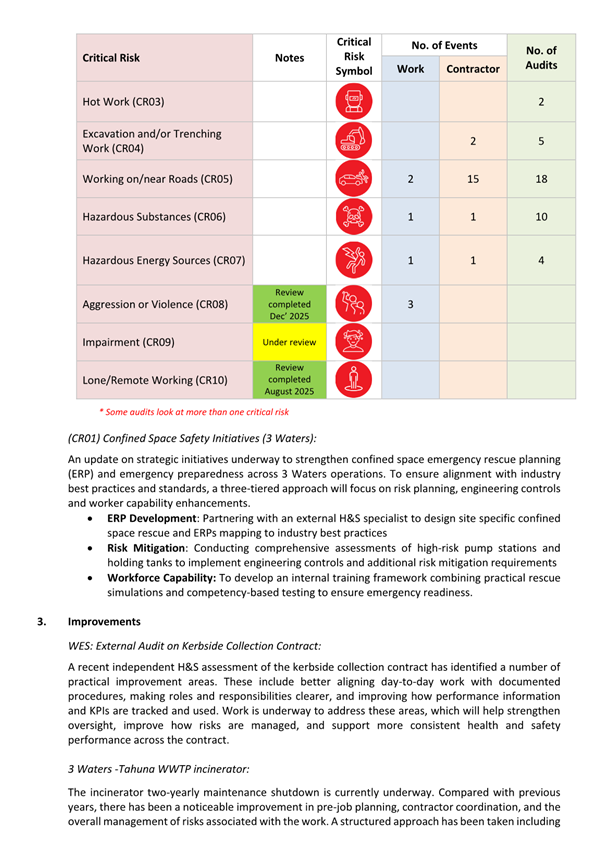
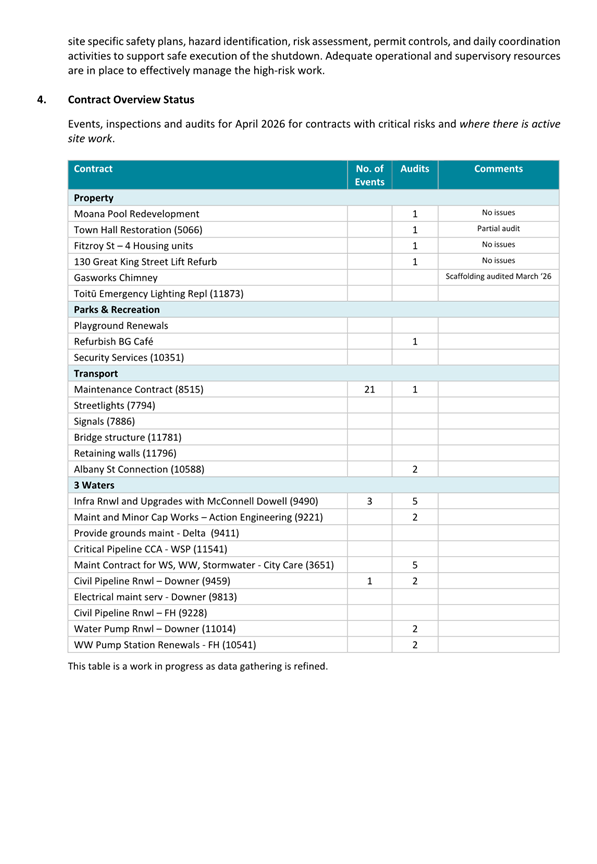
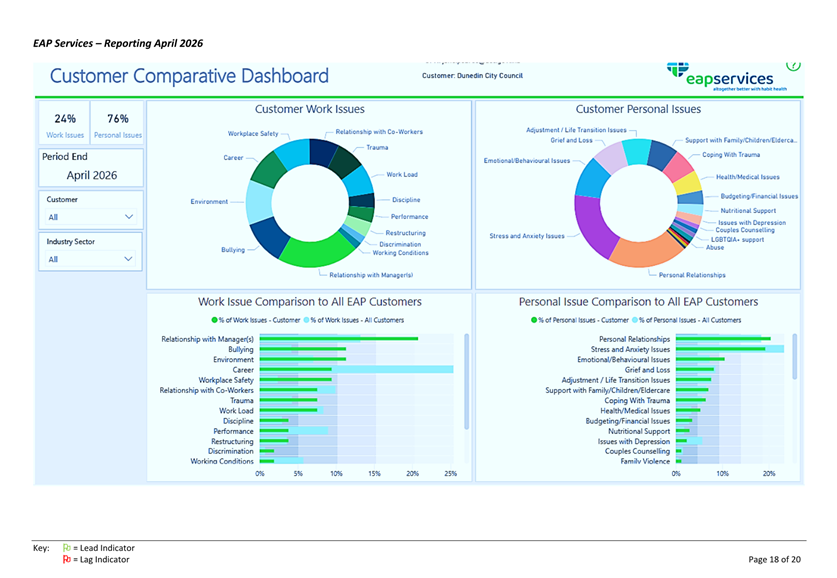
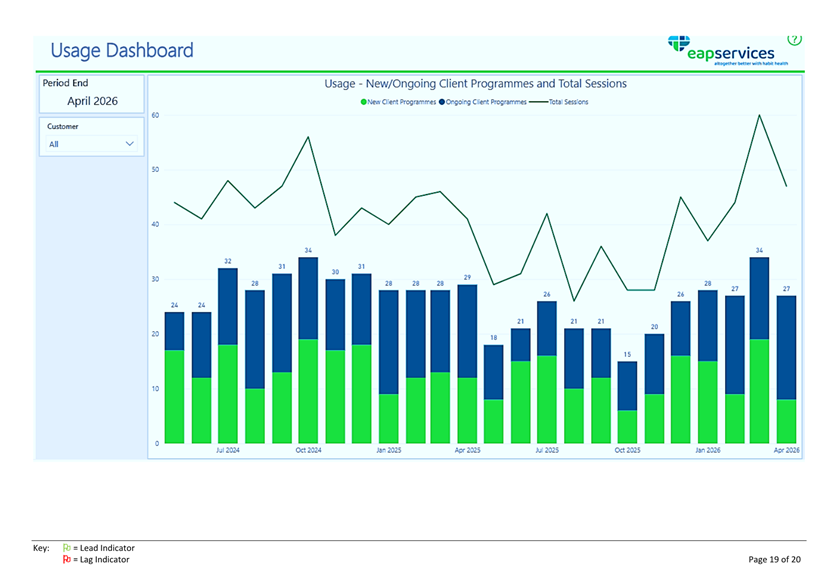
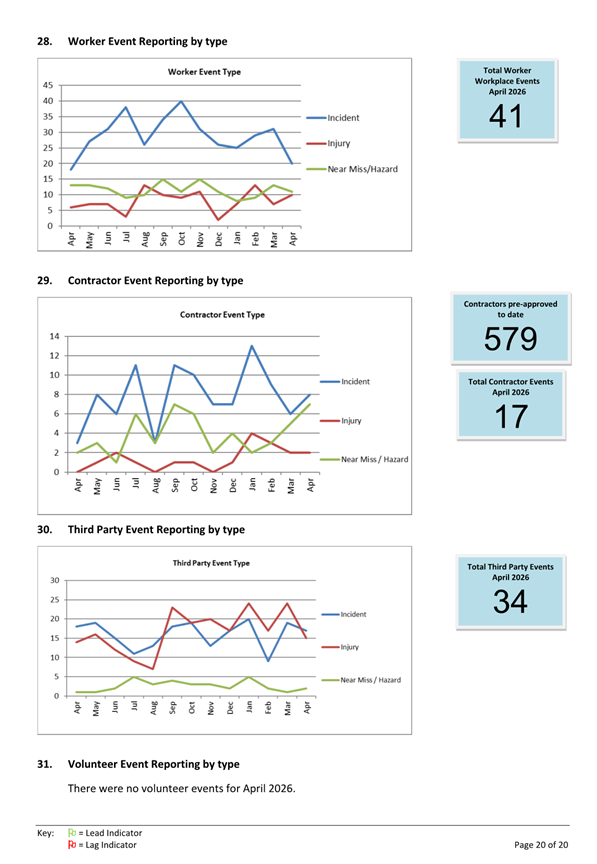
1 The
monthly Health, Safety and Wellbeing report for April 2026 is attached for
consideration.
RECOMMENDATIONS
That the Committee:
a) Notes the monthly
Health, Safety and Wellbeing report for April 2026.
Signatories
|
Author:
|
Jane Pearce - Health and Safety Manager
|
|
Authoriser:
|
David Ward - General Manager, 3 Waters, Property and Urban
Development
|
Attachments
|
|
Title
|
Page
|
|
⇩a
|
HSW report for April
2026
|
37
|
|
|
Audit, Risk and Assurance Committee
30 June 2026
|
|
|
Audit, Risk and Assurance Committee
30 June 2026
|
Financial Report - Period ended 30 April 2026
Department: Finance
EXECUTIVE SUMMARY
1 This
report provides the financial results for the period ended 30 April 2026 and
the financial position as at that date. This report is due to be presented to
Council on 25 June 2026.
2 As
this is an administrative report only, there are no options or Summary of
Considerations.
RECOMMENDATIONS
That the Committee:
a) Notes the Financial
Performance for the period ended 30 April 2026 and the Financial Position as at
that date.
BACKGROUND
3 This
report attaches a financial update and financial statements for the period
ended 30 April 2026.
DISCUSSION
4 The
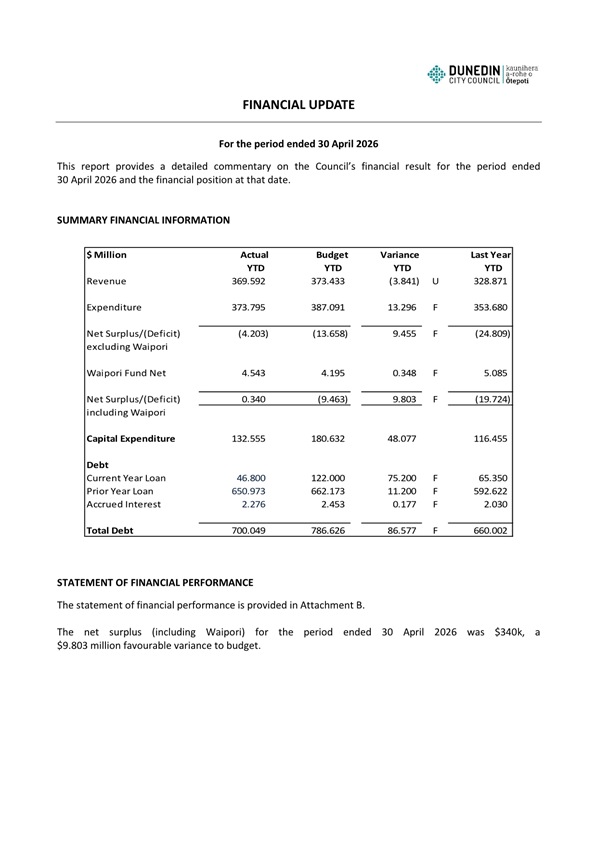
net deficit (including Waipori) for the period ended 30 April 2026 was $340k, a
$9.803 million favourable variance to budget. A detailed commentary is provided in Attachment A (Financial Update). In summary, the
following variances were recorded:
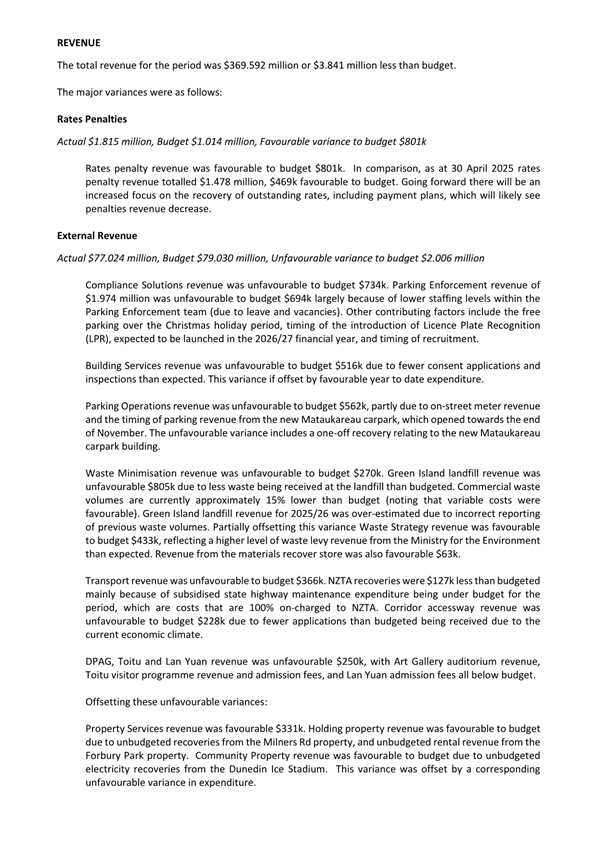
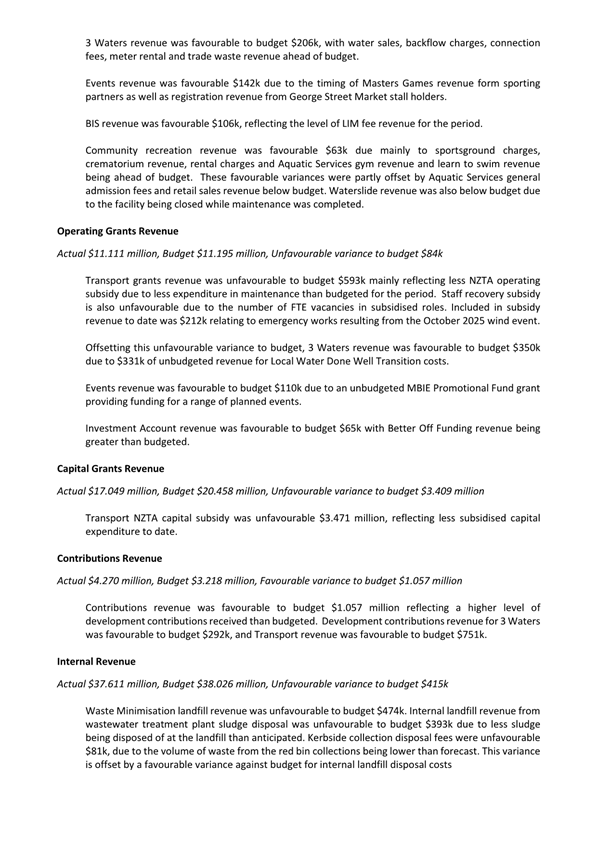
a) Revenue
was $369.592 million for the period, or $3.841 million unfavourable to budget.
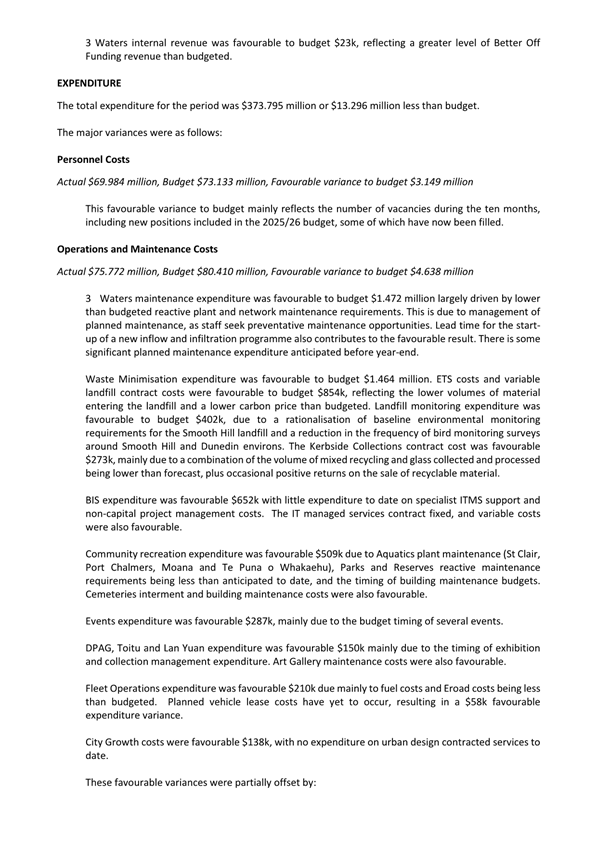
b) Expenditure
was $373.795 million for the period, or $13.296 million favourable to budget.
c) The
Waipori Fund has reported a net operating surplus for the period of $4.543
million, $348k favourable to budget.
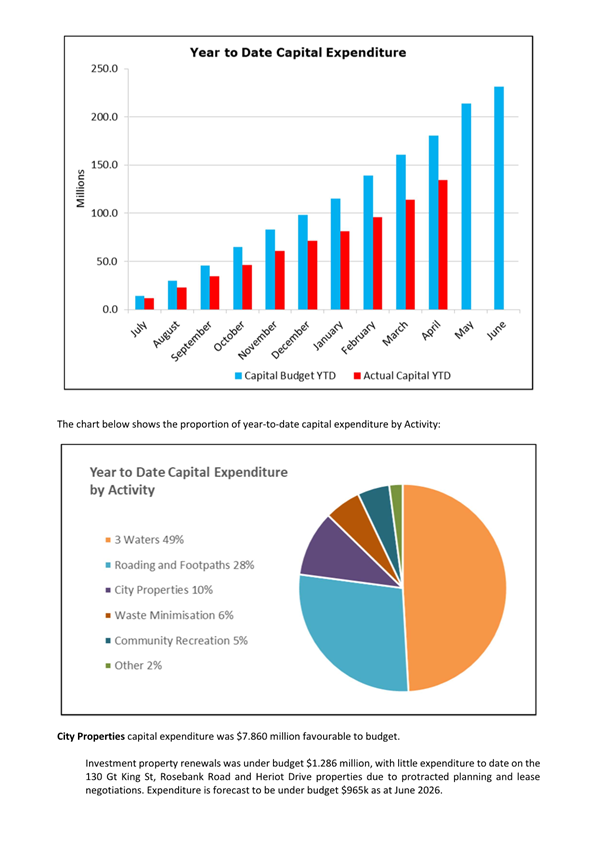
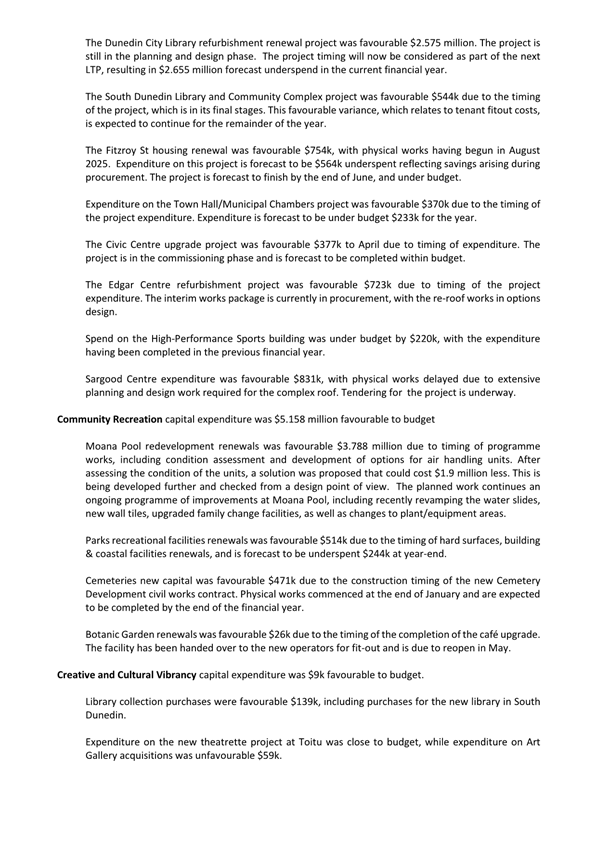
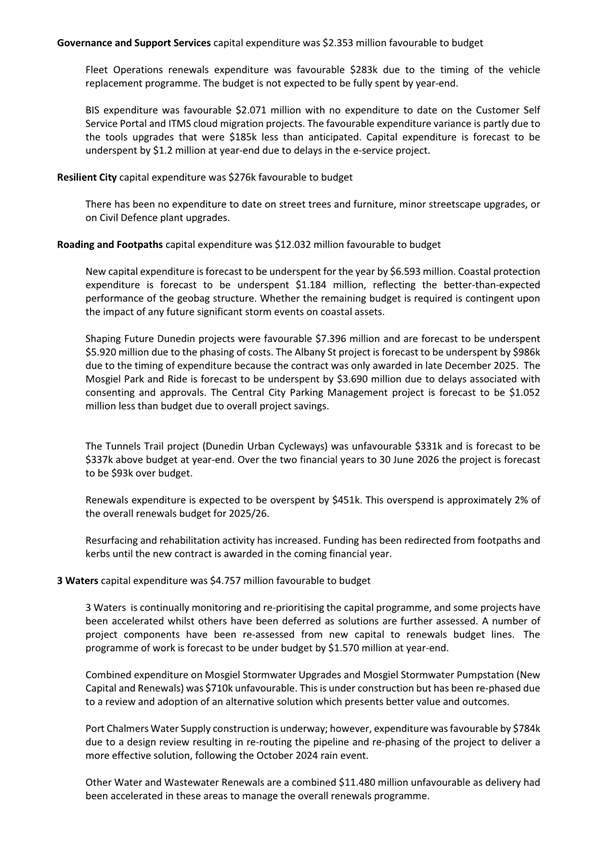
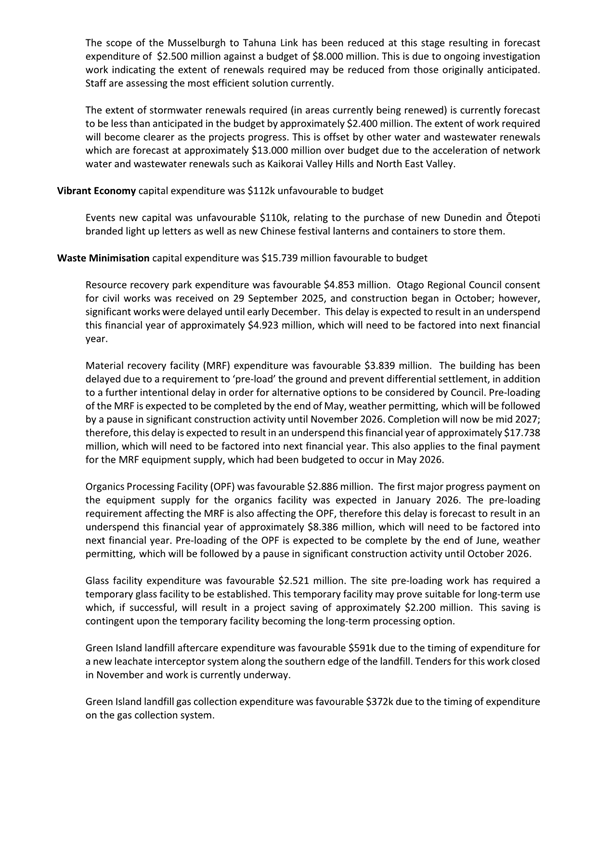
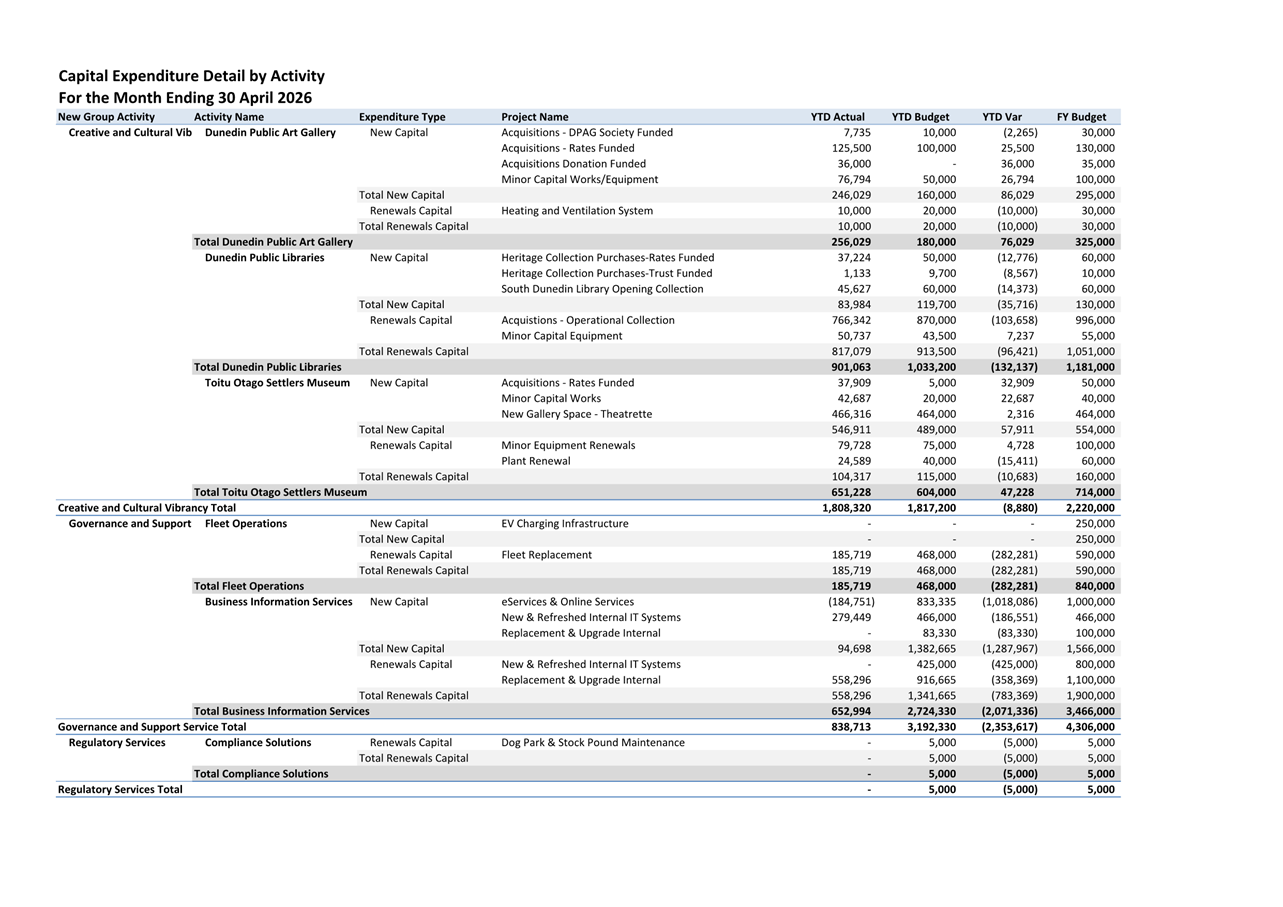
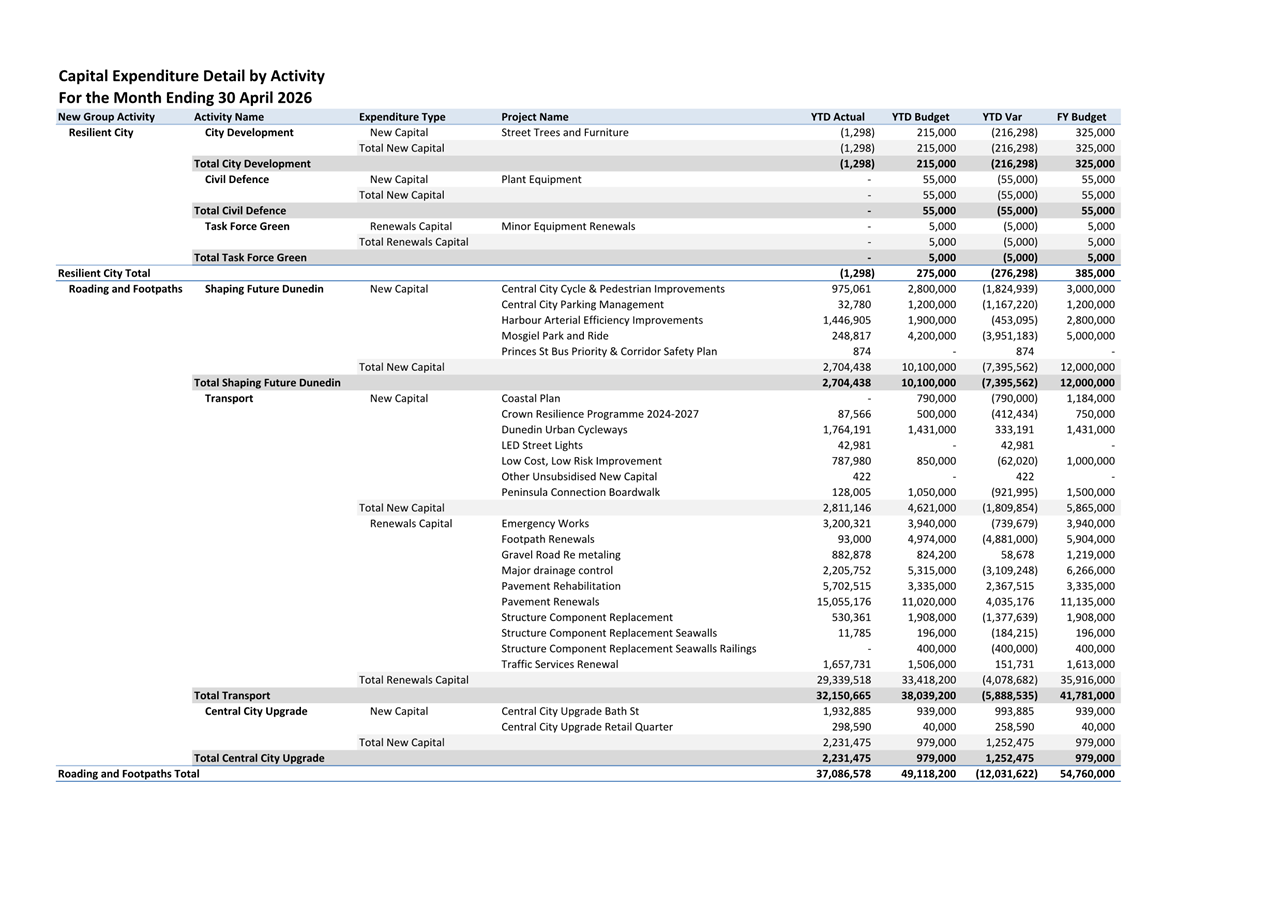
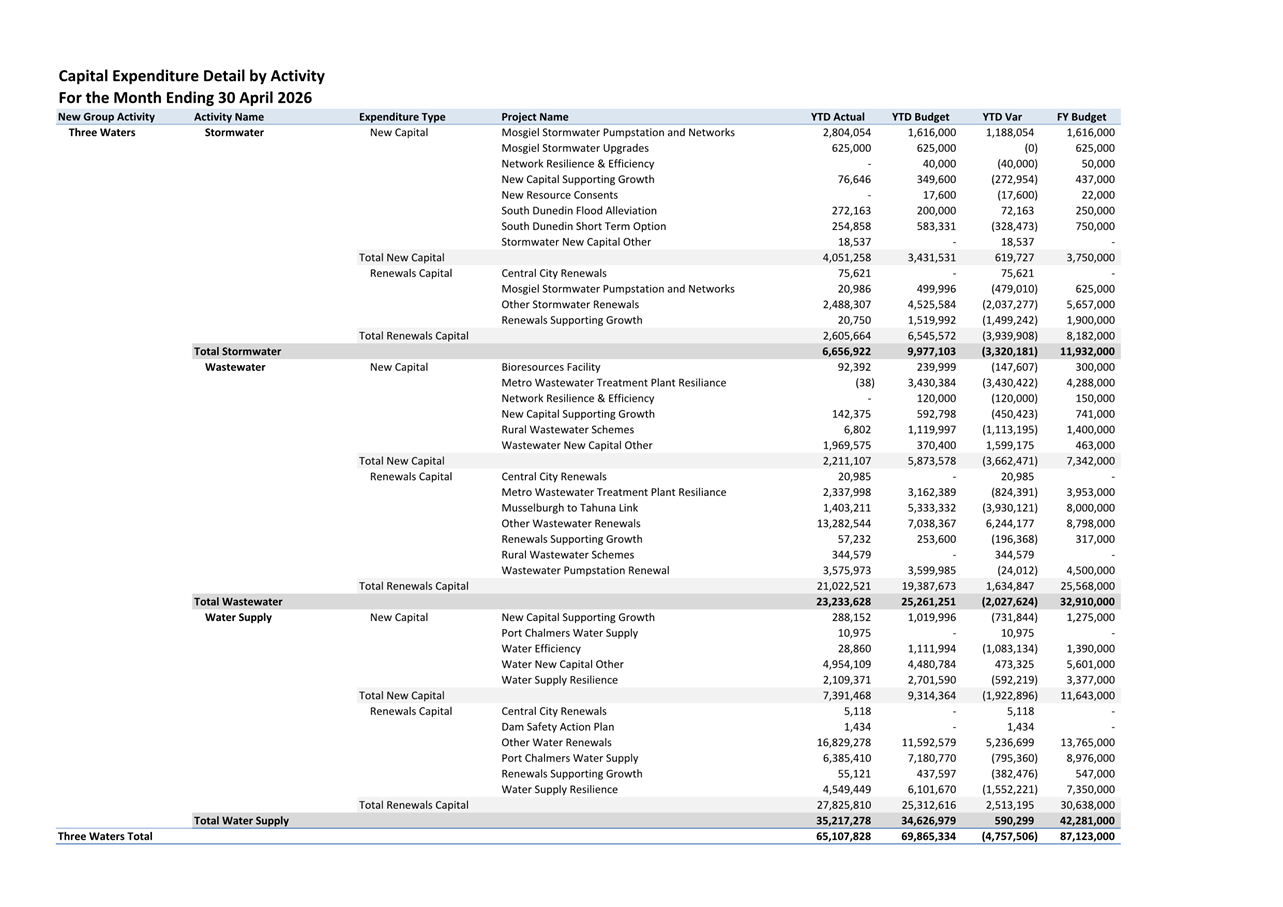
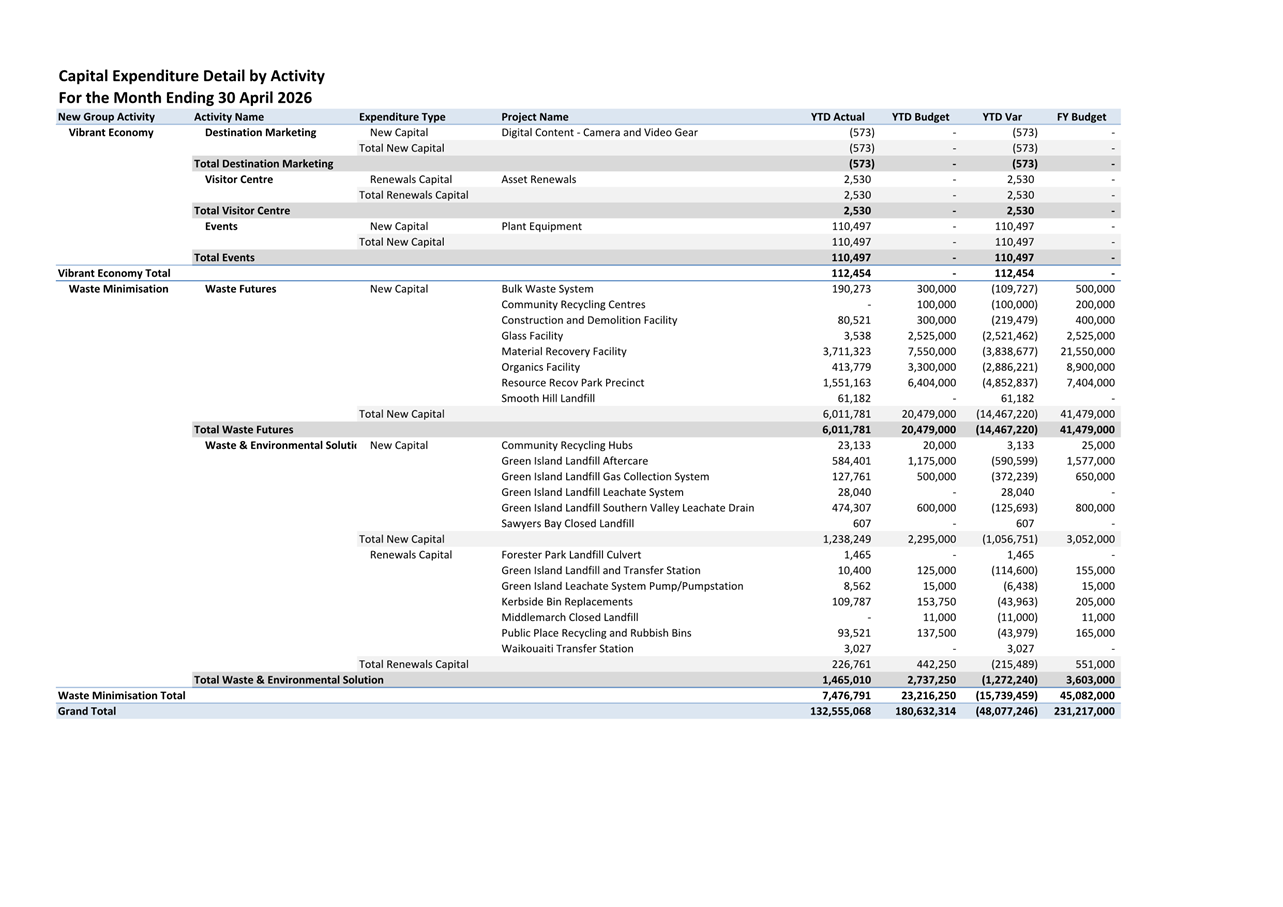
5 Capital
expenditure was $132.555 million for the period ended 30 April 2026 or 73.4% of
the year-to-date budget.
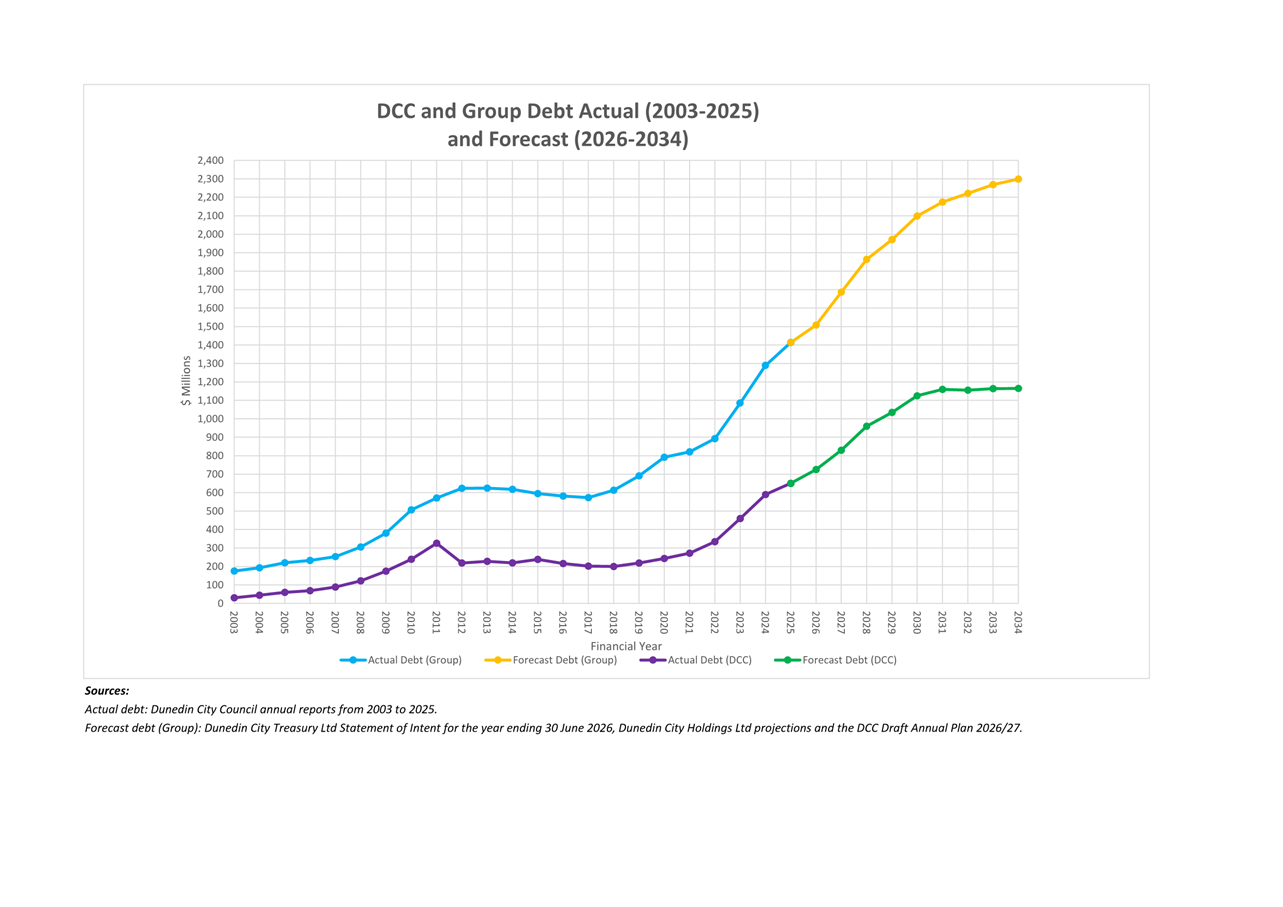
6 The
total loan balance at 30 April 2026 was $697.773 million which was $86.400 million
less than budget.
NEXT STEPS
7 Month
end financial reports will continue to be presented to future Council or
Finance and Performance Committee meetings. The latest report will also be
provided to the Audit, Risk and Assurance Committee.
Signatories
|
Author:
|
Lawrie Warwood - Management Accountant
|
|
Authoriser:
|
Hayden McAuliffe - Financial Services Manager
Carolyn Allan - Chief Financial Officer
|
Attachments
|
|
Title
|
Page
|
|
⇩a
|
Financial Update
|
59
|
|
⇩b
|
Statement of Financial
Performance
|
74
|
|
⇩c
|
Statement of Financial
Position
|
75
|
|
⇩d
|
Statement of Cashflows
|
76
|
|
⇩e
|
Capital Expenditure
Summary
|
77
|
|
⇩f
|
Capital Expenditure Detailed
|
79
|
|
⇩g
|
Statement of Operating
Variances
|
85
|
|
⇩h
|
Debt Graph
|
86
|
|
|
Audit, Risk and Assurance Committee
30 June 2026
|
|
|
Audit, Risk and Assurance Committee
30 June 2026
|
|
|
Audit, Risk and Assurance Committee
30 June 2026
|
|
|
Audit, Risk and Assurance Committee
30 June 2026
|
|
|
Audit, Risk and Assurance Committee
30 June 2026
|
|
|
Audit, Risk and Assurance Committee
30 June 2026
|
|
|
Audit, Risk and Assurance Committee
30 June 2026
|
|
|
Audit, Risk and Assurance Committee
30 June 2026
|
|
|
Audit, Risk and Assurance Committee
30 June 2026
|
Waipori Fund - Quarter Ending 31 March 2026
Department: Finance
EXECUTIVE SUMMARY
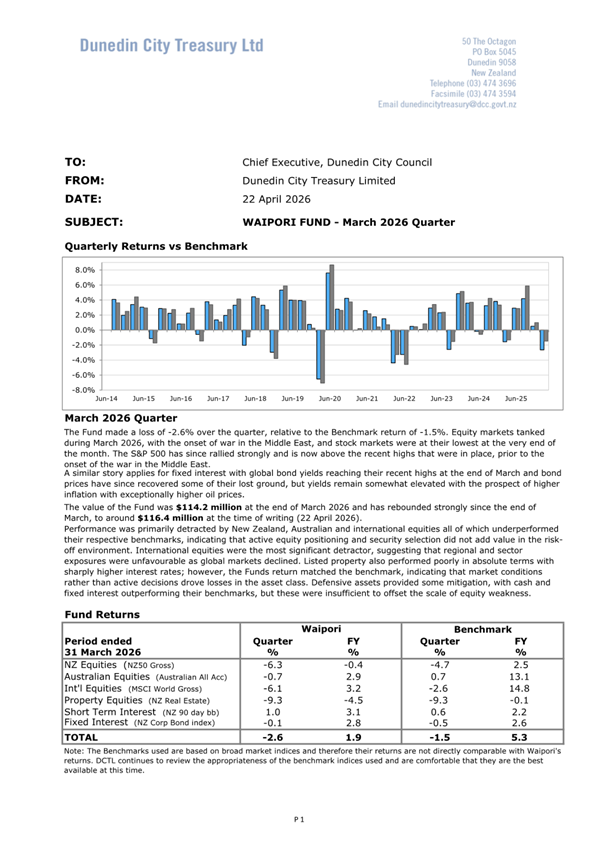
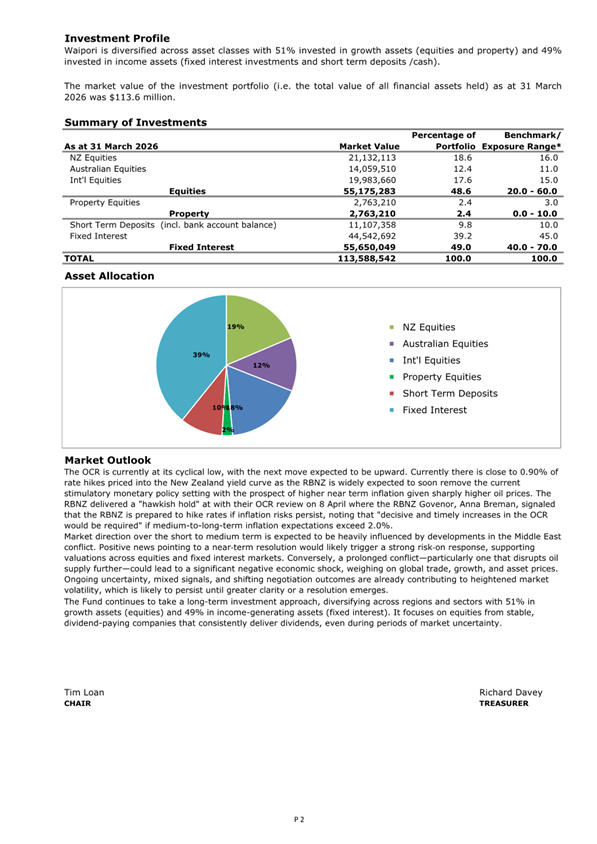
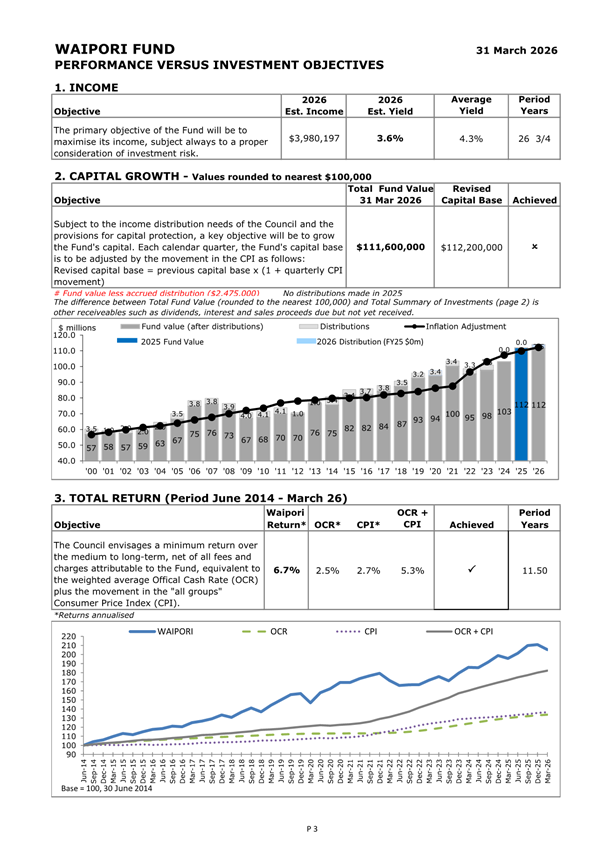
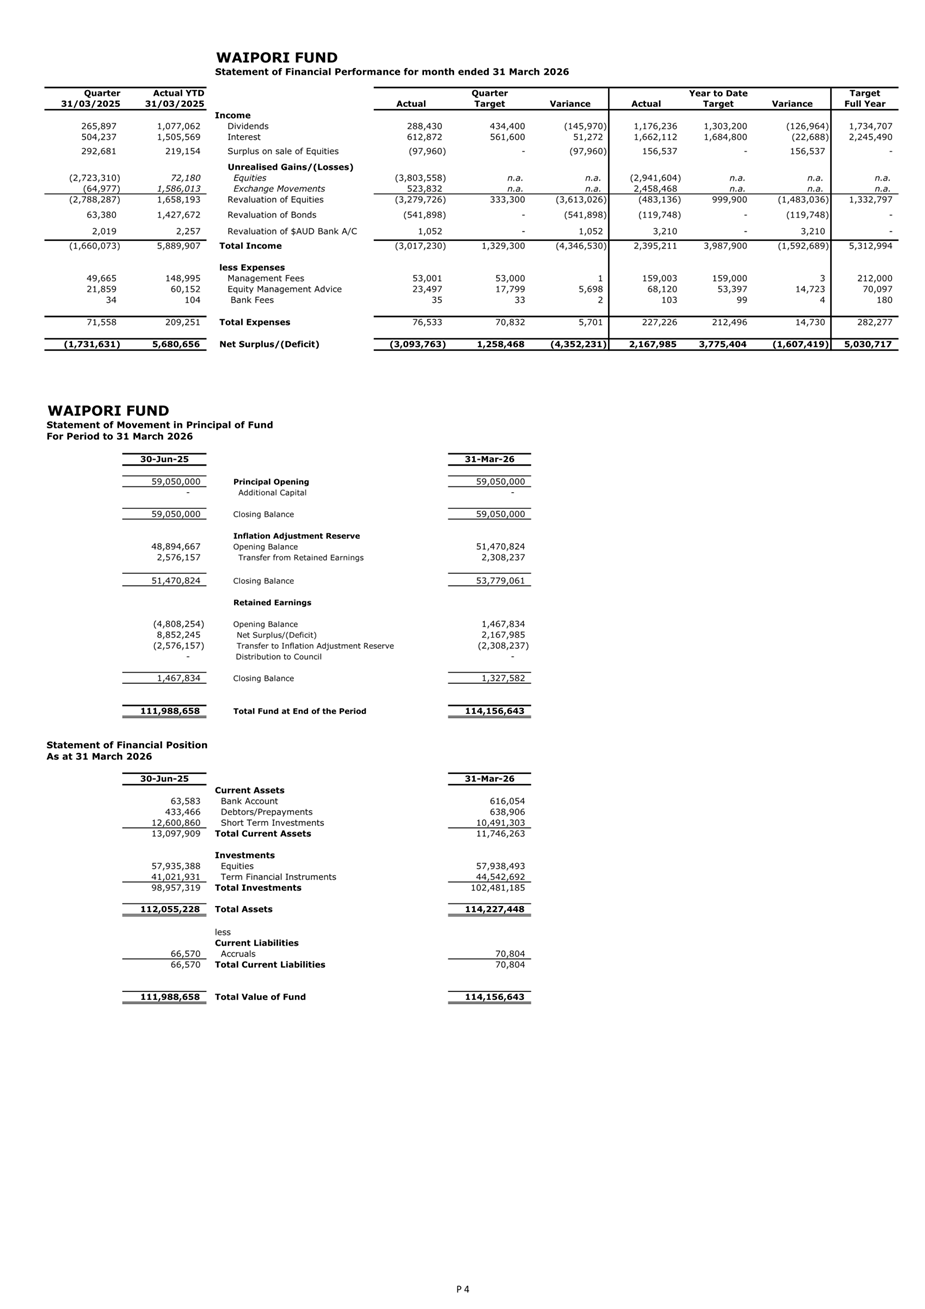
1 The
attached report from Dunedin City Treasury Limited provides information on the
results of the Waipori Fund for the quarter ended 31 March 2026.
RECOMMENDATIONS
That the Committee:
a) Notes the report from
Dunedin City Treasury Limited on the Waipori Fund for the quarter ended 31
March 2026.
DISCUSSION
2 The
Waipori Fund Statement of Investment Policy and Objectives (SIPO) requires
quarterly reporting on the performance and financial position of the fund.
3 Dunedin
City Treasury Limited has provided the Waipori Fund report for the
March 2026 quarter. The report is provided as Attachment A.
OPTIONS
4 As
this is a noting report, no options are provided.
NEXT STEPS
5 Quarterly
reporting on the performance and financial position of the fund will be
provided to future meetings of either the Finance and Performance Committee or
Council. In addition, they are provided to the Audit, Risk and Assurance
Committee.
Signatories
|
Authoriser:
|
Carolyn Allan - Chief Financial Officer
|
Attachments
|
|
Title
|
Page
|
|
⇩a
|
Waipori Fund March 2026
Quarter
|
90
|
|
SUMMARY OF CONSIDERATIONS
|
|
Fit with purpose of Local Government
This decision enables democratic local
decision making and action by, and on behalf of, communities.
|
|
Fit with strategic framework
|
|
Contributes
|
Detracts
|
Not applicable
|
|
Social Wellbeing Strategy
|
☐
|
☐
|
✔
|
|
Economic Development Strategy
|
☐
|
☐
|
✔
|
|
Environment Strategy
|
☐
|
☐
|
✔
|
|
Arts and Culture Strategy
|
☐
|
☐
|
✔
|
|
3 Waters Strategy
|
☐
|
☐
|
✔
|
|
Future Development Strategy
|
☐
|
☐
|
✔
|
|
Integrated Transport Strategy
|
☐
|
☐
|
✔
|
|
Parks and Recreation Strategy
|
☐
|
☐
|
✔
|
|
Other strategic projects/policies/plans
|
☐
|
☐
|
✔
|
Reporting on the performance of the Waipori Fund does not
contribute directly to the Strategic Framework.
|
|
Māori Impact Statement
Investment returns from the Waipori Fund impact on the
level of rates payable and therefore impact across all Dunedin communities
including Māori.
|
|
Sustainability
There are no impacts for sustainability.
|
|
Zero carbon
There
are no impacts for zero carbon.
|
|
LTP/Annual Plan / Financial Strategy /Infrastructure
Strategy
There are no implications for LTP / Annual Plan /
Financial Strategy / Infrastructure Strategy.
|
|
Financial considerations
Financial considerations are presented in the Waipori Fund
report for the March 2026 quarter.
|
|
Significance
This report is considered to be of low significance in
terms of the Council’s Significance and Engagement Policy.
|
|
Engagement – external
There has been no external engagement.
|
|
Engagement - internal
There has been no internal engagement.
|
|
Risks: Legal / Health and Safety etc.
There are no identified risks.
|
|
Conflict of Interest
There are no known conflicts of interest.
|
|
Community Boards
There are no implications for Community Boards.
|
|
|
Audit, Risk and Assurance Committee
30 June 2026
|
|
|
Audit, Risk and Assurance Committee
30 June 2026
|
DCC Policy Update Report
Department: Finance and Business Information Services
EXECUTIVE SUMMARY
1 This
report provides an update on DCC policies identified in the Audit, Risk and
Assurance Committee (ARAC) Workplan.
RECOMMENDATIONS
That the Committee:
a) Notes the Policy
Update Report – June 2026.
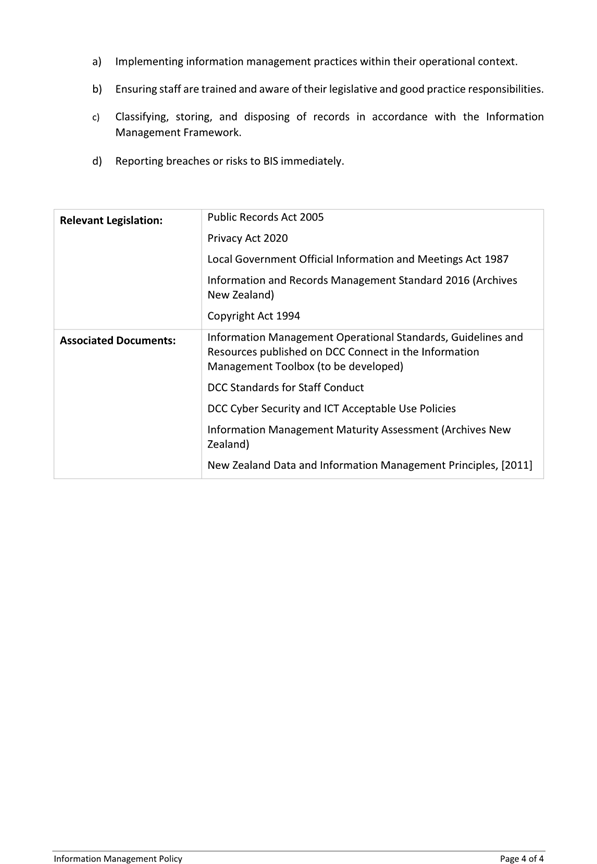
b) Notes the Information
Management Policy (Attachment A)
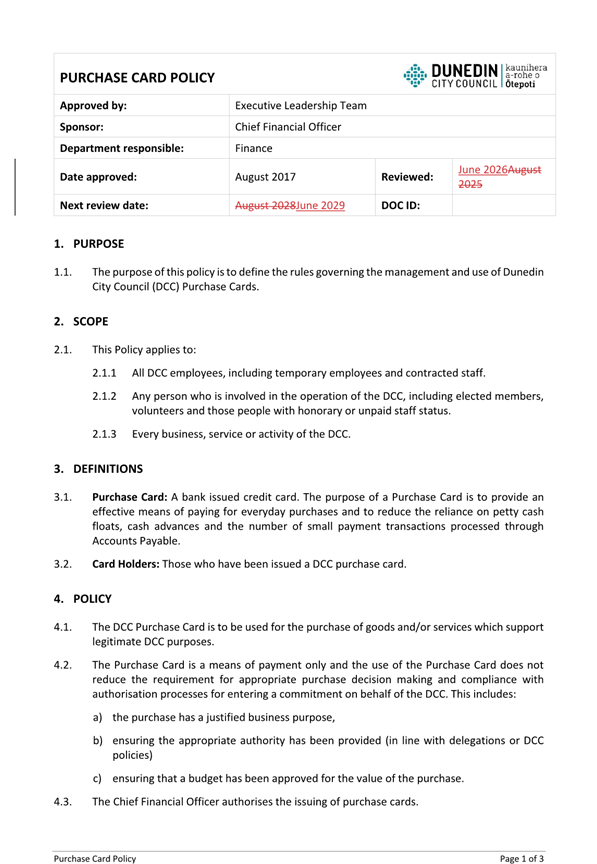
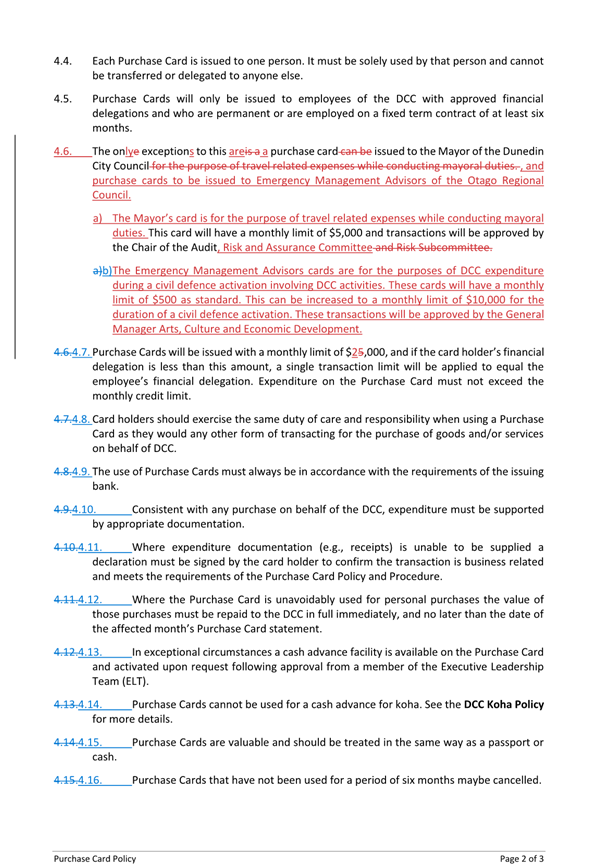
c) Approves the updated
Purchase Card Policy (Attachment B).
DISCUSSION
2 The
following policies are undergoing review:
a) Asset
Management Policy: A working group has been set-up to review and update the
Asset Management Policy including the recommendations from the Asset Management
Policy Audit. This policy will be a high-level principles-based policy that
will support consistency of asset management practices across the DCC. This
policy is expected to be presented to ARAC at the December meeting.
b) Asset
Disposal and Write-Off Policy: This policy is now in the final stages of
review; the proposed policy and guidance are being tested against similar
policies developed by other local government entities/CCO’s. This policy
and the guidelines are expected to be presented to ARAC at the December
meeting.
c) ICT
Acceptable Use Policy: A draft “Digital Acceptable Use Policy”
is under development to replace the current ICT Acceptable Use Policy. Further
review is underway with Business Information Services, People and Capability,
Legal, and the Privacy Officer before going through the formal approval process.
A timeframe for this work has not been developed.
d) Leave
Management Policy: As the government has signalled there will be updates to
the legislation (Holidays Act reform) the review of this policy is on-hold
until those changes have occurred. The expected review and delivery date for
this policy has not been set.
e) Staff
Code of Conduct: Following the organisational values refresh there has been
review and development of a number of policies managed by the People and
Capability team. This document is expected to be presented to ARAC at the
September meeting. The Staff Code of Conduct is being updated to provide:
· A
principles-based document that sets clear expectations for behaviour and
decision-making.
· A shift away
from a primary focus on unacceptable behaviour to a strengths-based approach
grounded in the values of commitment, accountability, wellbeing, and
collaboration.
· Greater
emphasis on the positive behaviours that support a respectful, inclusive, and
high-performing workplace.
f) Protected
Disclosures (Whistleblower) Policy: This policy has had some minor edits to
provide contact details for those who can receive protected disclosures, that
version is live on the DCC website. Further review is on-going including
development of a fraud response plan for employees involved in investigations.
Investigation is underway for implementing a protected disclosures hotline
which will allow for anonymous reporting. This policy and the procedures
are expected to be presented to ARAC at the September meeting.
g) Risk
Management Policy: As recruitment is underway for a new Risk Lead, the
expected review and delivery date for this policy has not been set.
h) Health,
Safety and Wellbeing Policy: This policy has undergone a high-level review
and the review date has been pushed back 12 months to November 2026. The
current review of the policy will look at aligning to the new organisational
values. The charter is also under review by the CEO and Mayor. This policy and
the charter are expected to be presented to ARAC at the December meeting.
i) Treasury
Risk Management Policy: This policy is reviewed every three years as a part
of the 10-year plan process. Forex Limited are currently providing an external
review of the policy. This policy will be brought to ARAC at the September
meeting to allow for feedback before it goes to Council for approval.
3 After
the review process, updated copies of DCC policies will be provided to ARAC for
feedback or approval.
Information Management Policy
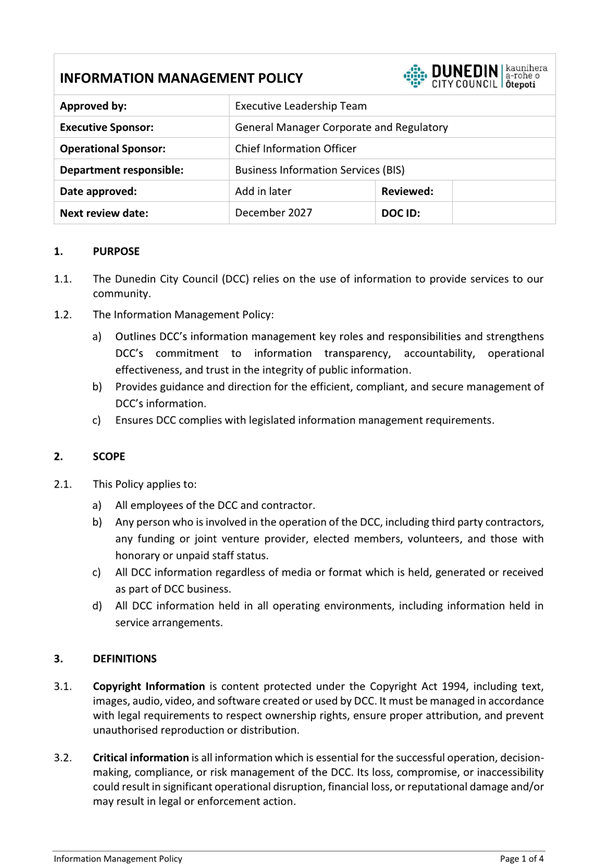
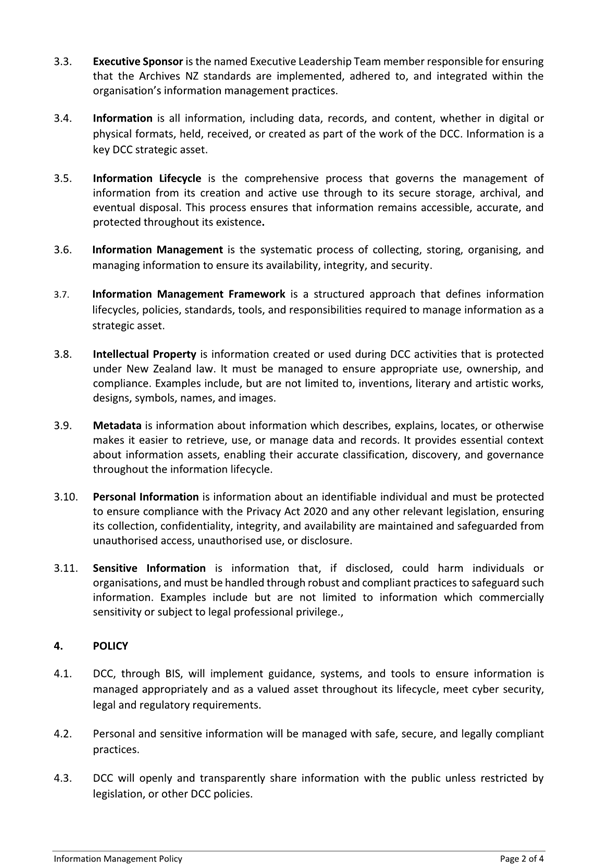
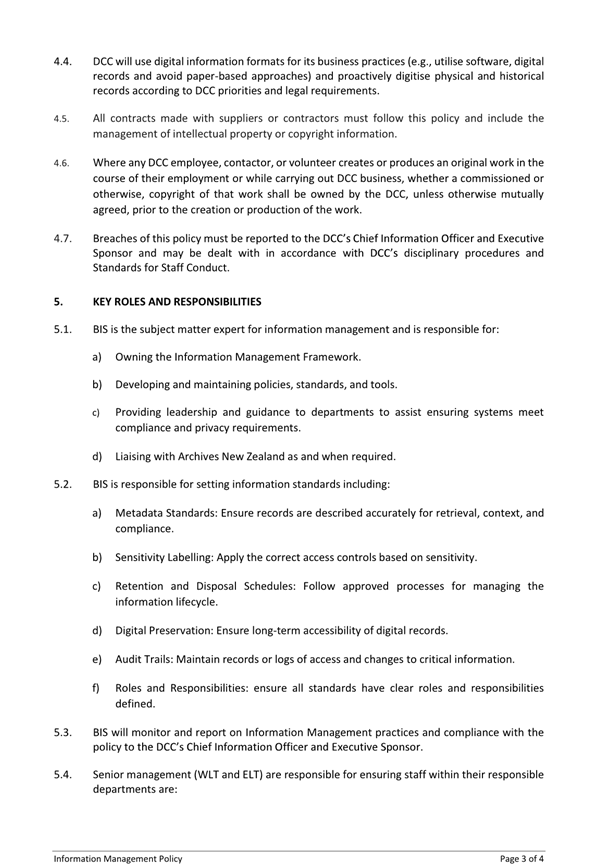
4 Attachment
A provides a copy of the Information Management Policy to ARAC for noting. The
policy was approved by the Executive Leadership Team in December 2025.
5 An
internal audit on Records Management recommended that the DCC develop a new
policy for information management that covered the requirements of the
Information and Records Management Standard 2016.
6 The
attached Information Management Policy has been developed by Business
Information Services and reviewed by the Assurance Manager and Legal Services.
7 The
Information Management Policy has been developed to align with:
a) Public
Records Act 2005
b) Privacy Act
2020
c) Local
Government Official Information and Meetings Act 1987
d) Information
and Records Management Standard (Archives New Zealand 2016)
8 Information
management policies from other councils were examined to support consistency in
the wording and approach for information management practices.
9 This
policy has been written at a high level, with the Information Management
Operational Standards, Guidelines and Resources undergoing development.
10 The
Information Standards are under development to work alongside the policy, and
cover five core standards of:
a) Information
Management Lifecycle: A high-level end-to-end model for how information is
created, stored, used, maintained, and eventually disposed of in a compliance
with legal and business requirements.
b) Information
Access, Privacy and Security: Ensures information is accessible while
protecting sensitive information, meeting privacy obligations, and enabling
open-by-default transparency while adopting a digital-first approach.
c) Information
Storage and Approved Repositories: Specifies approved locations for storing
information. Ensures reliability, accessibility, and legal compliance while
prevention use of non-compliant locations.
d) Information
Asset Register: Documents the organisation’s information assets,
ownership, sensitivity, risks, and dependencies – reducing duplication,
improving accountability, and supporting risk and retention decisions.
e) Metadata
and Classification Standard: Ensures consistent metadata and classification
so information is searchable, trustworthy, retainable, migratable, and secure.
11 These
standards will provide a framework for departments on how to view and manage
information. The standards will provide a maturity assessment for different
types of information and where improvements should be made. Work is underway to
have the standards used early in project work to ensure new information
management processes are compliant by design.
Purchase Card Policy
12 The
Purchase Card Policy is not due for review until August 2028, however, a few
areas have been identified for change.
13 This
report is seeking approval for the following edits to be made to the Purchase
Card Policy, as outlined in Attachment B:
a) Update
section 4.6 to include two identified Civil Defence roles (employed by the
Otago Regional Council) as an exception role, to be authorised to hold a DCC
purchase card. The purpose of this is for DCC business during a civil defence
activation, and to keep the facility operational (for example, diesel for the
boilers). The cards will hold a $500 value and will be increased to a $10,000
limit upon a civil defence activation involving DCC activities. This is to
provide emergency funding resiliency as cards can only be issued to a specific
holder, and it can be difficult to guarantee which DCC staff will be involved
in an activation. This approach has been considered as being the most
pragmatic.
b) Update
section 4.6 to refer to the “Chair of the Audit, Risk and Assurance
Committee”.
c) Update
section 4.7 to have the standard limit for purchase cards of $2,000, to reduce
exposure risk.
NEXT STEPS
14 Any
policies that are approved will be presented to employees alongside supporting
materials e.g., guidance, procedures, and FAQs.
Signatories
|
Author:
|
Hayley Knight - Assurance Manager
Graeme Riley - Chief Information Officer
|
|
Authoriser:
|
Carolyn Allan - Chief Financial Officer
Paul Henderson - General Manager Corporate and Regulatory
Services
|
Attachments
|
|
Title
|
Page
|
|
⇩a
|
Information Management
Policy
|
101
|
|
⇩b
|
Purchase Card Policy -
June 2026 draft track changes
|
105
|
|
SUMMARY OF CONSIDERATIONS
|
|
Fit with purpose of Local Government
This report provides an update on Council
Policy documents as identified by the Audit Risk and Assurance Committee
Workplan, which is a regulatory function considered good quality and cost effective.
|
|
Fit with strategic framework
|
|
Contributes
|
Detracts
|
Not applicable
|
|
Social Wellbeing Strategy
|
✔
|
☐
|
☐
|
|
Economic Development Strategy
|
✔
|
☐
|
☐
|
|
Environment Strategy
|
✔
|
☐
|
☐
|
|
Arts and Culture Strategy
|
✔
|
☐
|
☐
|
|
3 Waters Strategy
|
✔
|
☐
|
☐
|
|
Spatial Plan
|
✔
|
☐
|
☐
|
|
Integrated Transport Strategy
|
✔
|
☐
|
☐
|
|
Parks and Recreation Strategy
|
✔
|
☐
|
☐
|
|
Other strategic projects/policies/plans
|
✔
|
☐
|
☐
|
The Audit Risk and Assurance Committee monitors and
provides assurance for the effective review and management of core Council Policies
– thereby supporting business controls and delivery, governance and the
realisation of strategic objectives.
|
|
Māori Impact Statement
There are no know impacts for mana whenua.
|
|
Sustainability
There are no implications for sustainability.
|
|
LTP/Annual Plan / Financial Strategy /Infrastructure
Strategy
There are no known implications.
|
|
Financial considerations
No financial implications have been identified.
|
|
Significance
This report is considered low in terms of the
Council’s Significance and Engagement Policy.
|
|
Engagement – external
No external engagement required for the Information
Management Policy as it is an internal operating policy.
Civil Defence staff were engaged to understand the needs
for activations involving DCC activities.
|
|
Engagement - internal
For the development of the Information Management Policy,
Business Information Services, in house Legal, Assurance Manager have been
engaged.
For the update of the Purchase Card Policy the Finance
team and Civil Defence team have been engaged.
|
|
Risks: Legal / Health and Safety etc.
A failure to maintain effective and appropriate Policy
framework across core Council functions exposes the DCC to a range of
operational and strategic risks, including financial, business and service
performance, community, business and sector confidence, as well as potential
fraud and litigation.
|
|
Conflict of Interest
No conflicts of interest have been identified.
|
|
Community Boards
There are no known implications for the Community Boards.
|
|
|
Audit, Risk and Assurance Committee
30 June 2026
|
|
|
Audit, Risk and Assurance Committee
30 June 2026
|
|
|
Audit, Risk and Assurance
Committee
30 June 2026
|
Resolution to Exclude the
Public
That the Audit, Risk and
Assurance Committee:
Pursuant to the provisions of the
Local Government Official Information and Meetings Act 1987, exclude the public
from the following part of the proceedings of this meeting namely:
|
General subject of the matter to be considered
|
Reasons
for passing this resolution in relation to each matter
|
Ground(s) under
section 48(1) for the passing of this resolution
|
Reason for
Confidentiality
|
|
C1
Confirmation of the Confidential Minutes of Audit, Risk and Assurance
Committee meeting - 27 March 2026 - Public Excluded
|
S7(2)(i)
The
withholding of the information is necessary to enable the local authority to
carry on, without prejudice or disadvantage, negotiations (including
commercial and industrial negotiations).
S7(2)(h)
The
withholding of the information is necessary to enable the local authority to
carry out, without prejudice or disadvantage, commercial activities.
S7(2)(b)(ii)
The
withholding of the information is necessary to protect information where the
making available of the information would be likely unreasonably to prejudice
the commercial position of the person who supplied or who is the subject of
the information.
S7(2)(b)(i)
The
withholding of the information is necessary to protect information where the
making available of the information would disclose a trade secret.
S7(2)(c)(i)
The
withholding of the information is necessary to protect information which is
subject to an obligation of confidence or which any person has been or could
be compelled to provide under the authority of any enactment, where the
making available of the information would be likely to prejudice the supply
of similar information or information from the same source and it is in the
public interest that such information should continue to be supplied.
S7(2)(a)
The
withholding of the information is necessary to protect the privacy of natural
persons, including that of a deceased person.
S7(2)(g)
The
withholding of the information is necessary to maintain legal professional
privilege.
|
.
|
|
|
C2
Treasury Risk Management Compliance Report
|
S7(2)(h)
The
withholding of the information is necessary to enable the local authority to
carry out, without prejudice or disadvantage, commercial activities.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
|
|
C3
Dunedin City Holdings Ltd - Update on Audit and Risk Activity
|
S7(2)(b)(ii)
The
withholding of the information is necessary to protect information where the
making available of the information would be likely unreasonably to prejudice
the commercial position of the person who supplied or who is the subject of
the information.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
|
|
C4
Risk Management Update and Deep Dive
|
S7(2)(h)
The
withholding of the information is necessary to enable the local authority to
carry out, without prejudice or disadvantage, commercial activities.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
|
|
C5
Risk Assurance: Cybersecurity Update
|
S7(2)(h)
The
withholding of the information is necessary to enable the local authority to
carry out, without prejudice or disadvantage, commercial activities.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
|
|
C6
Underwriting Policy
|
S7(2)(g)
The
withholding of the information is necessary to maintain legal professional
privilege.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
|
|
C7
Assurance Dashboard
|
S7(2)(h)
The
withholding of the information is necessary to enable the local authority to
carry out, without prejudice or disadvantage, commercial activities.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
The information in this
report is commercially sensitive..
|
|
C8
Insurance Update Report - June 2026
|
S7(2)(h)
The
withholding of the information is necessary to enable the local authority to
carry out, without prejudice or disadvantage, commercial activities.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
|
|
C9
Internal Audit: Workplan Update
|
S7(2)(b)(i)
The
withholding of the information is necessary to protect information where the
making available of the information would disclose a trade secret.
S7(2)(c)(i)
The
withholding of the information is necessary to protect information which is
subject to an obligation of confidence or which any person has been or could
be compelled to provide under the authority of any enactment, where the
making available of the information would be likely to prejudice the supply
of similar information or information from the same source and it is in the
public interest that such information should continue to be supplied.
S7(2)(h)
The
withholding of the information is necessary to enable the local authority to
carry out, without prejudice or disadvantage, commercial activities.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
|
|
C10
Audit New Zealand Update
|
S7(2)(i)
The
withholding of the information is necessary to enable the local authority to
carry on, without prejudice or disadvantage, negotiations (including
commercial and industrial negotiations).
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
|
|
C11
External Audit: Recommendations and Actions Update
|
S7(2)(c)(i)
The
withholding of the information is necessary to protect information which is
subject to an obligation of confidence or which any person has been or could
be compelled to provide under the authority of any enactment, where the
making available of the information would be likely to prejudice the supply of
similar information or information from the same source and it is in the
public interest that such information should continue to be supplied.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
|
|
C12
Legal Matters
|
S7(2)(g)
The
withholding of the information is necessary to maintain legal professional
privilege.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
|
|
C13
Protected Disclosure and Investigation Register - June 2026
|
S7(2)(a)
The
withholding of the information is necessary to protect the privacy of natural
persons, including that of a deceased person.
S7(2)(c)(i)
The
withholding of the information is necessary to protect information which is
subject to an obligation of confidence or which any person has been or could
be compelled to provide under the authority of any enactment, where the
making available of the information would be likely to prejudice the supply
of similar information or information from the same source and it is in the
public interest that such information should continue to be supplied.
|
S48(1)(a)
The public conduct of
the part of the meeting would be likely to result in the disclosure of
information for which good reason for withholding exists under section 7.
|
|
This resolution is made in
reliance on Section 48(1)(a) of the Local Government Official Information and
Meetings Act 1987, and the particular interest or interests protected by
Section 6 or Section 7 of that Act, or Section 6 or Section 7 or Section 9 of
the Official Information Act 1982, as the case may require, which would be
prejudiced by the holding of the whole or the relevant part of the proceedings
of the meeting in public are as shown above after each item.